These cards are your ticket to sky-high point earning potential, hefty welcome bonuses, solid ongoing earn rates, and a premium selection of travel-centric perks.
7+
Great
These cards might have slightly less impressive points earning or sign-up bonuses.
5+
Standard
Reliable workhorses for frequent flyers who want a well-balanced card. Enjoy decent point earning potential, competitive rates, and a good mix of practical perks.
0+
Basic
The entry point in the frequent flyer market. Their sign-up bonuses and ongoing earn rates might not be as generous.
Updated by Finder's senior money editor Richard Whitten in September 2026.
What is a Qantas frequent flyer credit card?
A Qantas frequent flyer credit card lets you earn Qantas Points through the Qantas Frequent Flyer program.
There are two main types:
A Qantas Money credit card. This is Qantas' own money brand, though the cards themselves are issued through other banks.
A Qantas-partnered credit card from a bank or credit card company. All the Big 4 banks and card companies offer cards which can earn Qantas Points.
How to earn Qantas Points with your credit card
You earn Qantas Points with your credit card by:
Spending. A Qantas card will let you earn Qantas Points when you spend using the card for eligible purchases. Earn rates range from half a point per dollar spent up to 1 point per dollar spent or more. Typically eligible purchases excludes cash advances, balance transfers and BPAY payments. That means payments for tax, mortgages and rent don't earn points (even assuming your card allows them, which many don't).
Bonus sign-up offers. The best Qantas cards have major sign-up bonuses. Typically these require you to spend a fixed amount in the first few months of card ownership. Some cards will also offer bonuses if you sign up for a second year.
Converting your existing bank reward points into Qantas Points. Check the fine print on your rewards credit card to see if it lets you do this.
Types of Qantas credit cards
Everyday, Platinum, Black, Premium, Business Premium: these credit card names aren't helping anyone!
But you can break Qantas cards down into a few groups based on:
The points you earn by $1 spent.
The annual fee.
The perks you get.
The most expensive cards have higher fees, but you earn more points and get more perks.
There are also Qantas business cards. These cards offer stacks of points and high earn rates. But the annual fees are higher and you'll need an ABN, plus a minimum amount of annual revenue to qualify.
Our expert says
"Qantas is my favourite frequent flyer scheme because there are so many ways to redeem your points for flights, including really good value domestic options. You can boost earning on your Qantas card further by shopping at Woolworths and converting your Everyday Rewards into Qantas Points. If you convert your Qantas Points to flights, that's much better value that just getting $10 off vouchers at Woolworths."
The bottom line - the best Qantas credit card is the one you can afford. The more points and perks the better, obviously. But you have to balance this against the annual fee cost and the spend requirements to get the bonus points.
Here's how you do it:
Look at the bonus points offer. A really good credit card should come with 50,000 bonus Qantas Points or more. Just make sure you can meet the spending conditions to get the points.
Compare the earn rate. As a general guide, 1 Qantas Point per $1 is usually seen as a good earn rate.
Factor in the annual fee. Let's say your card has a $350 annual fee. That's quite high for a credit card. But if the points you earn in a year pay for a couple of domestic reward flights you've already earned back the value of the fee.
Compare purchase rates. Qantas credit cards have higher interest rates on purchases. This can make these cards expensive if you don't pay the card off on time. If you struggle to pay off your balance, a frequent flyer points card isn't a wise choice
Don't forget about eligibility. Many credit cards have minimum incomes and other requirements. Because Qantas credit card fees and interest rates are higher than average, you usually need to have at least a good credit score.
How to get the most from a Qantas credit card
Earn your bonus. Make sure you meet the conditions to get the bonus points. Use the card when you spend to earn points on eligible purchases.
Use the points for flights. You can use Qantas Points on shopping, rewards flights or upgrades. You get the most value out of your points booking reward flights or upgrades.
Pay the card off in full. Don't get stuck carrying a balance on your Qantas card. The high interest rate will really start to hurt you.
Review your card after 12 months. You have to pay the annual card fee every year. Before you do, review the card. Are you taking full advantage of the card? Is there a better offer out there?
Finder Scores for Qantas credit cards explained
9+ Excellent - These Qantas credit cards offer big points bonuses, high earn rates and premium perks.
7+ Great - These cards might have slightly less impressive points earning or sign-up bonuses than the absolute best Qantas credit cards on the market.
5+ Satisfactory - These are solid but unspectacular cards for frequent flyers.
Less than 5 - Basic - Entry-level cards with sign-up bonuses and ongoing earn rates that are lower than average.
More about Finder Score
The Finder Score is an easy way you can figure out which Qantas credit cards really offer first class value.
Here's how the score works:
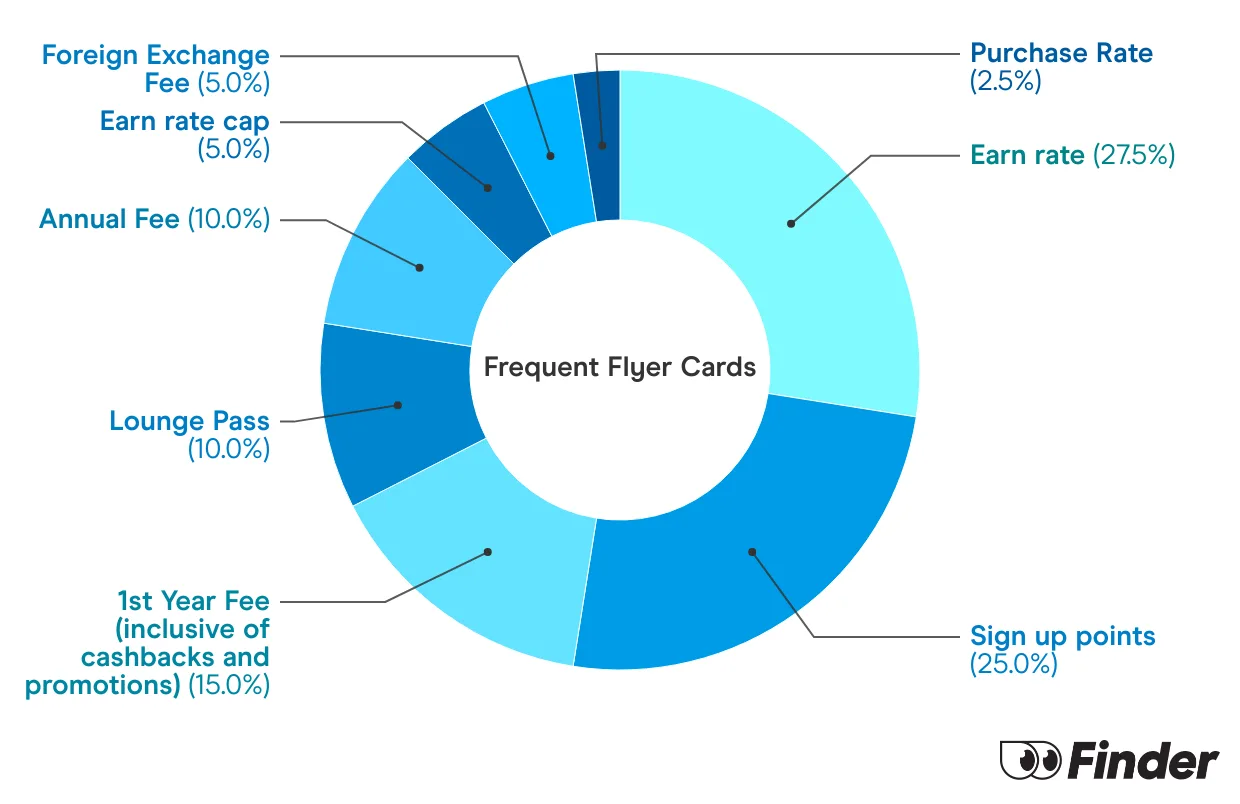
We analyse credit cards that let you earn Qantas Points and assess 8 features, giving a score for each one.
Then we combine these scores using a weighted methodology (because some features are more important than others).
This gives us a final score out of 10: the Finder Score.
In the Qantas frequent flyer category we only consider credit cards that:
Link to the Qantas Frequent Flyer program.
Let you earn points directly based on spending.
Are available to general consumers.
Scores are category-specific. One card might get a 10 in the Qantas Frequent Flyer category but only a 7 in the balance transfer category.
The Finder Score methodology is designed by our insights and editorial team. Commercial partners carry no weight and all products are reviewed objectively.
Feature
Definition
Assessment
Weight
Earn rate
Points earned for every dollar spent on eligible purchases
Points awarded per dollar (up to 1.5)
27.5%
Sign-up points
Bonus points earned for signing up and meeting spending requirements
Total bonus points offered (up to 200,000)
25%
Purchase rate
Interest rate on new purchases
Lower rates receive higher scores (up to 23.99% max)
Frequently asked questions about Qantas credit cards
Each month, we analyse the current value of Qantas Points. Bottom line: a single Qantas Point is worth anywhere from 0.5 cents to 8 cents. The best-value attainable option for most folks is a rewards flight, which will be worth between 1 cent and 2 cents. The higher-value options such as upgrades are great, but they're very hard to get if you're not a Qantas Gold or Platinum flyer.
The points you earn on a Qantas credit card are usually added to your Qantas Frequent Flyer account each month, around the time you get your credit card statement.
If you've earned bonus Qantas Points, these will usually be added to your frequent flyer account within 8 to 12 weeks of meeting a spend requirement.
Some dedicated Qantas Points chasers will choose a card based on the bonus points offer, keep it for a while and then look for another sign-up offer.
This strategy is known as credit card churning. You can potentially get lots of points doing this but it's getting harder to do and has some risks:
Having multiple cards limits your chances of getting new ones approved.
Too many applications in a short time can hurt your credit score.
If you carry a balance on any card, you'll have to pay interest – not to mention all the annual fees.
Many credit card companies limit bonus points offers to new customers only.
The Qantas Money Titanium Credit Card currently has one of the biggest bonus Qantas Points offers in Australia, with 150,000 bonus Qantas Points when you spend $5,000 in the first months of approval as a new cardholder. It's also one of the most exclusive frequent flyer credit cards on the market, with a minimum income requirement of $200,000 and a $1,200 annual fee.
If you meet the criteria for the bonus points, once they are credited to your account, you can cancel your credit card at any time. Just remember that you'll need to pay off the account balance before you cancel it.
It depends on your earn rate and spending. You need at least 8,000 Qantas Points for a Classic Flight Reward, which would mean spending at least $8,000 on a card that earned 1 point per $1. On a card that earned 0.5 points per $1, you'd need to spend at least $16,000.
Qantas Points only expire if you do not earn or spend Qantas Points for 18 consecutive months. This means paying with a Qantas credit card is one way to avoid points expiring, because you'll earn Qantas Points per $1 spent. Check out Finder's guide to points expiry for more information and how you can avoid having your points expire.
As of July 2026, the Qantas American Express Discovery Card and the BankVic Qantas Visa Card have ongoing $0 annual fees.
Sarah is the author of How to Raise Rich Kids. With over 20 years of experience in property, finance and investment journalism, she is a trusted expert whose insights regularly appear across television, radio and print media, including Sunrise, Channel 7 News, Bloomberg and Yahoo! Finance. She has previously served as managing editor for Your Investment Property and Australian Broker. Her expert advice has been shared in the media over 4,000 times. Sarah holds a Bachelor’s degree in Communications and a Tier 1 Generic Knowledge certification, which complies with ASIC standards.
See full bio
Sarah's expertise
Sarah
has written
262
Finder guides across topics including:
Angus Kidman is Finder’s global Editor-at-Large and an award-winning journalist with over 30 years of experience in tech, travel and finance. He was previously the editor of Lifehacker Australia and Australian Personal Computer, and is a recognised commentator, appearing on shows like Sunrise and The Project. A two-time IT Journalism Award winner, Angus has written for top publications such as The Sydney Morning Herald, the AFR, The Australian and Gizmodo, and is known for his expertise in travel rewards and consumer technology.
See full bio
Angus's expertise
Angus
has written
243
Finder guides across topics including:
Hi, Thanks for your reply. I will indeed go check my credit rating, as I think it is A1, but maybe others do not agree. I did provide HSBC with my SMSF statement showing almost 2 million is assets with no liabilities other than day to day.
So, maybe I have no choice and I am stuck with the Citi credit card.
Citibank advise that BPAY, or Direct Debit payments each month do not attract FF points. I am a bit perplexed as to how you now earn FF points when using a credit card…They keep saying “eligible payments”, without explaining what an eligible payment method is in real English other than their legal terms and conditions.
Are eligible payments those made through the credit card to certain vendors only? Do I have to link the card to these vendors?
Finder
JonathanMarch 1, 2016Finder
Hi Geoff, thanks for your inquiry!
Eligible purchases/ payments typically require a good/ service to be exchanged. You can earn FF points by using your credit card at the point of sale. Since direct debit payments are usually associated with paying bills and charges these transactions do not qualify for earning FF points.
Cheers,
Jonathan
GeoffFebruary 26, 2016
I made an application to HSBC for a Platinum Qantas Credit Card, but they declined me.
They advise there is no, “one” reason for their decision, but i am sure they must there must be a reason. Can I make them tell me the reason(s) for declining me?
I have had a credit card all my life, never been in default, or late payment, and my credit history should be perfect, as never any issues. My present credit card has a limit of $25,000, and they keep offering me more….The new card would have provided greater points earning ability.
The only issue maybe, is that I retired a few years ago. However, my income from my super and private investments gives me an annual income of $60,000+, and despite a few world trips each year over the last three years with Qantas in First and Business, my super balance is still going up, proving we can live within the income range.
I would have thought, some one like me with a million plus in super, with no mortgages etc is a far better risk than some person an a salary paying a mortgage and other commitments, with their job always in question…..
Finder
SallyFebruary 29, 2016Finder
Hi Geoff,
Thanks for your question and we’re sorry to hear about your declined credit card application. If your credit history is in good standing and you meet the eligibility requirements, perhaps you didn’t include all of the necessary information (such as superannuation statements and assets) to prove your income.
Declined credit card applications can have a negative impact on your credit score, so you might want to take some time comparing your options before applying for another one. In the mean time, you might like to read over the product disclosure statement to confirm which documents you need to provide to increase your chances of approval.
I hope this has helped and we’re sorry we can’t provide you with more specific information.
Cheers,
Sally
ThoiFebruary 16, 2016
Is direct debit payment considered to be an eligible purchase with BankWest Qantas transaction account? Thanks
Finder
JonathanFebruary 16, 2016Finder
Hi Thoi, thanks for your inquiry!
Direct debit payments can qualify as eligible purchases providing a good/ service is being exchanged for funds. Transactions that do not qualify as eligible purchases include cheques, any transaction which incorporates a cash-out transaction at any merchant, BPAY payments, interest charges, government charges and business related expenses. Please refer to page 3 clause 5 of the PDF I have sent to your email for the full list of ineligible transactions.
Cheers,
Jonathan
GeoffFebruary 2, 2016
My present credit card provider has advised me from May they will no longer accept payments via BPay as eligible payments to earn Qantas FF points. Is the BPay payment a common restriction?
I am thinking of using the Bank@Post as an alternative
Finder
JonathanFebruary 3, 2016Finder
Hi Geoff,
Thanks for your inquiry!
A number of banks/ issuer allow bill payments to earn Qantas FF points. So we can inform other users to this update could you please let us know who your credit card issuer is?
Thanks,
Jonathan
GeoffFebruary 4, 2016
Hi, I was looking at the HSBC card which allows bill payments to be claimed as flyer points…I am in the process of an application…But, when I look at their site, it seems to be saying they do not allow BPAY ??
“Ineligible transactions for earning points includes balance transfers, cash advances, interest free transactions and HSBC’s special promotions, business expenses, fees or charges (including government), any value charged to your card in association with a points plus pay redemption, any expenditure incurred as part of a ‘points plus pay’ transaction, a transaction which HSBC decides is fraudulent or involves the abuse of a card, a disputed debit transaction and finally BPAY transactions.”
Finder
JonathanFebruary 5, 2016Finder
Hi Geoff, thanks for your response.
That is correct, unfortunately HSBC does not allow earning points with BPAY transactions. Since earning points with BPAY payments is less common transaction the best way to approach this would be to narrow down your list of credit card options and determine whether each bank accepts BPAY payments or not. Were there any other credit cards you were considering to apply for?
Cheers,
Jonathan
GeoffFebruary 5, 2016
Hi, Any card will do that I can use my monthly payment to attract points.
My present card will have annual fees of $160. Unless I can earn sufficient points, maybe the award card is not worth it?
Maybe I go back to the old way of paying the card – A bank transfer! I do not see any reference to this as being not an eligible payment.
Finder
JonathanFebruary 8, 2016Finder
Hi Geoff,
Thanks for your inquiry!
That is correct. It is beneficial to take your annual fee into account and assess whether you earn sufficient points to justify the value of having a particular rewards card. You can compare a range of Qantas credit cards and check your options. You can compare these cards based on annual fees, interest rates, and rewards points earned per $1 spent.
Before applying, please ensure that you meet all the eligibility criteria and read through the details of the needed requirements as well as the relevant Product Disclosure Statements/Terms and Conditions when comparing your options before making a decision on whether it is right for you.
I hope this helps.
Cheers,
Jonathan
GeoffFebruary 3, 2016
Hi Jonathon,
My current provider is Cardservices – Mycard (part of the citigroup)
They have advised me about a few changes:
BPAY transaction no longer able to earn reward points.
The international transaction fee will be 3.4% of the AUD dollar conversion of any transaction made in a foreign currency.
Any transaction made with an overseas merchant in Australian Dollars, of which a 1% service and assessment fee is payable by Mycard to MasterCard
A $49.00 annual fee for the rewards program(used to be free)
Change from 1 point for each Australian Dollar to 1 point for each Australian Dollar for the first $1500 spent each statement period and 0.5 Points thereafter.
Platinum reward points earn rate reduced from 1.25 to 1 point
So, in my case, I pay my card each month via BPAY, which I have done for many years). If I can no longer earn points this way, I need to find another way of making payment(I have asked them this and they are considering my request)
OR look for a new card provider. But, now retired, obtaining a new card may not be as easy when working.
Finder
JonathanFebruary 3, 2016Finder
Hi Geoff,
Thanks for your reply!
We can confirm that Citi has cancelled the feature of earning Qantas Points with BPAY payments. Since this feature varies between banks please refer to the section ‘Which credit card issuers let you earn Qantas Points paying bills’ for an evaluation of which banks still allow this points transaction.
Please ensure that you meet all the eligibility criteria and read through the details of the needed requirements as well as the relevant Product Disclosure Statements/Terms and Conditions when comparing your options before making a decision on whether it is right for you.
Cheers,
Jonathan
AshJanuary 9, 2016
What are the affiliated shops were you earn double points
Finder
DebbieJanuary 11, 2016Finder
Hi Ash,
Thank you for your inquiry.
We can’t provide a full list of the shops where you can earn double points. These offers may also vary on the credit cards or issuers that lets you earn Qantas Points. You may want to go directly to Qantas Store website or contact a customer service representative directly, they may able to assist you further with your concern.
I suggest that you revisit the relevant product disclosure statement and terms and conditions to ensure that you got everything covered on your transactions.
The Wizitcard offers an alternative to traditional credit cards and buy now pay later, with no interest charges, a monthly fee and a virtual account – is it right for you?
Whether you’re flying interstate or overseas, having a credit card that offers complimentary flights or travel credit can help you save on your costs every year.
With contactless payments, exclusive entertainment offers and online shopping benefits, Visa credit cards offer a wide range of benefits you can enjoy with most issuers in Australia.
Understand why your bank may decline your credit card transaction and what you can to do avoid this embarrassing and inconvenient issue.
Important information about this website
Finder is a comparison service. We do not compare every product or every provider in the market.
We make money through commercial arrangements with some of the providers on this site. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement.
Our editorial content, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements.
The default order of products in our tables can be influenced by commercial arrangements. You can re-sort or filter using the controls above each table.
Some content on this site may be generated or supported by AI tools. You should verify details directly with the provider.
Finder is one of Australia's leading comparison websites. We are committed to our readers and stand by our editorial principles.
Our comparison service does not include every product or every provider in the market. Some product issuers offer their products under multiple brands or through associated companies. Where we can, we identify the underlying issuer so you can compare like with like, but you should always check with the provider directly to confirm which brand you are dealing with.
Finder is a comparison website and an intermediary. We are not a product issuer and we do not provide personal financial or credit advice. When you click a link to a product, or apply for a product through our site, you deal directly with the product issuer. We may receive a referral fee, commission or other payment from the issuer if you click through, apply or take out a product. We describe these arrangements in more detail under 'How we make money' below.
Product features, fees, terms and eligibility criteria are set by the product issuer and may change. We rely on information supplied by issuers when we present product details on our site. Before you apply for or take out any product, you should confirm the details directly with the issuer.
We earn revenue from Finder in four principal ways:
Referral fees and commissions. When you click a product link, complete an enquiry form or apply for a product through our site, we may receive a referral fee, commission or other payment from the product issuer. We may also receive payment based on the volume of leads or conversions we send to an issuer.
Sponsored placements. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement between Finder and the issuer. These labels always indicate a paid placement. We do not use them for editorial choices.
Display advertising. Banner advertising, newsletter advertising and similar display ads on our site are paid by advertisers.
Content sponsorship. Some articles, videos and social media posts are sponsored by an issuer and are clearly labelled as such.
Our editorial opinions, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements. A 'Top Pick' is an editorial choice made by our writers and editors based on the criteria described on each comparison page. A 'Top Pick' is not a personal recommendation and does not mean the product is appropriate for your circumstances.
If you would like to know whether we have a commercial arrangement with a specific product issuer, please contact us.
When products are grouped in a table or list, the default order can be influenced by commercial arrangements we have with product issuers. In some categories, sponsored or featured products appear in the top positions of the table by default, and are always labelled as such.
Other factors that influence default order include price, fees and features, and (where relevant) our editorial view of the product.
You can re-sort every comparison table using the controls above the table. You can filter by product features that matter to you. The order you see after re-sorting or filtering is not influenced by commercial arrangements.
Some content on this site is generated or supported by artificial intelligence tools, including our AI-powered assistant FinderBot. AI-generated content may contain errors. Please verify important information directly with the product issuer before making a financial decision. For more information about FinderBot, see the FinderBot Terms of Use and FinderBot Privacy Collection Notice.
Please read our website terms of use and privacy policy for more information about our services and our approach to privacy.
We update our data regularly, but information can change between updates. Confirm details with the provider you're interested in before making a decision.
Our goal is to create the best possible product, and your thoughts, ideas and suggestions play a major role in helping us identify opportunities to improve.


Hi, Thanks for your reply. I will indeed go check my credit rating, as I think it is A1, but maybe others do not agree. I did provide HSBC with my SMSF statement showing almost 2 million is assets with no liabilities other than day to day.
So, maybe I have no choice and I am stuck with the Citi credit card.
Citibank advise that BPAY, or Direct Debit payments each month do not attract FF points. I am a bit perplexed as to how you now earn FF points when using a credit card…They keep saying “eligible payments”, without explaining what an eligible payment method is in real English other than their legal terms and conditions.
Are eligible payments those made through the credit card to certain vendors only? Do I have to link the card to these vendors?
Hi Geoff, thanks for your inquiry!
Eligible purchases/ payments typically require a good/ service to be exchanged. You can earn FF points by using your credit card at the point of sale. Since direct debit payments are usually associated with paying bills and charges these transactions do not qualify for earning FF points.
Cheers,
Jonathan
I made an application to HSBC for a Platinum Qantas Credit Card, but they declined me.
They advise there is no, “one” reason for their decision, but i am sure they must there must be a reason. Can I make them tell me the reason(s) for declining me?
I have had a credit card all my life, never been in default, or late payment, and my credit history should be perfect, as never any issues. My present credit card has a limit of $25,000, and they keep offering me more….The new card would have provided greater points earning ability.
The only issue maybe, is that I retired a few years ago. However, my income from my super and private investments gives me an annual income of $60,000+, and despite a few world trips each year over the last three years with Qantas in First and Business, my super balance is still going up, proving we can live within the income range.
I would have thought, some one like me with a million plus in super, with no mortgages etc is a far better risk than some person an a salary paying a mortgage and other commitments, with their job always in question…..
Hi Geoff,
Thanks for your question and we’re sorry to hear about your declined credit card application. If your credit history is in good standing and you meet the eligibility requirements, perhaps you didn’t include all of the necessary information (such as superannuation statements and assets) to prove your income.
Declined credit card applications can have a negative impact on your credit score, so you might want to take some time comparing your options before applying for another one. In the mean time, you might like to read over the product disclosure statement to confirm which documents you need to provide to increase your chances of approval.
I hope this has helped and we’re sorry we can’t provide you with more specific information.
Cheers,
Sally
Is direct debit payment considered to be an eligible purchase with BankWest Qantas transaction account? Thanks
Hi Thoi, thanks for your inquiry!
Direct debit payments can qualify as eligible purchases providing a good/ service is being exchanged for funds. Transactions that do not qualify as eligible purchases include cheques, any transaction which incorporates a cash-out transaction at any merchant, BPAY payments, interest charges, government charges and business related expenses. Please refer to page 3 clause 5 of the PDF I have sent to your email for the full list of ineligible transactions.
Cheers,
Jonathan
My present credit card provider has advised me from May they will no longer accept payments via BPay as eligible payments to earn Qantas FF points. Is the BPay payment a common restriction?
I am thinking of using the Bank@Post as an alternative
Hi Geoff,
Thanks for your inquiry!
A number of banks/ issuer allow bill payments to earn Qantas FF points. So we can inform other users to this update could you please let us know who your credit card issuer is?
Thanks,
Jonathan
Hi, I was looking at the HSBC card which allows bill payments to be claimed as flyer points…I am in the process of an application…But, when I look at their site, it seems to be saying they do not allow BPAY ??
“Ineligible transactions for earning points includes balance transfers, cash advances, interest free transactions and HSBC’s special promotions, business expenses, fees or charges (including government), any value charged to your card in association with a points plus pay redemption, any expenditure incurred as part of a ‘points plus pay’ transaction, a transaction which HSBC decides is fraudulent or involves the abuse of a card, a disputed debit transaction and finally BPAY transactions.”
Hi Geoff, thanks for your response.
That is correct, unfortunately HSBC does not allow earning points with BPAY transactions. Since earning points with BPAY payments is less common transaction the best way to approach this would be to narrow down your list of credit card options and determine whether each bank accepts BPAY payments or not. Were there any other credit cards you were considering to apply for?
Cheers,
Jonathan
Hi, Any card will do that I can use my monthly payment to attract points.
My present card will have annual fees of $160. Unless I can earn sufficient points, maybe the award card is not worth it?
Maybe I go back to the old way of paying the card – A bank transfer! I do not see any reference to this as being not an eligible payment.
Hi Geoff,
Thanks for your inquiry!
That is correct. It is beneficial to take your annual fee into account and assess whether you earn sufficient points to justify the value of having a particular rewards card. You can compare a range of Qantas credit cards and check your options. You can compare these cards based on annual fees, interest rates, and rewards points earned per $1 spent.
Before applying, please ensure that you meet all the eligibility criteria and read through the details of the needed requirements as well as the relevant Product Disclosure Statements/Terms and Conditions when comparing your options before making a decision on whether it is right for you.
I hope this helps.
Cheers,
Jonathan
Hi Jonathon,
My current provider is Cardservices – Mycard (part of the citigroup)
They have advised me about a few changes:
BPAY transaction no longer able to earn reward points.
The international transaction fee will be 3.4% of the AUD dollar conversion of any transaction made in a foreign currency.
Any transaction made with an overseas merchant in Australian Dollars, of which a 1% service and assessment fee is payable by Mycard to MasterCard
A $49.00 annual fee for the rewards program(used to be free)
Change from 1 point for each Australian Dollar to 1 point for each Australian Dollar for the first $1500 spent each statement period and 0.5 Points thereafter.
Platinum reward points earn rate reduced from 1.25 to 1 point
So, in my case, I pay my card each month via BPAY, which I have done for many years). If I can no longer earn points this way, I need to find another way of making payment(I have asked them this and they are considering my request)
OR look for a new card provider. But, now retired, obtaining a new card may not be as easy when working.
Hi Geoff,
Thanks for your reply!
We can confirm that Citi has cancelled the feature of earning Qantas Points with BPAY payments. Since this feature varies between banks please refer to the section ‘Which credit card issuers let you earn Qantas Points paying bills’ for an evaluation of which banks still allow this points transaction.
Please ensure that you meet all the eligibility criteria and read through the details of the needed requirements as well as the relevant Product Disclosure Statements/Terms and Conditions when comparing your options before making a decision on whether it is right for you.
Cheers,
Jonathan
What are the affiliated shops were you earn double points
Hi Ash,
Thank you for your inquiry.
We can’t provide a full list of the shops where you can earn double points. These offers may also vary on the credit cards or issuers that lets you earn Qantas Points. You may want to go directly to Qantas Store website or contact a customer service representative directly, they may able to assist you further with your concern.
Kindly visit our guide to Qantas Frequent Flyer program partners.
I suggest that you revisit the relevant product disclosure statement and terms and conditions to ensure that you got everything covered on your transactions.
I hope this helps.
Cheers,
Debbie