Home loan cashback offers
Grab yourself a home loan cashback offer and get up to $4,000 in your pocket. Here are all the top cashback deals.
A home loan cashback is a lump-sum payment a lender gives to a borrower as an incentive to take out a mortgage with them. Cashbacks are typically worth between $1,000 and $4,000.
Lenders use these offers to attract new customers, particularly those looking to refinance an existing home loan from a competitor. However, some cashback deals are also available for first home buyers and those purchasing a new property.
Once your loan is approved and settled, the lender deposits the cashback amount directly into your transaction or offset account. The funds are not considered taxable income and you are free to use the money however you like.
Cashbacks can have some conditions attached that borrowers need to meet, like:
The time it takes to receive your payment varies between lenders, but you can typically expect the money in your account within 30 to 120 days after settlement.
Unloan Finder Reward
You could get a $1,000 visa card when you apply to refinance your home loan to Unloan and settle by 30 November 2026.
| Lender | Cashback amount | Borrowing criteria |
|---|---|---|
| ME Bank | Up to $3,000 | Refinancers |
| BankVic | $3,000 | Police, emergency services and health workers only |
| IMB | Up to $4,000 | Purchasers and refinancers |
| Greater Bank | Up to $3,000 | First home buyers, refinancers and online applicants |
| Newcastle Permanent | Up to $3,000 | Purchasers and refinancers |
| Great Southern Bank | Up to $3,000 | Refinancers and investment lending |
| ANZ | $3,000 | First home buyers (excludes ANZ Plus home loans) |
| Bank of Queensland | $2,000 | Refinancers |
| Credit Union SA | $2,000 | Refinancers and purchasers (South Australian education employees only) |
| BankWAW | $2,000 gift card | Refinancers |
A cashback offer can be a great perk, but it shouldn't be the main reason you choose a loan. The long-term cost of the mortgage is far more important than a one-off bonus. A loan with a slightly higher interest rate can cost you tens of thousands of dollars more over time, quickly wiping out the benefit of a few thousand dollars in cashback.
Before committing, ask yourself: if the cashback offer was removed, would this still be the right loan for me?
Always compare the following features to ensure the loan is a good deal on its own:
"Cashbacks were initially offered to cover the switching costs associated with refinancing. Whilst these are a great offer, it shouldn't be the sole reason to refinance your loan or pick a product provider.
When we assess the suitability of a lender, we take into account your circumstances and match the right lending policy before anything else – then it is rates and fees and finally we look at cashback opportunities. We have seen many clients get into the wrong products because they were lured by a $2,000 sugar hit. These products can end up being tens of thousands of dollars more expensive in the long run."
Here's an example of how a cashback offer can be misleading:
Imagine you're refinancing a $500,000 loan. You have two options:
With Loan A, you get an immediate $3,000 boost. However, after just five years, you will have paid $1,975 in annual fees and approximately $5,500 more in interest compared to Loan B. The initial cashback has been completely erased by higher costs.
A lender might waive the application fee, which can be a saving of $600 or more.
Some loans offer a low introductory or 'honeymoon' rate for the first year or two. Be sure to check what the rate reverts to after the discount period ends.
Lenders may bundle a home loan with other products like a credit card and transaction account for a single annual fee. This can offer value if you use all the products included.
Some home loans let you earn frequent flyer points on your loan balance, though these loans often come with higher rates or fees.

"Cashback offers are still available and can provide a financial boost during the settlement process. However, it's important to weigh the overall loan cost and terms, as cashback deals sometimes come with higher interest rates or fees. Always compare the long-term savings against the upfront reward."
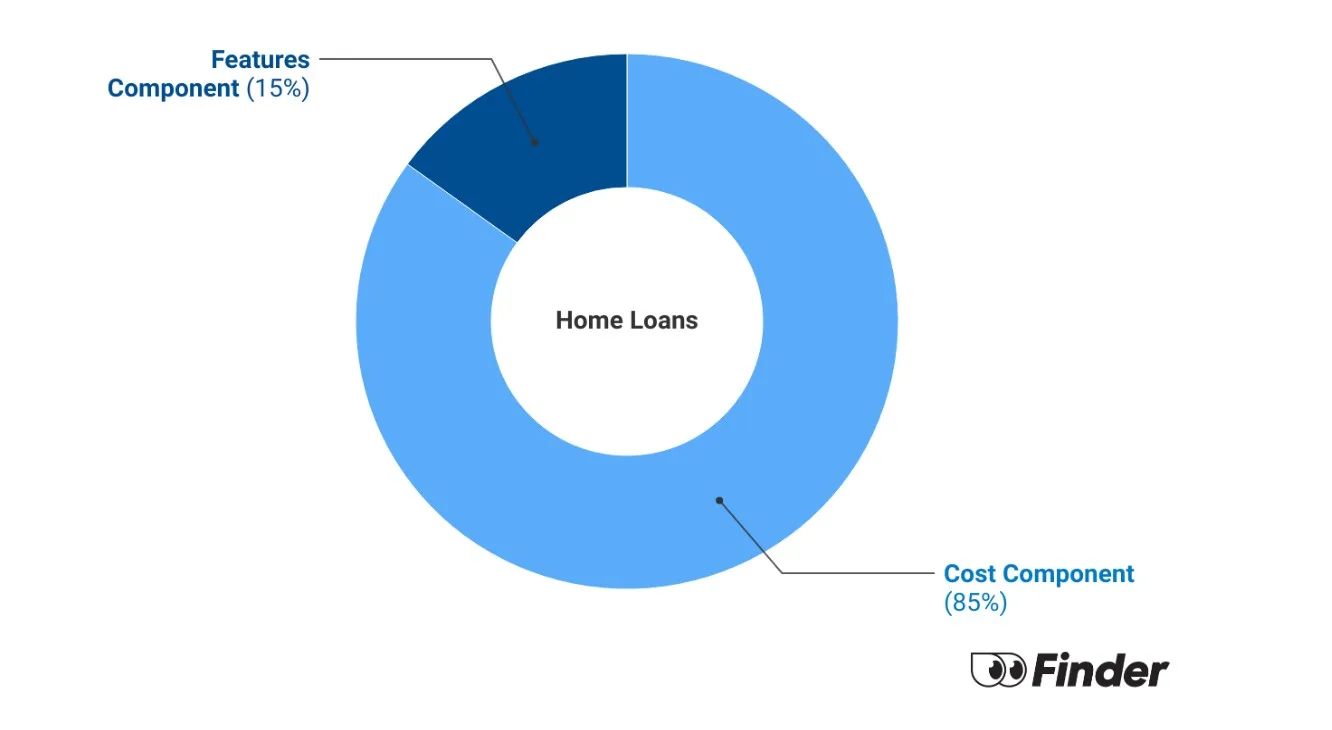
The Finder Score crunches 7,000 home loans across 120+ lenders. It takes into account the product's interest rate, fees and features, as well as the type of loan eg investor, variable, fixed rate - this gives you a simple score out of 10.
To provide a Score, we compare like-for-like loans. So if you're comparing the best home loans for cashback, you can see how each home loan stacks up against other home loans with the same borrower type, rate type and repayment type. We also take into consideration the amount of cashback offered when calculating the Score so you can tell if it's really worth it.
Do you have to tell your lender if you rent out a room and turn your mortgage into an investment loan?
Read our detailed review of reverse mortgage lender Household Capital.
All Australian home loan types explained, from the common to the specific.
A guide to shared equity schemes, how they work and where to find them.
Compare home loans from Firefighters Mutual Bank. Read reviews and apply.
A closer look at the home loans provided by Central West Credit Union.
If your lender was to collapse, not much would change to your home loan.
Your guide to home loan offers from First Option Bank.
Illawarra Home Loans is a Wollongong mortgage broker that has been arranging home loans since 1989.
Compare home loan offers from St.George. Learn more about this lender and its loans.