Compare third party car insurance
Third party car insurance can cover you for damage you incur to other people's cars and property. Compare now.
Third party property car insurance covers you for damage to other people's property – for example someone else's car, home or shop. It covers only this and nothing else, up to a certain limit (commonly $20 million). This type of policy adds an additional layer of protection over the bare minimum compulsory third party insurance, and prevents you from having to be out of pocket for potentially enormous bills if you hit something expensive.
This is a step up from third party property insurance. In addition to covering you for costs if you damage someone else's property, it can pay to repair or replace your car if it's damaged by fire or stolen. However, it still doesn't cover you for damage done to your own car – only comprehensive car insurance covers you for this.
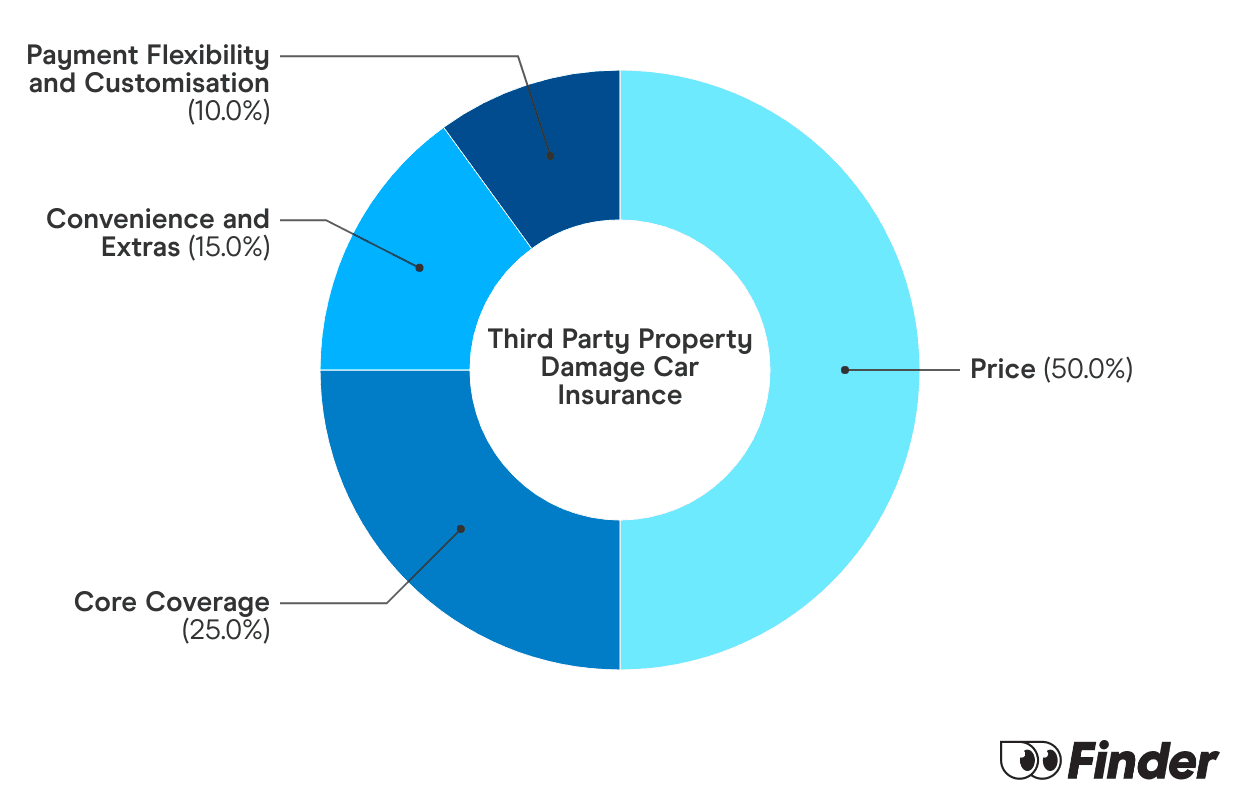
We analyse over 30 car insurance products across insurance providers, and rate each one for price and features. We collect up to 36 quotes per product, for male and female drivers in New South Wales, Victoria, Queensland, South Australia, Tasmania and Western Australia. Quotes are collected for 20 year olds, 30 year olds and 60 year olds, assuming an excess of $850 for a 2020 Toyota Corolla 4 door sedan model, with an average 15,000 kms driven each year. While we are not allowed to display actual quotes, our Finder Score aims to serve as an indicative guide to how cost and feature competitive a product might be for you.
Our feature score assesses each product for more than 15 features across loss and damage coverage, repairs and assistance coverage, personal items coverage and policy coverage. Features we assess include but are not limited to legal liability, essential repairs, new car replacement, car hire events, roadside assistance, agreed or market value, windscreen damage and natural disaster coverage.
Third party property damage cover is already one of the cheaper ways to insure your car, but prices still vary between insurers. In Finder's latest quotes, the cheapest third party property damage policies started from around $427 a year.
Based on our sample quotes, the most affordable policies came from Budget Direct and Bingle, both around the $427 to $431 mark for our driver profile. Keep in mind these are based on a set profile, so the cheapest option for you will depend on your car, your age and where you live.
The cheapest policy isn't always the best value, though. Some slightly dearer policies include extras like cover for damage caused by an uninsured driver, which can be worth the small difference. Compare a few options on both price and what's included before you decide.
1. Compare quotes
Most third party car insurance policies are very similar so price is an important factor. If you think you're paying too much, compare car insurance policies to find a better deal.
2. Choose a higher excess
Your insurer will offer you a lower premium in return.
3. Restrict drivers
You can get a cheaper car insurance policy by restricting your policy to drivers over a certain age.
4. Uninsured motorist damage
Some third party policies cover damage to your own car caused by an uninsured driver. The cap is usually $5,000 but will vary between insurers.
5. Discounts
Sign-up discounts can be a good way to pay less. Just make sure the policy is still the right fit for you.
Could be good if you:
Might not be good if you:
"I had a third party property damage policy on my old car. It was a pretty run-down vehicle, plus I was always working from home and barely used it or left it unattended, so a comprehensive policy just wouldn't have been worth the money. A basic third party policy to protect me from the costs associated with damage to other people's property was all I needed at the time and cutting it right back was a good way to save money."
Find out if RAC Roadside Assistance is the right option for you.
Find out what RAA Roadside Assistance covers you for and how much it costs.
Find out what 24/7 Roadside Assistance covers you for and how much policies cost.
RACV’s roadside assistance offers premium cover with strong benefits - but the price point may put some drivers off.
RACQ offers strong benefits and service, but drivers can expect to pay higher premiums.
Find out if Allianz Roadside Assistance has a policy that's right for you.
Coles roadside assistance – affordable cover with your car insurance. Is it right for you?
AAMI roadside assistance: Find out what's covered, how much it costs & more.
Your guide to Youi Roadside Assistance.
A quick summary of NRMA Roadside Assistance.

I am currently looking for an insurance policy for my son who is about to go on his P’s. I think Third Part Fire and Theft will be fine as we are looking at a car under 10k. However I’m not sure of rates as you need to know models prior to getting quotes. Is there a way of getting quotes without knowing the car you are getting yet?
Hi Suzie, Quotes will always be specific to the model, so you won’t be able to get a quote without one. However, you can get an idea by picking models from your shortlist of potential buys and seeing what the rates are. Realistically, for a P-plate driver you’ll be paying more as the risk is higher for younger drivers, no matter what car you choose.
I have a car with hail damage only.
Can I still get third-party insurance?
Hi Tina,
Provided the car is still safe to drive, it should be possible to get third party car insurance. Good luck!
I am 76, male, car worth less than $10,000, drive less than 5,000 km annually. What’s best, cheapest insurance for me, for damage to other cars only?
Hi Bjorn,
What’s best or cheapest will depend on your personal circumstances and driver profile so I couldn’t recommend specific providers to you. Instead, I can share a few tips to help you find a cheaper policy:
– Get quotes from at least 3-5 providers so you can see the difference in pricing on offer
– Look for sign up discounts
– Consider adjusting your excess; a higher excess means a lower premium. Just be sure you can still afford the excess in the event you’re required to pay it
– Restrict drivers under 25 if you’re sure no one under that age will drive the car. This can help bring the cost down as insurers typically view younger drivers as more risky and can up the premium if they’re not excluded
Remember, every policy varies so to ensure it covers what you need, read the product disclosure statement on the provider’s website.
I hope this helps!
I have a 2004 Holden Berlina which has not been registerred nor driven for 5 years , it is now for sale, can I get CTP insurance for less than 12 months , even 6 month to match the proposed registration term.
James
Hi James, CTP insurance can typically be bought for either 6 or 12 months but it’s best to check with your insurer as payment terms may vary. This page may be helpful for any other questions: https://www.finder.com.au/car-insurance/ctp-insurance
Hello, I have an at fault claim from nearly 4 years ago, a driving under the influence of drugs charge for which I lost my licence for 6 months approx 3 years ago plus I have a criminal record for drug charges… Can you help me weed through the options, if any, available to me to take out a policy?
Hi Ryan,
Check out this article for more info that might be useful for your situation:
https://www.finder.com.au/car-insurance/car-insurance-criminal-record