How much is car insurance?
The average comprehensive car insurance premium cost is $134 a month – but we’ve got third party policies starting from $32 a month.
Note: For information on how we got these quotes, see our car insurance methodology.
We currently don't have that product, but here are others to consider:
How we picked theseWe currently don't have that product, but here are others to consider:
How we picked these| Average cost in Australia | New South Wales | Queensland | South Australia | Tasmania | Victoria | Western Australia | |
|---|---|---|---|---|---|---|---|
| Budget Direct | $992 | $1,148 | $941 | $978 | $829 | $1,180 | $880 |
| Virgin | $1,057 | $1,214 | $1,013 | $1,046 | $880 | $1,254 | $934 |
| Suncorp | $1,559 | $2,003 | $2,107 | $1,240 | $1,100 | $1,588 | $1,317 |
| Everday | $1,552 | $1,861 | $1,356 | $1,402 | $1,218 | $2,070 | $1,403 |
| Hume Bank | $959 | $900 | $1,036 | $922 | $783 | $1,280 | $831 |
| ROLLiN' | $886 | $1,151 | $843 | $690 | $709 | $1,248 | $674 |
| Bingle | $862 | $935 | $872 | $724 | $726 | $1,156 | $761 |
| Huddle | $1,407 | $1,702 | $1,261 | $1,286 | $1,112 | $1,848 | $1,233 |
| Real Insurance | $1,464 | $1,752 | $1,277 | $1,326 | $1,147 | $1,959 | $1,321 |
| AAMI | $1,218 | $1,884 | $1,106 | $1,015 | $985 | $1,318 | $1,002 |
| State | Cost |
|---|---|
| New south wales | $1,698 |
| Victoria | $1,721 |
| Queensland | $1,274 |
| South australia | $1,233 |
| Western australia | $1,242 |
| Tasmania | $1,128 |
When you're younger you'll pay noticeably more for car insurance as you're deemed to be a higher risk driver. But our research says that these high prices thankfully don't last! As you get older, your cost should go down as long as you stay a safe driver.
| Age | Average cost |
|---|---|
| 20 | $2,387 |
| 30 | $1,293 |
| 40 | $1,116 |
| 50 | $1,010 |
| 60 | $899 |
| Brand | Cost |
|---|---|
| Virgin | $378.90 |
| Budget Direct | $379.57 |
| Bingle | $425.84 |
| Qantas | $434.42 |
| Australia Post | $449.69 |
| Allianz | $481.65 |
| Kogan | $515.04 |
| AAMI | $516.02 |
| NRMA | $524.56 |
| GIO | $526.89 |
The cost of car insurance is impacted by the level of policy you choose, who is driving the car, what type of car you have, where you live, as well as other factors.
Aside from compulsory third party (CTP) insurance, which is mandatory for all Australian drivers, there are 3 levels of car insurance cover to choose from: comprehensive, third party fire and theft, and third party property damage. The policy you choose will influence the cost of cover due to:
A lot of insurers will offer the option to pay monthly, but you need to check if you're being charged an additional fee for this. We researched over 50 car insurance providers and found that about 30 of them will add a surcharge for paying monthly. In some cases we found a surcharge of around 15%, which can be hundreds of dollars over the course of a year. ASIC's 2026 review found a gap of 10% to 20% between paying by instalments and paying annually with many insurers. Below is a real life example of this surcharge in action.
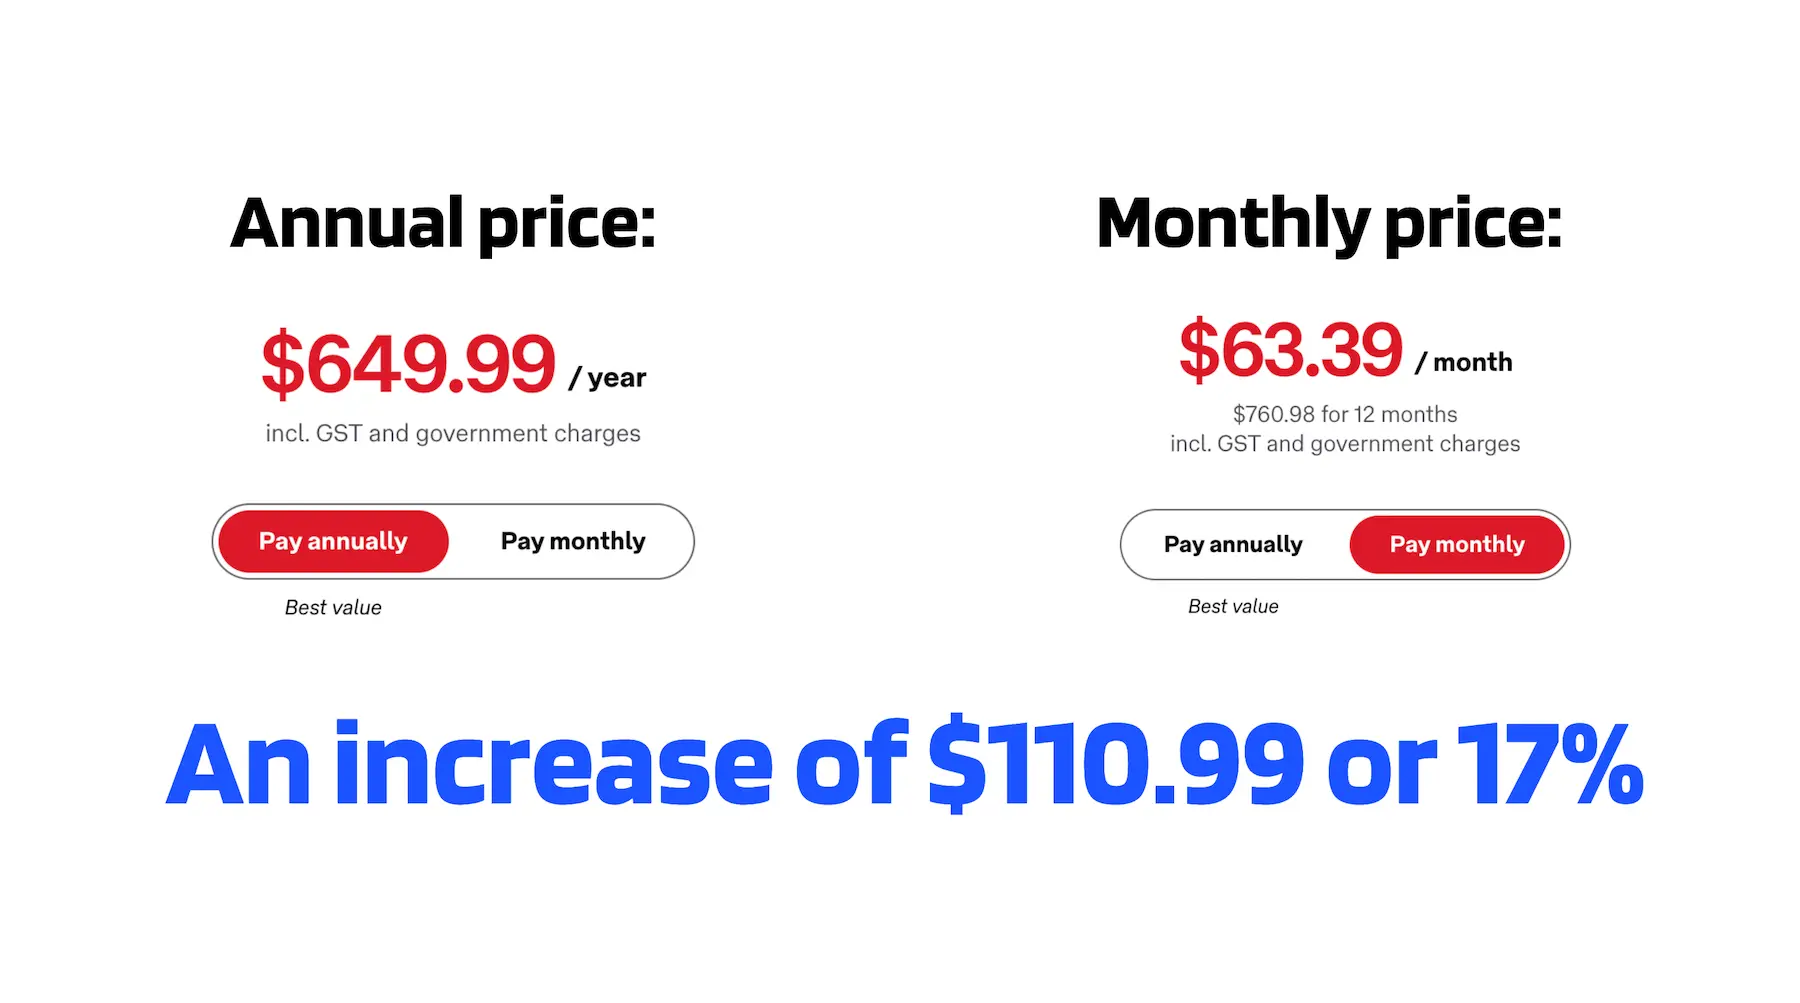
Based on comprehensive insurance, female driver aged 40, parked in QLD, car insured at market value.
So, if you'd like to pay monthly, just be sure to check if this is a financially sound choice for the longterm.
To help determine your risk, all insurers will ask you about the following:
Some vehicles are more expensive to insure than others for several reasons, and insurers will consider the following factors when calculating your premium:
And at the end of all this, if you’re deemed a high risk driver, your premium will be more expensive.
Explore comprehensive cover designed for Tesla drivers. We cover the pros, cons and other details you need to know about InsureMyTesla.
Teslas are more expensive to insure than traditional cars but there's ways to cut costs.
Learn the factors that may cause you to be considered a high-risk driver and whether you might be eligible for cover.
The media always talks about how cheap electric cars are to run, but will you save money when insuring one?
A quick summary of NRMA Roadside Assistance.
Find out what car insurance options are available for rideshare drivers, including Ubers.
Discover the steps to get affordable car insurance if you are under 25.
This article runs through the ins and outs of choosing a good third party property damage car insurance policy.
Explore our analysis and see how you can find the best car insurance for your needs.
Compare cover from a range of car insurance providers and find out some of the things you will be covered for under a comprehensive policy.

How much higher or lower than the purchase price should you insure for a new car if agree value option is chosen?
Hi Richard,
The goal is to be insured enough that you’re not terribly out of pocket if the car were to be written off. If you bought the car outright, it’s smart to insure it for at least what you paid. If you’ve bought the car with finance of some sort (loan, lease etc) then it’s smart to consider what you owe with interest and any other fees accounted for, then ensure your agreed value reflects at least that amount.
Typically, you won’t want to to try to insure it for loads more than you bought it for because that’ll only drive up the cost of your premium. Insurers will also have a cap on how much they’re willing to insure it for so you don’t want to price yourself out of coverage either. The higher your agreed value, the more your premium will cost. So you’ll want to strike a good balance between enough coverage that you’d be okay if the car was written off, while maintaining an affordable premium.
I hope this helps!
can i get a range of figures like on this page for a van, used only for private puproses?
Hi Trav,
We don’t have a page full of statistics about van insurance, but we do have a guide with some info you mind find useful. Hope this helps!