Looking for other options? Check out these similar products.
How we picked theseKey takeaways
- Low rate cards under 15% can save you significantly more than Finder's database average purchase rate of 17.15%.
- Compare purchase rates below 10% and annual fees, but watch for high revert rates on 0% offers.
- Many low rate cards offer 0% balance transfers or cashbacks on spending to boost your savings.
Best low rate credit cards
- Best Big 4 Bank low rate credit card: Westpac Lite Card
- Best low rate cashback credit card: St.George Vertigo Card - Cashback Offer
- Best low rate no annual fee credit card: American Express Low Rate Credit Card
Top low rate credit card offers for October
These are the market's top low interest rate credit cards based on their Finder Scores:
- The Defence Bank Foundation Credit Card has a Finder Score of 9.9.
- The St.George BusinessVantage Visa has a Finder Score of 9.9.
- The Coastline Visa Credit Card has a Finder Score of 9.76.
- The Community First Low Rate Pink credit card has a Finder Score of 9.77.
- The Community First Low Rate Blue credit card has a Finder Score of 9.77.
- The National Seniors Credit Card has a Finder Score of 9.77.
Finder's low rate credit score analyses hundreds of credit cards and ranks each card based on a combination of low rates, annual fees and the number of interest-free days.
Updated in October 2026 by Finder's senior money editor, Richard Whitten.
-
Number crunching the Finder Score
- 9+ Excellent - These cards offer the lowest ongoing purchase rates, high number of interest free days, and competitive introductory and ongoing annual fees.
- 7+ Great - Reasonable ongoing purchase rates and fees, with the potential for additional perks.
- 5+ Satisfactory - Low interest rates, but watch out for above average ongoing fees.
- Less than 5 – Basic - These are generally cards with low interest rates, however could charge high ongoing fees.
Tell me more about the low rate credit card score
Finding the perfect low rate card is about more than just the rate (although that is the most important thing).
That's why we created the Finder Score. It's an easy, data-driven way to judge credit cards at a glance.
- Every month, our insights team analyses over 220 credit cards.
- We assess ten features for each card, rating each feature.
- Then these ratings are combined via a weighted methodology to create a simple score out of 10.
We give different scores for different categories. So a card might get a 9 in the low rate category but an 8 in the balance transfer category.
The Finder Score is designed by our insights and editorial team. We score credit cards objectively. Commercial partnerships don't affect the scores at all.
Remember that Finder Score is just one factor to consider. Look at other aspects like fees, features, benefits and risks to make sure a product is suitable for you. Double-check details that matter to you before applying or buying.
Low rate credit cards - score weightings
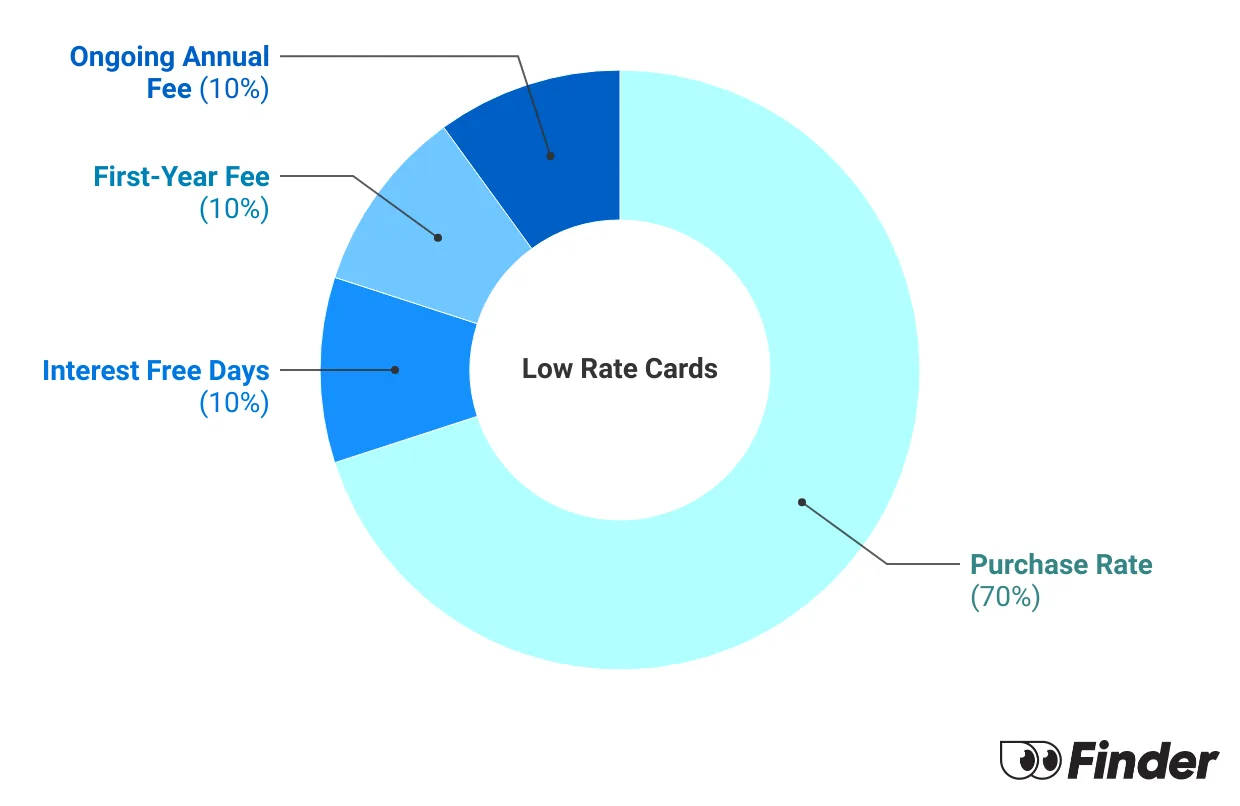
Feature Definition Assessment Weight Purchase Rate Interest rate on new purchases Lower rates score higher 70% Interest Free Days Number of days with no interest charged on new purchases Higher number of days score higher 10% First-Year Fee Annual fee charged in the first year of ownership Lower fees score higher. $0 fee receives the maximum points 10% Ongoing Annual Fee Annual fee charged from the second year onwards Lower fees score higher. $0 fee receives the maximum points 10%
What is a low interest rate on a credit card?
In Australia anything under 15% is a fairly low purchase rate for a credit card. Some cards have interest rates as low as 8.99% or as high as 27.99%.
Some cards even offer 0% interest rates, but those are usually introductory offers that revert to a much higher rate after 6 months.
A low rate credit card gives you a way to spend money and then pay it off over time without getting hit with high interest rate charges.
2 ways to avoid or minimise interest charges on a credit card
- Pay the card off completely each month and pay no interest at all. Any credit card becomes a 0% interest rate card if you pay your spending off in full before interest charges kick in.
- Get a low rate credit card and pay it off as quickly as you can. If you can't afford to pay off your card spending fully, a low or 0% rate is the next best option. This lets you pay the card spending off over time while minimising the interest charges.
Why do people use low rate credit cards?
You can't afford to pay off your card spending in full
Sometimes in life it just isn't possible to pay off your card spending each month before you start getting charged interest. Life is expensive.
If you frequently find you spend more than you earn, you may be in deeper financial trouble long term. But it can't be helped sometimes, and a low rate credit card helps you cut down those interest costs.
You need to repay card debt via a balance transfer
The second scenario where people really need a low interest rate credit card is when their existing card spending has gotten them into trouble. That's a where a balance transfer can help.
A good balance transfer credit card offer gives you 0% or very low interest charges for 24 months (or more) on your existing credit card debt. You move the unpaid balance from the old card onto the new one, cancel the old one and then start paying it back.
What about 0% interest rate cards?
There are also cards that offer a 0% purchase interest rate. Some cards give you 0% for 6 months, others charge a monthly fee instead interest.
These cards are useful if you have large purchases, like a holiday, wedding or renovation coming up. You can spend now and pay it off over time without interest charges.
You just need to watch out for:
- The revert rate. Some credit cards give you 0% for 6 months. But on month 7 the rate jumps up to 20%. If you haven't paid off your spending, you're suddenly looking at big interest charges.
- The fees. Some of these cards never charge interest but do charge an ongoing fee. This fee could be small but still end up costing more than interest charges over a few months.
Pros and cons of low rate credit cards
Pros
- You pay less interest. Low rate credit cards can be a cheaper option as you pay less interest on purchases, which will help you save money and avoid falling into unmanageable debt.
- You save on fees. Many low interest rate credit cards also have lower annual fees, which helps you save even more money.
- You can get promotional offers. Low interest rate credit cards sometimes offer 0% promotions on purchases and/or balance transfers, allowing you to avoid interest altogether for an introductory period.
Cons
- You get fewer rewards. Low rate credit cards tend to have fewer or no rewards or perks, compared to higher rate, premium rewards and frequent flyer cards.
- You get fewer extra features. Lower rates generally mean fewer extra features, unlike platinum cards which often come with complimentary insurance options, cashbacks, concierge services and more.
- Watch out for revert rates. If your card offers 0% interest on purchases for a promotional period, it will revert to a higher purchase rate that could be up to 29.99% p.a.
How much can you save with a lower rate?
Most Australians pay their credit cards in full each month. This means they don't get charged any interest on their spending.
But Australians with an unpaid credit card balance have on average $1,655. Let's look at how much interest you end up paying on this balance with different interest rates (assuming you take 12 months to pay off the card:
| Balance | Interest rate | Monthly payments (over 12 months) | Total interest charged |
|---|---|---|---|
| $1,655 | 9.0% | $144.73 | $81.79 |
| $1,655 | 12.0% | $147.04 | $109.54 |
| $1,655 | 15.0% | $149.38 | $137.53 |
| $1,655 | 17.0% | $150.94 | $156.33 |
| $1,655 | 20.0% | $153.31 | $184.72 |
The difference between a 20% interest rate and a 9% rate is over $100 in interest over 12 months.
How long will it take Aussies to pay off their credit card debt?
| Length of time | Percentage |
|---|---|
| 3-4 years | 2% |
| 5 or more years | 3% |
| 1-2 years | 6% |
| 7-12 months | 9% |
| 1-6 months | 16% |
How to compare low interest rate credit cards
With so many competitive low interest rate credit cards on the market, here are some of the features that can help you narrow down your options:
- Compare interest rates. The lower the interest rate the better. Below 15% is good, below 10% is very good. If a card offers a 0% promotional rate, check how long it lasts and remember that it will be much higher after this period ends. Some 0% cards jump to 20% after 6 months!
- Look at the card's annual fee. Low rate cards have annual fees of around $59 on the lower end but can go as high as $200. The lower the better, but cards with higher fees may offer useful features and perks. There are also some cards that offer $0 annual fee for the first year or for life.
- Factor in other fees. If you use your card for foreign currency or overseas purchases (including online), you will usually be charged a foreign transaction fee of around 2-3.5%. But certain credit cards are more tailored to international use and offer 0% foreign transactions fees.
- Compare perks and features. Some low rate cards also come with cashback offers, although you'll usually need to meet a certain spend requirement to get the money back. Some low rate cards offer you complimentary travel insurance and purchase cover.
What perks and benefits can you get with these credit cards?
Let's be clear: low rate credit cards are not the best cards for points, perks and other benefits. Those cards have higher rates and higher annual fees.
But the best low rate cards often come with decent benefits at the price point, such as:
- Cashbacks. Quite a few of the top scoring low rate cards in Finder's database offer some form of cashback on your spending. Cashbacks usually give you, say, 10% back on eligible spending, capped at a certain amount. This can save you a few hundred dollars.
- 0% balance transfers. Low rate cards often have some of the best 0% balance transfer deals. Just keep in mind that a balance transfer customer needs to focus on paying off existing debt rather than adding to it with more spending. So the low purchase rate doesn't matter as much because you should be paying the balance transfer off.
- 0% foreign transaction fees. A few low rate cards offer 0% foreign transaction/international transaction fees, which saves you money when travelling or shopping overseas.
- Complimentary insurance cover. While low rate cards are far less likely to offer complimentary travel insurance, some cards do offer this, or other types of cover like purchase protection insurance.
The bottom line
If you often carry over a balance from one month to the next, a low interest credit card could help you save on interest charges. While there is no "best" low rate care, the mix of credit cards available in Australia means you can compare credit card offers and features to help find a card that you want.
2026 Finder Awards for Low Rate Credit Cards
Each year the Finder Credit Card Awards recognises Australia's top credit cards, with expert analysis of rates, fees and offers based on 12 months' worth of data. Here are the top performing low rate credit cards.
Best Low Rate Credit Card: G&C Mutual Bank Low Rate Visa Credit Card
G&C Mutual Bank's Low Rate Visa Credit Card is the winner of this year's low rate credit card award. It has, you guessed it, a very low interest rate. Plus a low annual fee.
Highly commended
Community First Low Rate Credit Card
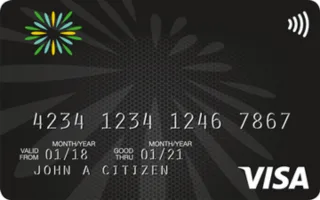
Community First's Low Rate Credit Card finished highly commended in the Low Rate Credit Card category this year with a very low rate.
Community First Low Rate Credit Card
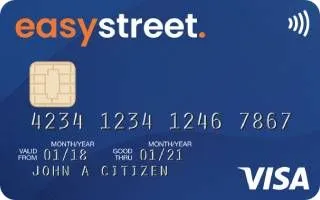
Community First's Low Rate Credit Card finished highly commended in the Low Rate Credit Card category this year with a very low rate.
Easy Street Easy Low Rate Visa credit card
The Easy Street Easy Low Rate Visa credit card secured a highly commended distinction thanks to its competitive purchase rate.
Easy Street Easy Low Rate Visa credit card
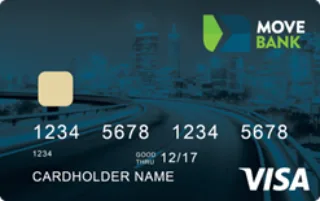
The Easy Street Easy Low Rate Visa credit card secured a highly commended distinction thanks to its competitive purchase rate.
MOVE Bank Low Rate Credit Card
MOVE Bank's Low Rate Credit Card scored well this year with one of the market's lowest credit card purchase rates.
MOVE Bank Low Rate Credit Card
MOVE Bank's Low Rate Credit Card scored well this year with one of the market's lowest credit card purchase rates.
Frequently asked questions
-
The cheapest card will depend on how you use it. If you pay off your balance every month, a $0 annual fee credit card would likely be the cheapest option.
If you regularly carry a balance from month to month, the cheapest credit card will have a low interest rate and a modest annual fee (less than $100). There aren't many cards on the market that offer both a $0 annual fee and a low rate, but using the table above you can find what you consider to be a cheap credit card.
-
There is no one "best" low interest rate credit card in Australia. With so many cards on the market, a card's individual features have an impact on how well it suits your circumstances. So the card that's right for you may not be right for someone else. Comparing low interest rate credit cards based on the features you're looking for will help you find a card for your individual needs.
-
A low rate credit card can be very useful if you carry a balance (can't repay all your card spending in one month) as it cuts down your interest charges. It's also useful if you need to make a large one-off purchase and pay it off over time.
These cards are less useful if you're a big spender who can afford to pay your card spending off in full. You may get more value out of a reward or frequent flyer credit card.
And if you only use the card occasionally and always pay it off, you might save money with a no annual fee credit card.
-
Low rate and low fee credit cards can both save you money but in different ways. A low interest rate credit card reduces your interest charges if you can't repay your card balance fully each statement period.
A low fee credit card saves you money on fees. They are more suited to customers who pay off the card in full and don't need to worry about interest charges.
-
Credit card interest rates are usually advertised by the annual rate that applies to the account, shown as "per annum" or p.a. However, interest on your account balance is typically calculated daily and then charged monthly on the statement due date. This means that for every day that you don't make a payment, the interest charges will build up (or compound).
If you want to learn more about credit card interest in detail, you can check out Finder's comprehensive guide to interest rates.
-
This depends on the credit card and any applicable balance transfer offers. If the card allows balance transfers, it may come with a 0% interest rate for a promotional period before reverting to a standard rate.
Some low interest rate cards apply the standard purchase rate to balance transfers after the introductory period while others apply the cash advance rate, which can be as high as 29.99% p.a. The average standard credit card interest rate is currently 20.99% according to Finder analysis of Reserve Bank of Australia data.
-
There isn't a single "cheapest" credit card option because everyone uses credit cards differently. There are other costs to consider beyond the purchase rate, such as annual fees and interest rates for cash advances or balance transfers. On the flip side, some people might find cards with high rates and fees "cheap" because of all the complimentary extras.
When you're looking to find a credit card, consider all of the potential costs based on how you plan to use the account. That way, you'll be able to find one with rates and fees that are affordable for you.
-
Most frequent flyer and rewards credit cards have higher interest rates and fees than low rate cards. But there is a small selection of low rate credit cards that offer points on eligible spending, including the Coles Low Rate Mastercard and Queensland Country Bank Visa My Rewards Credit Card. These cards typically earn fewer points per $1 spent, so it's important to consider whether rewards or a low rate will offer you more value before choosing a card.
-
If your credit card offers 55 interest-free days and you make a purchase on the first day of your statement period, you'll have 55 days to pay it back before you're charged interest. If you make that purchase on day 15 of your statement period, you'll have 40 interest-free days, and so on.
This only applies if you pay the amount required by the provider by the due date listed on your statement. See Finder's guide to interest-free days for full details.
-
A $1,000 limit can suit those new to credit or looking to build their credit score with minimal risk. It offers flexibility while limiting the risk of debt.
-
Yes, many entry-level and low-fee credit cards offer credit limits starting from $2,000. Cards like the ANZ First or CommBank Low Fee cards are examples.
Sources
Richard Whitten is Finder’s Senior Money Editor, with over eight years of experience in home loans, property, credit cards and personal finance. His insights appear in top media outlets like Yahoo Finance, Money Magazine, and the Herald Sun, and he frequently offers expert commentary on television and radio, helping Australians navigate mortgages and property ownership. Richard started his career in education and textbook publishing in South Korea. He holds multiple industry certifications, including a Certificate IV in Mortgage Broking (RG 206) and Tier 1 and Tier 2 certifications (RG 146), as well as a Bachelor of Education from the University of Sydney and a Graduate Certificate in Communications from Deakin University. See full bio
- Home loans
- Credit cards
- Personal finance
- Money-saving tips
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
Read more on Low Rate Credit Cards
-
Credit card instalment plans
You can manage repayments and secure a low or 0% interest offer with a credit card that provides instalment plans.
-
Cash advances interest rates and fees
A credit card cash advance is when you withdraw money or get a “cash equivalent” like gift cards – and it typically attracts high rates and fees.
-
How the interest-free period on a credit card saves you money
Most credit cards offer interest-free days on purchases – here's how they actually work.

I want a low interest credit card for purchase of sewing machine
I won’t be able to pay back in full for the first few months
however I endeavour to pay off as quick as possible after 6 months.
What are some options please
Hi Jlb,
Thank you for your question.
If you think you will have difficulty paying off your credit card each month, a low-interest rate credit card may be of value to you.
You can select the “Go to Site” button of your preferred credit card to proceed with your application. You can also contact the provider if you have specific questions. A gentle reminder, please ensure to read through the relevant product disclosure statement and terms and conditions to ensure that you got everything covered before you apply.
I hope this has answered your question.
Thanks,
Sally
Hi,
I am wanting to purchase a caravan for $10,000. I’ve looked into personal loans but am also considering credit card as interest can be lower. What would you suggest on a type of credit card?
Hi Kristy,
Thanks for your inquiry.
You may like to consider to compare 0% purchase credit cards. You can select the “Go to Site” button of your preferred credit card to proceed with your application. You can also contact the provider if you have specific questions. A gentle reminder, please ensure to read through the relevant product disclosure statement and terms and conditions to ensure that you got everything covered before you apply.
Cheers,
Jonathan
If we move our balance to a new credit card do we have to close the account it came from?
Hi Diane, thanks for your inquiry!
That is correct, it is the primary cardholders responsibility to close the existing credit cards when transferring to a new credit card.
Cheers,
Jonathan
what are my chances of getting a credit card when im not getting a weekly wage only fortnightly payments from centrelink
Hi Shareen,
Thanks for your inquiry.
Some credit cards have low minimum income requirements of $15,000 to $35,000 per year to be approved. You may try to apply for a low-income credit card and check your eligibility.
You may also refer to our guide to loans for Centrelink recipients.
Before applying, please ensure that you meet all the eligibility criteria and read through the details of the needed requirements as well as the relevant Product Disclosure Statements/Terms and Conditions when comparing your options before making a decision on whether it is right for you.
Cheers,
Jonathan
We received an email about a card where you get 6 Months Interest Free on all purchases over $250 and you can buy at retailers who offer Interest Free. It is a Once Agile Visa Card. Do you think this would be better ongoing as a card or keep doing balance transfer swaps to new cards with 0% interest offers.
Hi Jason,
Thanks for your question.
Unfortunately I really can’t comment on whether one card is better than the other, as the best card for you will depend on your needs and situation. Six months interest free can be good cards if you’re looking to make purchases for that period. Keep in mind that for your other suggestion, card issuers can see all the cards you’ve recently been approved for and applied for, and applying for multiple cards in a short period of time can negatively affect your credit rating.
I hope this has helped.
Thanks,
Elizabeth