Adding a driver to car insurance
Everything you need to know about adding a driver to your car insurance, unlisted driver excesses and more.
Adding a driver to your car insurance can be done in a few simple steps.
These quotes are accurate as of March 2026
Allowing someone else to drive your car is fine but there are a few things you should be aware of.
If they're a listed driver: If you've already listed this person as an additional driver on your insurance policy, then you've got nothing to worry about. If they're a listed driver then you're technically already sharing your car insurance with them.
If they're not a listed driver: If the person who's driving your car is not listed on your car insurance policy then you may have to pay an unlisted driver excess. This cost varies between insurers but is typically in the range of $400 to $2,000, depending on the insurer and the driver's age.
It's possible to add a driver to your car insurance policy, even if you only want them there for a limited time. You'd follow the same steps as adding a regular driver and when you no longer want them on the policy, you'd call to remove them. If you've already paid a higher premium in advance, then you'll likely receive a refund.
Car insurance can cover other drivers who drive your car. There are two ways for this to happen:
| Brand | Conditions |
|---|---|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
This is accurate as of January 2025
| Response | |
|---|---|
| No | 56.06% |
| Yes | 38.77% |
| Doesn’t apply | 5.17% |
You will generally have to pay an additional excess if they are involved in an accident, which can be more than $2,000. Typically, there's also an age excess charge if they're under 25. You may have to pay a higher excess if the young driver wasn't listed on your policy.
If someone plans to use your car regularly, then the best option is to list them as an additional driver; that way, you don't need to worry about the huge excess. But keep in mind, some insurers will charge you an additional excess regardless of whether they are listed or not.
Some will refuse to cover unlisted drivers altogether. So, it pays to know if this applies to you. Be sure to read your product disclosure statement (PDS) to be aware of any policy exclusions.
While CTP (Compulsory Third Party) insurance covers injury liability for anyone driving your car with your consent, regardless of who is listed on your comprehensive policy. Your comprehensive car insurance is different: some insurers only cover drivers listed on your policy certificate, apply age-based excess loadings, and exclude cover for unauthorised drivers.
You should always check with your provider, or read your policy's Product Disclosure Statement (PDS) as to how listed and unlisted drivers are taken into account.
If someone plans to use your car frequently, it's wise to add them to your insurance. That's so that if they ever get into an accident, you're not stuck paying a hefty unlisted driver excess.
Keep in mind, if the person you're looking at adding is the main driver of the car, then you have to add them to your policy - it's insurance fraud not to. You must be truthful about who the main driver of the car is.
But if they're not the main driver and just an additional driver, it's up to you if you wish to add them.
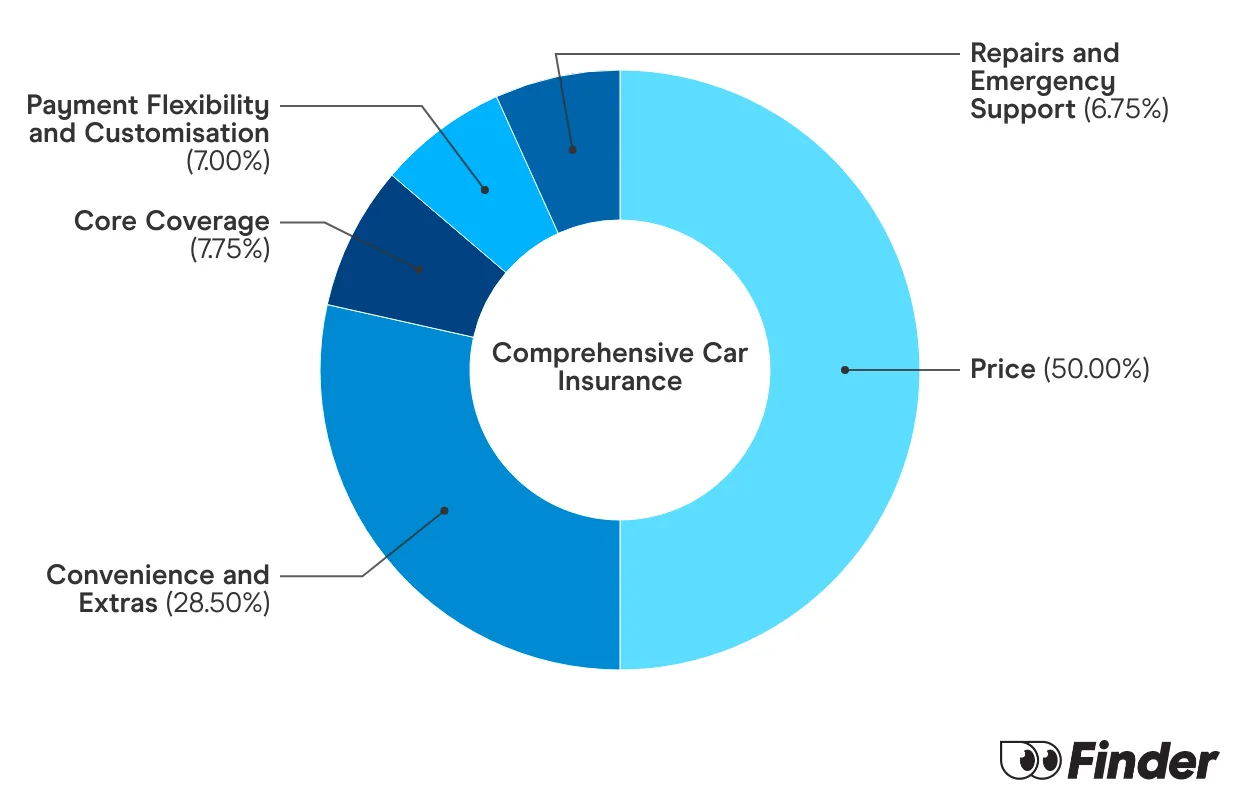
We analyse over 30 car insurance products across insurance providers, and rate each one for price and features. We collect up to 36 quotes per product, for male and female drivers in New South Wales, Victoria, Queensland, South Australia, Tasmania and Western Australia. Quotes are collected for 20 year olds, 30 year olds and 60 year olds, assuming an excess of $850 for a 2020 Toyota Corolla 4 door sedan model, with an average 15,000 kms driven each year. While we are not allowed to display actual quotes, our Finder Score aims to serve as an indicative guide to how cost and feature competitive a product might be for you.
Our feature score assesses each product for more than 15 features across loss and damage coverage, repairs and assistance coverage, personal items coverage and policy coverage. Features we assess include but are not limited to legal liability, essential repairs, new car replacement, car hire events, roadside assistance, agreed or market value, windscreen damage and natural disaster coverage.
If you’ve got one of these cars, you should seriously consider upgrading.
Would you know what to do if you were involved in a car accident? This guide looks at the steps to take after an accident has occurred, from securing the scene to making a claim with your insurer.
Find out what 24/7 Roadside Assistance covers you for and how much policies cost.
RACV’s roadside assistance offers premium cover with strong benefits - but the price point may put some drivers off.
Find out if Allianz Roadside Assistance has a policy that's right for you.
AAMI roadside assistance: Find out what's covered, how much it costs & more.
A list of roadside assistance options in Tasmania.
Your guide to Youi Roadside Assistance.
A quick summary of NRMA Roadside Assistance.
Read on to see if St.George car insurance is right for you.

My listed driver had accident at his fault. Is it effected my driving history and my insurance premiums
Thanks
Gamini
Hi Gamini,
There’s a chance this could affect your insurance premiums in future but this will vary between insurers and likely depend on who the listed drivers are on your next policy. Typically, they’ll ask if you or any listed drivers have been in an accident and you must answer honestly. When it comes time to renew or switch your car insurance, it could be worth getting in touch with the insurer to see what your options are.
We assisted our son to purchase a vehicle (we paid some & he took a loan for balance), the deal is it’s both of our vehicle. Can we list him as a driver if he took out a part loan on it?
Hi Jude,
When it comes to listing drivers for car insurance, it’s important to list whoever will be the main driver of the car, regardless of who paid for it. Some insurers will also ask you to list all additional drivers who may drive the car too. If you’re unsure about who to list, it might be worth calling your insurer to discuss your circumstances so they can help you know who is the best person to list as a driver.
Thanks,
Peta