Looking for other options? Check out these similar products.
How we picked theseKey takeaways
- Use the table to compare 4 year fixed rate home loans from various lenders.
- With 4-year fixed rate home loans your repayments stay exactly the same for the first 4 years of the loan.
- 4-year fixed rates tend to be higher than shorter fixed rate loans and are often close to or above variable rates.
Why should I fix my home loan rate for 4 years?
Most Australians go for variable rate home loans. Borrowers who do fix typically do so for 1-3 years. 4 year fixed rate home loans tend to have higher rates than variable rate loans and other fixed rate loans.
This would make your home loan more expensive and you wouldn't be able to take advantage of any rate cuts that might take place over that period. If you want to refinance the home loan or end it during the 4-year fixed period, you'll pay a hefty fixed rate break cost.
But there are some reasons people choose these loans:
- Repayment certainty. Your repayments won't change for 4 years. This means you know exactly how much to budget for your mortgage repayments for quite a long time. For some people, that beats the savings that come with a lower interest rate.
- Forget about rate rises. Borrowers on variable rate home loans know that their home loan rate could rise at any time. With fixed rate loans, you don't have to worry. For some borrowers, this peace of mind is worth getting a higher rate.
- Fixing for the long term. Fixing your rate for 4 years appeals to a borrower who wants to "set and forget" their rate.
Why are 4-year fixed rate loans less popular?
There are a couple of downsides to fixing for a long time that put off many borrowers:
- Higher rates. Rates for a 4-year home loan tend to be higher than most fixed rate loans. This makes your monthly repayments more expensive.
- Higher break costs. If you exit a home loan early or need to refinance suddenly, you have to pay a break fee if you have a fixed rate loan. The fixed rate break cost is determined partly by your loan amount, your rate and how long is left on your fixed period. The longer you have left, the higher the cost will be.
"It's really a matter of personal choice as to whether you opt for a 4 year fixed rate or not. It's impossible to know how 4 years might play out, so you'll never know if you could miss out on better rates over that time. Instead of trying to time the market you should decide based on whether locking in your repayments makes you feel more secure.
In the right environment it could work to your advantage. Borrowers who took out a 4 year fixed rate in 2021 when rates were at their lowest would have missed out on all the rate rises we saw in 2022 and 2023."
How do 4-year fixed rate home loans work?
A 4-year fixed rate home loan is like any other home loan – you borrow money and repay it over the loan term. But for the first 4 years of the loan, your repayments will stay the same every month.
The revert rate
After the fixed period, your loan reverts to a variable rate loan. Variable interest rate home loans can change at any time as lenders respond to changes in money markets and the overall economy.
When your fixed rate ends, it's a good time to compare home loans and see if you can get a better deal on a new variable rate loan. You could also get a new fixed rate loan instead.
Other fixed rate periods
Most lenders offer fixed rates between 1 and 5 years. Learn more about different fixed periods with these guides:
Are 4-year fixed rates higher than variable rates?
Typically, interest rates for 4 year fixed rate loans are higher than variable rates. But the Reserve Bank has raised the cash rate four times in 2026, which puts upward pressure on both variable and fixed rates.
The average owner occupier 4 year fixed rate for November 2026 is 7.09%.
The average owner occupier variable rate for November 2026 is 7.14%.
Is it too late to lock in a low 4-year fixed rate?
You can see the current difference between fixed and variable rates on our average interest rates guide.
With the cash rate rising through 2026, fixed rates have started to increase.
How do I compare 4-year fixed rate home loans?
To make sure you get a great deal on a 4-year fixed rate loan, pay attention to the rate, the fees and the loan's features.
Focus on the following:
Get a lower rate
Even if fixed rates are higher than variable rates, it's important to compare multiple 4-year fixed rates to find a good deal. Why pay more interest for no reason?
Get a loan with low fees
Some home loans have lots of fees and others have none. A lower interest rate is more important, but the fewer the fees, the cheaper the loan will be.
Loan features
Fixed rate loans have fewer features than variable rate loans, like 100% offset accounts or the ability to make extra repayments. But some do, so it's worth comparing.
More questions about fixing your home loan rate for 4 years
-
Most fixed rate loans don't let you make extra repayments. Some do, but charge an early repayment fee, while other loans limit the extra amount you can repay (usually to around $15,000 a year).
If you want to pay off your loan faster, you should get a loan with an offset account or find a loan with unlimited extra repayments. This is probably a variable rate loan.
-
Fixing for such a long time is not a popular choice (apart from a brief period of incredibly low rates in the early 2020s). A long fixed rate term is not really about locking in the lowest rate possible. It's about certainty and being able to budget your repayments exactly.
-
It's hard for the average person to understand interest rate moves. Lenders and banks are largely free to set their own rates on home loans, but they are guided by the broader economy and how easy (and cheap) it is for them to borrow the money to fund home loans.
The Reserve Bank of Australia also plays a big role. The bank sets the official cash rate, which sets a benchmark for the cost of institutions to lend and borrow money. When the cash rate goes up, lenders raise variable interest rates for borrowers. But they also start to raise fixed rate loans for new customers.
Follow Finder's monthly cash rate predictions to find out where the experts think rates are heading.
-
A split rate loan allows you to divide your loan into fixed and variable rate portions. This means you can lock in 50% of your loan for 4 years and have the remaining 50% on a variable rate.
A split rate lets you have the best of both worlds and is a way of hedging your bets if you're concerned about rate rises but still want the extra features and repayment options on a variable rate loan.
What is Finder Score?
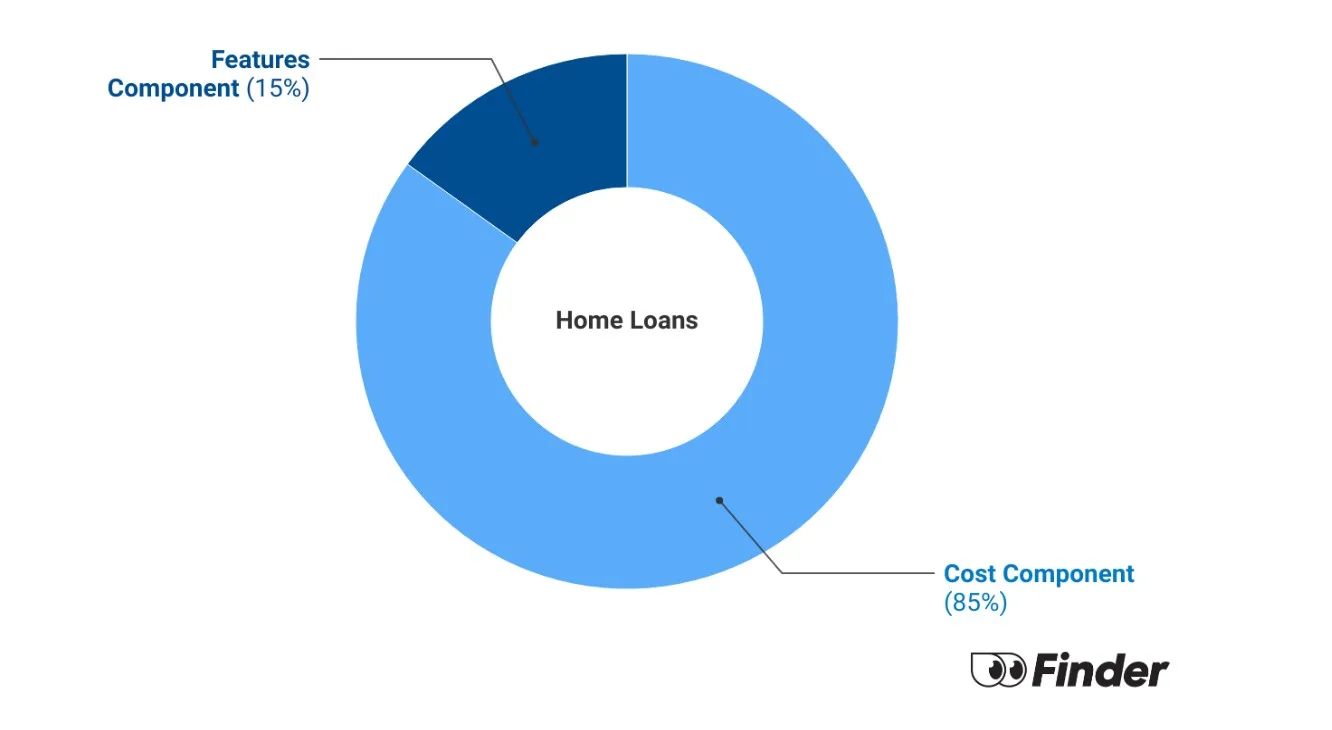
The Finder Score crunches 7,000 home loans across 120+ lenders. It takes into account the product's interest rate, fees and features, as well as the type of loan eg investor, variable, fixed rate - this gives you a simple score out of 10.
To provide a Score, we compare like-for-like loans. So if you're comparing the best home loans for cashback, you can see how each home loan stacks up against other home loans with the same borrower type, rate type and repayment type. We also take into consideration the amount of cashback offered when calculating the Score so you can tell if it's really worth it.
-
Finder writers are subject matter experts and use primary sources, in-depth research and interviews with other experts to ensure you're getting accurate, up-to-date information. Articles are fact checked in line with our editorial guidelines.
- Finder database, accessed 15 April 2026
Richard Whitten is Finder’s Senior Money Editor, with over eight years of experience in home loans, property, credit cards and personal finance. His insights appear in top media outlets like Yahoo Finance, Money Magazine, and the Herald Sun, and he frequently offers expert commentary on television and radio, helping Australians navigate mortgages and property ownership. Richard started his career in education and textbook publishing in South Korea. He holds multiple industry certifications, including a Certificate IV in Mortgage Broking (RG 206) and Tier 1 and Tier 2 certifications (RG 146), as well as a Bachelor of Education from the University of Sydney and a Graduate Certificate in Communications from Deakin University. See full bio
- Home loans
- Credit cards
- Personal finance
- Money-saving tips
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
More guides on Finder
-
10-year fixed mortgage rates
While getting a 10-year fixed rate home loan might be a good idea if you want to keep your repayments the same over the next decade, you will pay more if interest rates drop.
-
Fixed rate interest in advance home loans
Save on interest rates and enjoy tax savings with fixed rate interest in advance home loans.
-
Why 30 year fixed mortgage rates don’t exist in Australia
Thirty year fixed rate home loans don't exist in Australia, unlike in the US where they're very common.
-
5-year fixed rate home loan rates in Australia
A competitive 5-year fixed rate home loan will see your repayments stay the same for a large chunk of your home loan.
-
Compare 3-year fixed rate home loans
A fixed-rate home loan can offer you stability and peace of mind. Find out if a three-year fixed rate home loan is right for you.
-
2-year fixed rate home loans
Enjoy the stability of knowing your repayments won’t change for 2 years.
-
Compare 1-year fixed rate home loans
Find a competitive 1-year fixed interest rate home loan. Compare your options and apply today.
-
Fixed home loan break cost – how much does it cost to end a fixed loan?
Early repayment adjustment, also known as a break fee, is charged when you end a fixed loan contract. Learn how banks calculate these fees.