Your personal valuables
Includes damage or theft to your laptop, TV, designer clothes, jewellery and more.
Was this useful?
Why did you choose this rating?

By
Nicola MiddlemissEdited by
Tim BennettUpdated
Looking for other options? Check out these similar products.
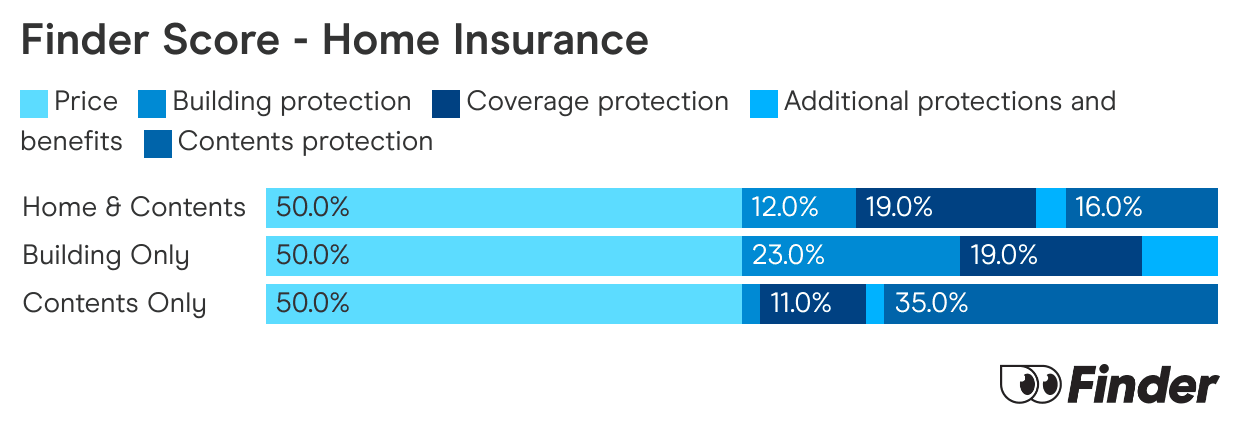
How we picked theseWe crunch eligible home insurance products in Australia to see how they stack up. We rank over 50 products on 16 different features, including price. We end up with a single score out of 10 that helps you compare home insurance a bit faster. We assess home and contents, building only and contents only products individually.
Here are some of the main things in your apartment that contents insurance can help protect.

Includes damage or theft to your laptop, TV, designer clothes, jewellery and more.
Covers additions to your apartment like bathroom vanities, stovetops and air conditioners.
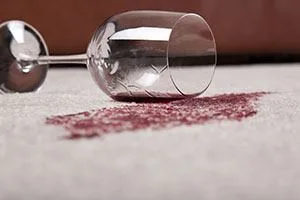
Cover for mishaps like spilled wine, a smashed TV screen or a burst water pipe.
Legally, you're not required to have insurance for your apartment. However, it's a good idea to take out a policy if you have any expensive items that you'd like to protect.
Lots of renters could benefit from contents insurance. If your home is burgled or a water pipe bursts and ruins your things, contents insurance can help you foot the bill.
Your apartment building is likely covered by strata, but you may want to add fixtures and fittings cover, as well as contents insurance. That way, you'll be covered for things like a damaged air-conditioner, as well as your belongings.
If you're renting your apartment out, you should look at landlord insurance.
"I recently had a bicycle stolen from the lock-up garage in my building's basement. The thieves were able to get into the basement, and then they literally bent back the door of my garage, so they didn't even need to break the lock! I would have had the bicycle covered if I had a apartment contents insurance policy, but I didn't. I figured that I lived on the 5th floor, so I would never need to worry about theft. I was incorrect!"
Contents insurance is important for anyone who has items in their home which would be expensive to replace. It doesn't matter whether you live in a studio apartment or a three-story townhouse, contents insurance is worth considering. It can protect everything from your TV and audio equipment, to expensive jewellery and designer clothing.
There are many ways to reduce the cost of home insurance, like increasing your excess and taking advantage of discounts. If you live in an apartment, there are a few extra things to consider when trying to save.
Insurance will only help cover you for accidents and the unexpected. It won't help if the damage is caused by your own neglect. Here are some tips to help prevent damage and loss to your apartment.
Regular maintenance of the apartment will help you identify areas of wear and tear before they cause problems.
Increasing security with security doors and surveillance cameras can help deter thefts.
Hiring professional handymen to help with more technical jobs can save you time and stress.
Compare apartment insurance now
If you own the apartment, you may want to protect permanent fixtures. All you have to do is take out additional "fixtures and fittings" cover on top of your contents insurance policy. This will cover things like bathroom and kitchen cabinets, air-conditioners and anything fitted to your apartment. This type of cover is usually only available when there is a body corporate or strata insurance.
The body corporate, which is sometimes referred to as the owners' corporation, is responsible for managing and maintaining the common areas of an apartment block. As the owner of an apartment or unit in the property, you become a member of the body corporate and can have a say in the decision-making process to do with all matters concerning common areas.
The body corporate is made up of all lot owners in the strata scheme and performs the following important roles:
The body corporate may vote to get a professional strata management team to manage the building on its behalf, or it may decide to take care of all management tasks itself.
Strata insurance covers any shared areas within the apartment building. So that could be things like the roof, lifts or pool. It's compulsory, so you and your neighbours will all be obligated to have strata insurance. You can learn more about what's covered, and how to find a policy, on our strata insurance page.
Home insurance generally covers the building, while contents insurance covers your belongings. Because apartment owners are required to get strata insurance, you don't need home insurance. However, you may want to buy contents insurance and add on cover for fixtures and fittings.
You'll need to consider buying landlord insurance. Landlord insurance covers all your fixtures and fittings in the apartment, which includes things like window blinds, carpets and light fittings.
These policies also include financial protection against a number of other risks, such as if a tenant defaults on their rental payments or if a public liability claim is made against you. Some landlord insurance policies will even cover your loss of rent if the apartment suffers contents damage and becomes uninhabitable for a period of time.
If you need cover for an apartment you want to rent out as an investment property, check out our guide to landlord insurance for more details on how this type of insurance works.
Nicola Middlemiss is a journalist with nearly a decade of experience in personal finance and insurance. She has contributed to Domain, Yahoo Finance, Money Magazine and Insurance Business Australia, offering in-depth insights into commercial insurance in the Australian market. Nicola holds a Bachelor’s degree in English from the University of Leeds and a Tier 1 General Insurance (General Advice) certification, which complies with ASIC standards. See full bio
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
Learn what strata insurance is and what to look for in a policy.
Discover what impacts the cost of home insurance and how to get the right protection with this handy guide.
Compare home insurance providers in Queensland. Protect your home from cyclones, floods, fire and more.
Coles Home Insurance is convenient and generous with its rewards. Just don’t forget to read the fine print.
Here's a detailed review of Bendigo Bank home insurance with information on 3 cover options.
Youi home insurance is slightly more expensive than the national average, but has a good range of benefits
Allianz's Home & Contents insurance includes higher benefit limits than some other popular providers, but it can be lacking in optional extras.
Follow these steps to find affordable home insurance that won't leave you stranded.
What you need to know about finding the best home insurance for you. Compare policies and learn what questions to ask when researching insurance policies.
Compare home and contents insurance - our research shows you can save up to $1,653 by switching.
Finder is a comparison service. We do not compare every product or every provider in the market.
We make money through commercial arrangements with some of the providers on this site. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement.
Our editorial content, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements.
The default order of products in our tables can be influenced by commercial arrangements. You can re-sort or filter using the controls above each table.
Some content on this site may be generated or supported by AI tools. You should verify details directly with the provider.
Finder is one of Australia's leading comparison websites. We are committed to our readers and stand by our editorial principles.
Our comparison service does not include every product or every provider in the market. Some product issuers offer their products under multiple brands or through associated companies. Where we can, we identify the underlying issuer so you can compare like with like, but you should always check with the provider directly to confirm which brand you are dealing with.
Finder is a comparison website and an intermediary. We are not a product issuer and we do not provide personal financial or credit advice. When you click a link to a product, or apply for a product through our site, you deal directly with the product issuer. We may receive a referral fee, commission or other payment from the issuer if you click through, apply or take out a product. We describe these arrangements in more detail under 'How we make money' below.
Product features, fees, terms and eligibility criteria are set by the product issuer and may change. We rely on information supplied by issuers when we present product details on our site. Before you apply for or take out any product, you should confirm the details directly with the issuer.
We earn revenue from Finder in four principal ways:
Referral fees and commissions. When you click a product link, complete an enquiry form or apply for a product through our site, we may receive a referral fee, commission or other payment from the product issuer. We may also receive payment based on the volume of leads or conversions we send to an issuer.
Sponsored placements. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement between Finder and the issuer. These labels always indicate a paid placement. We do not use them for editorial choices.
Display advertising. Banner advertising, newsletter advertising and similar display ads on our site are paid by advertisers.
Content sponsorship. Some articles, videos and social media posts are sponsored by an issuer and are clearly labelled as such.
Our editorial opinions, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements. A 'Top Pick' is an editorial choice made by our writers and editors based on the criteria described on each comparison page. A 'Top Pick' is not a personal recommendation and does not mean the product is appropriate for your circumstances.
If you would like to know whether we have a commercial arrangement with a specific product issuer, please contact us.
When products are grouped in a table or list, the default order can be influenced by commercial arrangements we have with product issuers. In some categories, sponsored or featured products appear in the top positions of the table by default, and are always labelled as such.
Other factors that influence default order include price, fees and features, and (where relevant) our editorial view of the product.
You can re-sort every comparison table using the controls above the table. You can filter by product features that matter to you. The order you see after re-sorting or filtering is not influenced by commercial arrangements.
Some content on this site is generated or supported by artificial intelligence tools, including our AI-powered assistant FinderBot. AI-generated content may contain errors. Please verify important information directly with the product issuer before making a financial decision. For more information about FinderBot, see the FinderBot Terms of Use and FinderBot Privacy Collection Notice.
Please read our website terms of use and privacy policy for more information about our services and our approach to privacy.
We update our data regularly, but information can change between updates. Confirm details with the provider you're interested in before making a decision.
Thank you for your feedback
Our goal is to create the best possible product, and your thoughts, ideas and suggestions play a major role in helping us identify opportunities to improve.