Key takeaways
- There are a few ways to insure your holiday home but it depends on how you use it.
- If you're using the holiday home for yourself, you can choose from multiple home & contents insurance policies. If you want to rent out your home for something like Airbnb, you'll need holiday let insurance.
- Consider add-ons for your policy for more thorough coverage.
Finding holiday home insurance is easy. If you want to keep your holiday home to yourself, a home and contents insurance policy is the way to go. Just make sure to check your PDS for how long the home can be left unoccupied – this varies by insurer and is commonly 60–90 consecutive days – and tell your provider if it will be empty for longer.
If you plan on renting out your place for longer than 90 days, you'll need to look for a policy like landlord insurance. For short stays like Airbnb, your best option is probably to go with a holiday let insurer like ShareCover.
Option 1: Holiday home insurance for your place
If you have a holiday home that you use for vacations and weekend getaways, you want to make sure it's properly looked after for when you're there and when you're not around. To do that, you'll need home insurance.
There's often one big difference between getting insurance for the house you're in most of the time and a holiday home — if you don't visit it for an extended period of time, it'll be considered unoccupied by the insurer. The unoccupancy limit varies by insurer and is commonly 60–90 consecutive days. If your holiday home is unoccupied for longer than the limit, your cover may be affected or you may need to meet additional conditions when making a claim. Check your policy's PDS for the specific unoccupancy limit and conditions.
What are the benefits of getting holiday home insurance in Australia?
Holiday home insurance provides peace of mind. It can ensure that you're financially covered for the following:
- Storm and rainwater damage
- Fire damage
- Theft (or attempted theft)
- Escape of liquid (e.g. a burst pipe, especially important if you're not home)
- Lightning
- Impact at home (e.g a tree falls on your property)
- Breakage of glass and other fixtures
- Malicious damage, vandalism
- Earthquake or tsunami
- Furniture, furnishings and kitchenware
- Computers and electrical appliances
- Clothing
- Other valuables including jewellery, sunglasses and cameras
- Blinds, curtains, fitted carpets and rugs
Here's your holiday home insurance comparison
Looking for other options? Check out these similar products.
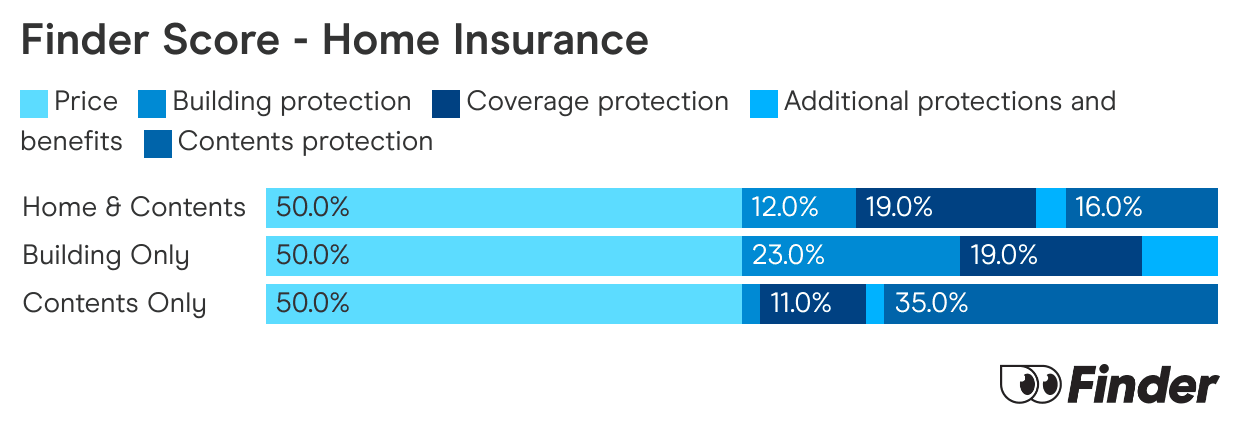
How we picked theseFinder Score - Home insurance
We crunch eligible home insurance products in Australia to see how they stack up. We rank over 50 products on 16 different features, including price. We end up with a single score out of 10 that helps you compare home insurance a bit faster. We assess home and contents, building only and contents only products individually.
What's not included?
It's important to know what's not included when you buy home insurance for your holiday home.
- Renting out your holiday home. If you want to rent out your holiday home, a home and contents insurance policy won't cover you. You would need landlord insurance, and even then, most policies will only cover you if you're renting out for longer than 90 days.
- Failing to keep your home in a lived-in state. This might seem like a strange one, but it's for security purposes. If your house appears unkempt, for example the grass isn't mowed and the mailbox is full, it lets burglars know that nobody is home. Keep it tidy and any claims you make during this period won't be refused.
- Upsizing. If you renovate your holiday home, or add value to the property by making changes, make sure you adjust your cover accordingly. Otherwise those new additions might not be covered.
- Not looking after things. It might not be your main home, but you need to keep on top of your simple repairs. Insurers will expect you to fix leaks, holes and anything that might come under general wear and tear.
Option 2: Looking for something like Airbnb insurance?
If you want to rent out your holiday home, you generally have two options:
- Landlord insurance. Suitable for people who want to rent out their holiday home for longer than 90 days at a time.
- Holiday let insurance. Suitable for short stays like Airbnb or Stayz.
What's covered under these policies?
These types of insurance are a little like extensions for your standard home and contents cover. With it, you can be covered against:
- Malicious and accidental damage caused by tenants and their guests
- Theft by tenants and their guests
- Loss of rental income if a tenant defaults on payment
- Loss of rental income if your property is left uninhabitable following damage
- Loss of rental income if something happens to the tenant so that they are unable to pay
- Changing keys and locks if a tenant doesn't return the keys
- Loss of rental income if your property is left inaccessible and unrentable for reasons beyond your control
- Legal expenses incurred while taking certain actions against tenants
- Legal liability, such as if guests slip and fall, die, or otherwise hold you legally liable for their injury, death or property damage
- Damage to property contents that have been provided for guest use
What's not included?
These are some of the situations and events that a landlord or Airbnb insurance policy will not cover:
- For landlord insurance, you generally won't be covered for Airbnb or Stayz unless they are staying for longer than 90 days
- Some insurers will not cover you if you are only renting out a room (like on Airbnb) but are still living at the property
- Water entering the building through an opening made to renovate or extend the property
- Poor housekeeping by your tenants (e.g unhygienic or untidy living habits)
- General wear and tear, rust, mould or mildew
- Loss or damage caused by insects or vermin
- Repairs carried out by the tenant that you consented to
For a full list of exclusions, be sure to give the product disclosure statement (PDS) a proper read.
Frequently asked questions
-
If your holiday home is mortgaged, then you may be required to take out home insurance on your holiday home. But even if it's not a mortgage requirement, holiday home insurance is a smart way to protect your investment and provide peace of mind. Because you're not always at your holiday home, they could be more likely to be broken into, so it's also a good way to protect yourself from burglary.
In lots of cases too, holiday homes are in rural areas where bushfires, storms and other dangerous weather events are more common. If something major was to occur, holiday home insurance can ensure you're looked after financially if you have to repair or rebuild.
-
If you leave furniture, TVs, appliances, jewellery, artwork or any other valuables at your holiday home, then you need to consider contents insurance.
Consider how hard you've worked to pay for these items and how much it would put a dent in your finances if you were forced to pay to replace them all. You leave yourself open to burglary every time you leave the house, so contents insurance is a smart way to cover yourself should someone break in. Contents insurance can also help out if you haven't visited for a while and a storm or weather event does damage to your property, causing damage to some of your belongings.
-
While you are usually covered for things like weather damage, burglaries and legal liability, accidental damage isn't always automatically included and could be worth it, especially if you have any expensive items.
Also, remember that the unoccupancy limit varies by insurer and is commonly 60–90 consecutive days. Check your policy's PDS for the specific unoccupancy limit and conditions. If you need cover beyond the standard limit, let your insurer know as they may be able to extend the cover for an additional cost.
-
As already stated, if you rent out your place, the insurance you need depends on how long your guests stay for.
- Longer than 90 days. For this, you'll need a type of landlord insurance.
- For short stays like Airbnb. You'll need a type of holiday let insurance like ShareCover.
-
There are a few useful ways to help reduce your holiday home insurance premiums.
- Pay annually. Paying annually is a common but sure way to pay less for your insurance.
- Combine your home and contents. Some insurers give you combined cover at a reduced rate than if you bought them separately.
- Home security. A big reason that holiday home insurance can cost a lot is that the home isn't permanently occupied, leaving you more open to theft. To make your home safer, and potentially lower your premiums, add alarm systems, locks and security lighting.
- Maintenance and repairs. Just like your home, keeping your holiday home in good condition reduces the chances of you having to make a claim.
-
Usually yes, provided the home has not been unoccupied longer than the period stated in your PDS (commonly 60–90 consecutive days) and you have met any security conditions. See the unoccupied home insurance guide for more information.
-
A normal home insurance policy won't cover you if you're making an income from the property, and your policy may also be voided if it's unoccupied for an extended period of time. This is why you need to choose the right policy for your holiday home.
-
It's a pretty common thing to sublet your place (especially if you're renting) if you go on holidays for a few weeks. While subletting could help you pay the rent on your place, it's often not permitted by your landlord since subletting tenants aren't usually covered by their insurance.
Your landlord can't physically stop you from subletting, but it will probably go against your lease agreement.
-
Finder writers are subject matter experts and use primary sources, in-depth research and interviews with other experts to ensure you're getting accurate, up-to-date information. Articles are fact checked in line with our editorial guidelines.
- Budget Direct home & contents PDS (accessed March 2025)
- Youi home insurance PDS (accessed March 2025)
- QBE home insurance PDS (accessed March 2025)
- Honey home insurance PDS (accessed March 2025)
- Kogan home insurance PDS (accessed March 2025)
- Qantas home & contents insurance PDS (accessed March 2025)
- Westpac home & contents insurance PDS (accessed March 2025)
Gary Ross Hunter has over 6 years of expertise writing about insurance, including life, health, home, and car insurance. Having reviewed hundreds of product disclosure statements and published over 800 articles, he loves simplifying complex insurance topics for everyday readers. Gary has contributed to major outlets like Yahoo Finance, The Sydney Morning Herald, and news.com.au, and holds a Bachelor of Arts (Honours) in English Literature from the University of Glasgow, along with a Tier 2 General Advice certification, ensuring his work adheres to ASIC’s RG146 standards. See full bio
- Health, home, life, car, pet and travel insurance
- Managing the cost of living
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
More guides on Finder
-
ALDI home insurance review
ALDI offers home, contents and landlords insurance. Its policies have thorough coverage with generous benefit limits.
-
Defence Services home insurance review
If you serve or have served, you are probably eligible for home insurance with the Defence Service Homes Insurance Scheme.
-
GIO home insurance review
GIO home Insurance has one of the most comprehensive policies around, covering you for environmental upgrades, emergency accommodation + more.
-
RAC home insurance review
If you live in WA, RAC home insurance could be good for you. It comes with lots of benefits and savings, including RAC membership.
-
CBA Home Insurance Review
Compare features and benefits of CBA's home insurance policy. Discover if it's right for you with this handy guide.
-
NAB home insurance review
A review of NAB's home and contents insurance policies. Find out how NAB can cover your house and possessions, giving you peace of mind and protection against the worst.
-
Bank of Queensland Home Insurance
Need home and contents insurance? Check out Bank of Queensland's Vero Secure Home Extra Insurance and Vero Secure Home Elite Insurance policies.
-
Budget Direct Home Insurance Review
Here's a review of the home insurance products available from Budget Direct.
-
Suncorp home insurance review
Compare the home insurance options available from Suncorp.
-
QBE Home Insurance Review
Review and compare policy features here and determine if QBE has a policy that is right for you.