Home insurance for first-time buyers

You usually need to get home insurance when you buy a home in Australia – often before settlement.

4.6 based on 835 reviews

Key takeaways

  • Lenders often require home insurance for houses before settlement, needing a certificate of currency.
  • For strata properties like apartments, building insurance is usually covered by strata fees.
  • Most policies cover fire and storm, but flood cover varies - some insurers include it as standard and others charge extra for it, so check the policy.

Do you need home insurance when you buy property?

Home

Houses

In the majority of circumstances, yes, most lenders will require you to take out home insurance if you have a mortgage and buy a house.

In most cases, you'll need to make sure you have a policy in place before settlement occurs and you take ownership of the house. This is often because your lender will need the certificate of currency (proof of insurance) before you are responsible for the property. Some states, such as Queensland, require you to have cover when you and the seller sign contracts.

Apartment

Apartments and townhouses

If you're buying a strata property, such as an apartment or townhouse, you don't need to take out building insurance – insurance should be included in your strata fees. Your conveyancer should be able to get proof of insurance for you.

Finder survey: Do people think home insurance is worth it?

ResponseFemaleMale
Yes70.34%66.17%
No14.14%22.37%
I don't know15.52%11.47%
Source: Finder survey by Pure Profile of 1113 Australians, December 2023

When you need to get home insurance: State by state

Queensland icon

Queensland

You typically become responsible for the house from 5pm the next business day after the date you sign the contract – this is before settlement.
New South Wales icon

New South Wales

You are responsible for damage from the settlement date. However, lenders will usually make sure you have cover in place before the settlement date.
Australian Capital Territory icon

Australian Capital Territory

You are responsible for any loss or damage to the property when you exchange contracts so the lender will require you to have home insurance in place by the contract date.
Victoria icon

Victoria

You are responsible for damage from the settlement date. However, lenders may require you to have cover in place before the settlement date.
Tasmania icon

Tasmania

You become responsible for any damage to the property on the exchange of contracts so you need to have home insurance in place by the contract date.
South Australia icon

South Australia

You're responsible for loss or damage to the house when you sign the contract – this is before settlement – so you'll need to have home insurance in place by the contract date.
Western Australia icon

Western Australia

You become responsible for the house either when you're given possession of the property or the date the whole of the purchase price is paid – whichever date comes first.
Northern Territory icon

Northern Territory

You become responsible for the property either when you're given possession of it or the date you pay the whole of the purchase price – whichever date comes first.
What should your home insurance policy cover?

All home insurance policies cover you for most major weather events such as bushfires and storms. However, flood cover varies by insurer - some include it as standard, while others only offer it as an optional extra. If you are moving to an area with a history of flooding, check the policy includes it.

Check icon

All insurers typically cover:

  • Fires (including bushfires) e.g. an electrical fault sparks a fire which seriously damages your home.
  • Theft and attempted theft e.g. burglars break into your home and steal your belongings.
  • Storms and rainwater e.g. hailstones damage your roof, letting rainwater inside.
  • Malicious damage e.g. a vandal graffitis your home and puts dents in your garage door.
  • Escape of liquid e.g. a pipe bursts and causes water damage throughout your home.
  • Lightning e.g. a lightning strike punches a hole through your roof.
  • Explosion e.g. a gas leak causes an explosion and destroys your home.
  • Impact e.g. a tree falls onto your house, damaging the roof and walls.
  • Breakage of glass e.g. a stray cricket ball breaks your window or solar panel.

plus icon

You might have to pay extra if you want:

  • Accidental damage. Usually an optional extra but sometimes included as standard. It covers mishaps such as a red wine spill or cracked TV screen.
  • Motor burnout. Also known as fusion damage insurance, it covers the repair or replacement of household appliances if the electric motor dies.
  • Flood cover. Insurers such as Budget Direct and Qantas don't automatically include this in their cover.
  • Specified items. If you have any high-value items, they might not be fully covered by a standard policy (most insurers have a cap of around $1,000). However, you can remove this cap with this add-on.
  • Personal contents. This covers your stuff while it's outside the home. So things like your handbag, backpack or phone.
  • Sum insured safeguard. If your sum insured ends up being less than the cost to repair, the insurer will increase your sum insured by a certain percentage.

How much home insurance do you need?

Figuring out how much to insure your home for is arguably the most important part of taking out home insurance.

calculator

Calculate your sum insured

Your sum insured is the amount your home would cost to rebuild if it was totally destroyed. You usually need to calculate this amount yourself – calculators can help. Make sure that your home is insured for the minimum amount required by your lender. You can usually find this in the loan offer document or by calling your mortgage broker.

sum insured

Consider a sum insured safeguard

Correctly calculating your sum insured is a pretty big onus to place on homeowners. For example, say you select a sum insured of $800,000 but it costs $1 million to rebuild your home – you would be $200,000 out of pocket. To prevent this, some insurers let you add a sum insured safeguard. This is a safety net that prevents big out-of-pocket expenses by providing up to an additional 30% of cover on top of your sum insured.

What's the best policy for first home buyers?

Just like buying a home, there's no one-size-fits-all for home insurance. While we can't say what's right for you, we can show you some policies we feel could be good depending on your situation. For more top picks, you can check out our best home insurance page.

    These policies were chosen based on factors including price, features and unique inclusions. We looked at 17 home insurance brands and analysed over 30 benefits. Remember that there's no single "best" home insurance policy that suits everyone since everyone's needs and budgets differ.

Compare more home insurance policies here

Finder Score Fire, Storm & Theft Damage Flood Accidental damage Escape of Liquid
Optional
Our verdict: With a a range of options available, Youi Building and Contents Insurance is a great pick for homeowners who are after a policy that allows them to find cover to suit their needs.
Get a quote View details
Compare product selection
Optional
Discount: Get 20% off your first year with a combined policy. T&Cs apply.
Our verdict: Finder's Top Pick for Floods plus cover for other common claims such as fire and theft.
Get a quote View details
Compare product selection
Optional
Optional
Get 15% off your first year's premium if you purchase online. T&Cs apply.
Our verdict: The most popular insurer on Finder, Budget Direct prioritises low-cost cover. You need to pay extra for flood cover and accidental damage.
Get a quote View details
Compare product selection
Coles Home Insurance logo
Optional
Optional
Discount: Save up to 30% (15% Online + Up to 15% Combined) off your first year's premium when you take out a new Combined Home & Contents Insurance policy online. T&Cs apply.
Our verdict: This covers what you'd expect in a home and contents policy; fire, storm and theft. There are plenty of optional extras available for those who'd like more thorough coverage.
Get a quote View details
Compare product selection
Budget Direct Home Insurance logo
Optional
Optional
Discount: Up to 30% (15% Online + Up to 15% Combined) off your first year's premium for a new combined Home and Contents policy purchased online. T&Cs apply.
Our verdict: The most popular insurer on Finder, Budget Direct prioritises low-cost cover.
Get a quote View details
Compare product selection
Qantas Home Insurance logo
Optional
Optional
Bonus points offer: Earn up to 35,000 Qantas Points for joining by 25 November 2026. Plus save up to 30% on your 1st year’s premium - 15% when you take out a new policy online, and up to 15% when you combine home and contents. T&Cs apply.
Get a quote View details
Compare product selection
Kogan Home Insurance logo
Optional
Discount: Get up to 10% off your first year's premium when you apply online and $10 monthly Kogan credit (valid on $100+ purchases) for active policyholders. T&Cs apply.
Get a quote View details
Compare product selection
Huddle Home Insurance logo
Discount: Get 10% off your premium when you purchase Home and Contents Insurance. T&Cs apply.
Get a quote View details
Compare product selection
Seniors Home Insurance logo
Discount: Get up to 20% off when you buy a combined home and contents policy. This includes a 10% discount for purchasing a combined policy and an additional 10% discount for valid Seniors Card holders. Terms, conditions, underwriting criteria and minimum premiums apply, which may reduce discount.
Our verdict: Make sure your rebuild costs are accurate though – Australian Seniors don’t do underinsurance cover.
Get a quote View details
Compare product selection
Qantas Home Insurance logo
Optional
Optional
Bonus points offer: Earn up to 35,000 Qantas Points for joining by 25 November 2026. Plus save 15% on your 1st year’s premium when you purchase online. T&Cs apply.
Get a quote View details
Compare product selection
Coles Home Insurance logo
Optional
Optional
Save 15% off your first year's premium when you take out a new Contents Insurance policy online. T&Cs apply.
Our verdict: This policy covers contents only. It includes some decent benefits like up to $5,000 worth of cover for jewellery and up to $2,000 for tools of trade.
Get a quote View details
Compare product selection
QBE Home Insurance logo
Optional
Get up to 10% off your first year online. T&Cs apply.
Our verdict: It covers essentials such as fire and theft plus comes with some good perks such as security upgrades after a burglary.
Get a quote View details
Compare product selection
Kogan Home Insurance logo
Optional
Get up to 10% off your first year's premium when you buy new online Contents Insurance, plus a $10 monthly Kogan.com credit (valid on $100+ purchases). T&Cs apply.
Get a quote View details
Compare product selection
Youi Home Insurance logo
Optional
Our verdict: A highly customisable policy with strong customer satisfaction. If you'd rather talk to a person than buy online, Youi's a good fit.
Get a quote View details
Compare product selection
Seniors Home Insurance logo
10% discount for valid Seniors Card holders. T&Cs apply.
Our verdict: It covers accidental damage, unlike many others. Make sure you value your contents properly though – Australian Seniors don’t do underinsurance cover.
Get a quote View details
Compare product selection
Huddle Home Insurance logo
Get a quote View details
Compare product selection
QBE Home Insurance logo
Optional
Our verdict: It covers essentials such as fire and theft plus comes with some good perks such as environmental upgrades and up to 10% off your first year.
Get a quote View details
Compare product selection
Budget Direct Home Insurance logo
Optional
Optional
Get 15% off your first year's premium if you purchase online. T&Cs apply.
Our verdict: The most popular insurer on Finder, Budget Direct prioritises low-cost cover. You need to pay extra for flood cover and accidental damage.
Get a quote View details
Compare product selection
Qantas Home Insurance logo
Optional
Optional
Bonus points offer: Earn up to 35,000 Qantas Points for joining by 25 November 2026. Plus save 15% on your 1st year’s premium when you purchase online. T&Cs apply.
Get a quote View details
Compare product selection
Youi Home Insurance logo
Optional
Our verdict: A highly customisable policy with strong customer satisfaction. If you'd rather talk to a person than buy online, Youi's a good fit.
Get a quote View details
Compare product selection
Coles Home Insurance logo
Optional
Optional
Save 15% off your first year's premium when you take out a new Home Insurance policy online. T&Cs apply.
Our verdict: This covers what you'd expect in a building only policy; fire, storm, theft and more. There are plenty of optional extras available for those who'd like more thorough coverage.
Get a quote View details
Compare product selection
Kogan Home Insurance logo
Optional
Get up to 10% off your first year's premium when you buy new online Home Insurance, plus a $10 monthly Kogan.com credit (valid on $100+ purchases). T&Cs apply.
Get a quote View details
Compare product selection
Seniors Home Insurance logo
10% discount for valid Seniors Card holders. T&Cs apply.
Our verdict: Good if you want a cheaper option. It covers most of the same things as Australian Seniors Top policy (except for accidental damage) but has lower payout limits.
Get a quote View details
Compare product selection
Huddle Home Insurance logo
Get a quote View details
Compare product selection
Huddle Home Insurance logo
Get a quote View details
Compare product selection
Huddle Home Insurance logo
Get a quote View details
Compare product selection
Seniors Home Insurance logo
10% discount for valid Seniors Card holders. T&Cs apply.
Our verdict: It covers accidental damage, unlike many others. Make sure your rebuild costs are accurate though – Australian Seniors don’t do underinsurance cover.
Get a quote View details
Compare product selection
loading

Finder Score - Home insurance

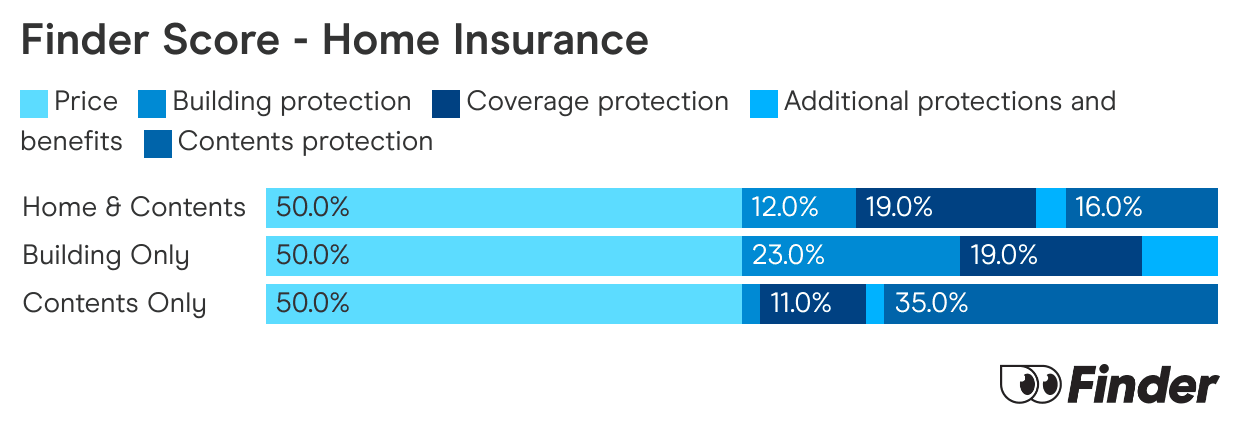
We crunch eligible home insurance products in Australia to see how they stack up. We rank over 50 products on 16 different features, including price. We end up with a single score out of 10 that helps you compare home insurance a bit faster. We assess home and contents, building only and contents only products individually.

Read the full methodology

Frequently asked questions

Jason Loewenthal's headshot
To make sure you get accurate and helpful information, this guide has been edited by Jason Loewenthal as part of our fact-checking process.
Gary Ross Hunter's headshot

Gary Ross Hunter has over 6 years of expertise writing about insurance, including life, health, home, and car insurance. Having reviewed hundreds of product disclosure statements and published over 800 articles, he loves simplifying complex insurance topics for everyday readers. Gary has contributed to major outlets like Yahoo Finance, The Sydney Morning Herald, and news.com.au, and holds a Bachelor of Arts (Honours) in English Literature from the University of Glasgow, along with a Tier 2 General Advice certification, ensuring his work adheres to ASIC’s RG146 standards. See full bio

Gary Ross's expertise
Gary Ross has written 520 Finder guides across topics including:
  • Health, home, life, car, pet and travel insurance
  • Managing the cost of living

Get rewarded $$ for switching with Finder Rewards

Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.

Ask a question

You are about to post a question on finder.com.au:

  • Do not enter personal information (eg. surname, phone number, bank details) as your question will be made public
  • finder.com.au is a financial comparison and information service, not a bank or product provider
  • We cannot provide you with personal advice or recommendations
  • Your answer might already be waiting – check previous questions below to see if yours has already been asked

Finder only provides general advice and factual information, so consider your own circumstances, or seek advice before you decide to act on our content. By submitting a question, you're accepting our Terms Of Service and Finder Group Privacy & Cookies Policy.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

More guides on Finder

  • ALDI home insurance review

    ALDI offers home, contents and landlords insurance. Its policies have thorough coverage with generous benefit limits.

  • Defence Services home insurance review

    If you serve or have served, you are probably eligible for home insurance with the Defence Service Homes Insurance Scheme.

  • GIO home insurance review

    GIO home Insurance has one of the most comprehensive policies around, covering you for environmental upgrades, emergency accommodation + more.

  • Jewellery insurance

    A surprising range of factors will shape your jewellery insurance options. Find out how to make the best choice.

  • RAC home insurance review

    If you live in WA, RAC home insurance could be good for you. It comes with lots of benefits and savings, including RAC membership.

  • CBA Home Insurance Review

    Compare features and benefits of CBA's home insurance policy. Discover if it's right for you with this handy guide.

  • NAB home insurance review

    A review of NAB's home and contents insurance policies. Find out how NAB can cover your house and possessions, giving you peace of mind and protection against the worst.

  • Bank of Queensland Home Insurance

    Need home and contents insurance? Check out Bank of Queensland's Vero Secure Home Extra Insurance and Vero Secure Home Elite Insurance policies.

  • Budget Direct Home Insurance Review

    Here's a review of the home insurance products available from Budget Direct.

  • Suncorp home insurance review

    Compare the home insurance options available from Suncorp.

Go to site