Fixtures: Items that are firmly attached to your home and difficult to remove.
![]()
Fittings: Temporarily attached to the property or free standing items which can be removed.

By
Nicola MiddlemissUpdated
Fixtures: Items that are firmly attached to your home and difficult to remove.
![]()
Fittings: Temporarily attached to the property or free standing items which can be removed.
There are some exceptions to the rule though. For example, carpets can fall into either category: some insurers treat fitted carpet as part of the building, while others cover carpets under contents. We recommend contacting your insurer directly if you need clarification.
Generally, building insurance protects fixtures and contents insurance protects fittings. Combined home and contents insurance policies in the table below protect both, while building-only and contents-only policies cover one or the other.
Looking for other options? Check out these similar products.
How we picked these| Response | |
|---|---|
| Yes | 68.37% |
| No | 18.06% |
| I don't know | 13.57% |
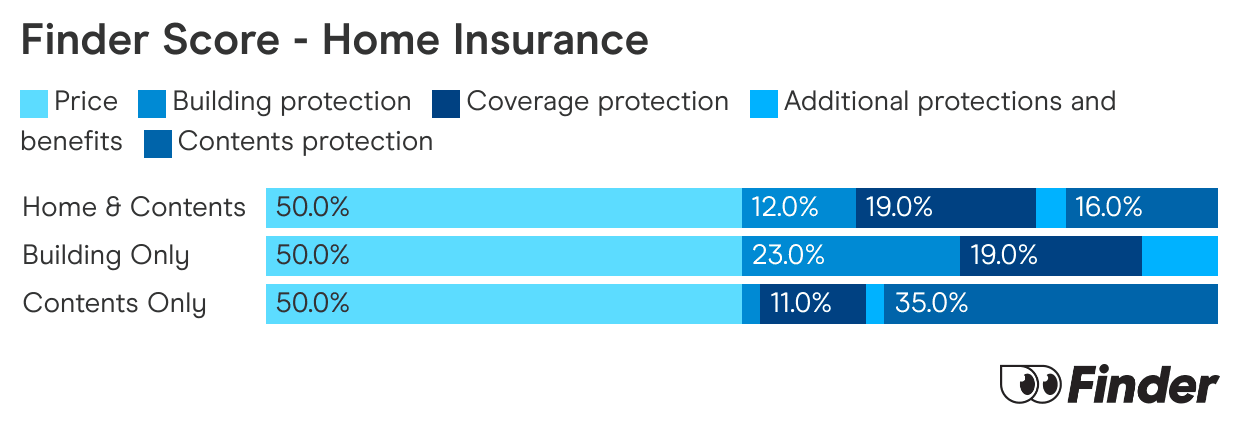
We crunch eligible home insurance products in Australia to see how they stack up. We rank over 50 products on 16 different features, including price. We end up with a single score out of 10 that helps you compare home insurance a bit faster. We assess home and contents, building only and contents only products individually.
Fixtures are items that are firmly attached to your home. There are some exceptions to the rule but generally, you would not take fixtures with you if you decided to move home.
There are two types of home insurance that can cover your fixtures.
This type of policy will cover the physical structure of your home. This includes things like solar panels and your bathroom sink, but it won't include your fittings or contents.
This type of policy is more comprehensive since it will cover both your fixtures and fittings. It covers the physical structure of your house and the belongings you keep in it.
Fittings are items that are freestanding or temporarily attached to your home. Generally, you would take fittings with you if you moved elsewhere. Carpets are a grey area, though: some insurers class fitted carpet as part of the building, while others cover carpets under contents, so check your insurer's PDS.
You can choose from two types of home insurance to cover your fittings.
This policy can cover your fittings and other things you have around your home. Just keep in mind that it won't cover things that are permanently attached to your home, or the physical house itself.
A home and contents insurance policy is probably the more comprehensive option since it can cover both fittings and fixtures. This way, you don't have to figure out which is which.
You can read our beginner's guide on home insurance to learn more about policies which cover both fixtures and fittings.
If you only want to insure the permanent fixtures, check out building insurance. If you're interested in insuring fittings, take a look at contents insurance.
Compare home insurance to cover your fittings and fixtures
To accurately value your fixtures and fittings, you should estimate the replacement cost. This is how much it would cost to purchase new items of similar quality and install them today. For fixtures, consider professional installation costs. For fittings, make a detailed list and research current market prices. Always check your policy wording for specific valuation methods and speak with your insurer if you are unsure.
The classification can sometimes be tricky and depend on how permanently they are attached. Built-in wardrobes that are custom made and permanently fixed to the wall or floor are generally considered fixtures. Custom blinds that are easily removed and not integral to the structure are typically fittings. However, the definitive answer depends on your insurer's specific definition in your policy disclosure statement.
As a landlord you are generally responsible for insuring the fixtures of the property through a building insurance policy. This includes things like built-in kitchens, bathrooms and flooring. You may also need landlord contents insurance to cover fittings that you provide for your tenants use such as curtains, blinds or unfixed appliances like an oven.
As a renter you are generally responsible for insuring your own personal belongings which fall under the category of fittings. This includes your furniture, appliances, clothing and other movable items. The landlord is usually responsible for insuring the property's fixtures. It is highly recommended that renters take out contents insurance to protect their possessions.
Yes it is important to notify your insurer if you make significant improvements or additions to your home that involve new fixtures or high value fittings. Installing new solar panels renovating a bathroom or purchasing expensive freestanding appliances can increase the replacement value of your property. Updating your policy ensures you have adequate cover and helps prevent underinsurance in the event of a claim.
When you sell your home fixtures are generally included in the sale and remain with the property unless specifically excluded in the contract of sale. Fittings however are typically considered personal property and you would take them with you unless they are explicitly included in the sale contract. It is crucial to clearly define what is included or excluded in your sales agreement to avoid disputes. Your insurance coverage should reflect this until settlement is complete.
Icons made by Vectors Market from www.flaticon.com
Picture: GettyImages
Nicola Middlemiss is a journalist with nearly a decade of experience in personal finance and insurance. She has contributed to Domain, Yahoo Finance, Money Magazine and Insurance Business Australia, offering in-depth insights into commercial insurance in the Australian market. Nicola holds a Bachelor’s degree in English from the University of Leeds and a Tier 1 General Insurance (General Advice) certification, which complies with ASIC standards. See full bio
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
Find out how many house break-ins happen in Australia each year, why the numbers are rising and what it means for your home insurance.
ALDI offers home, contents and landlords insurance. Its policies have thorough coverage with generous benefit limits.
From gazebos to furniture to water features, outdoor living home insurance can cover a range of things we keep outside.
Find out how home insurance can cover you for cyclones.
If you serve or have served, you are probably eligible for home insurance with the Defence Service Homes Insurance Scheme.
Want to know the difference between fair wear and tear and accidental damage? Find out here.
A surprising range of factors will shape your jewellery insurance options. Find out how to make the best choice.
Follow these steps to find affordable home insurance that won't leave you stranded.
What you need to know about finding the best home insurance for you. Compare policies and learn what questions to ask when researching insurance policies.
Finder is a comparison service. We do not compare every product or every provider in the market.
We make money through commercial arrangements with some of the providers on this site. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement.
Our editorial content, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements.
The default order of products in our tables can be influenced by commercial arrangements. You can re-sort or filter using the controls above each table.
Some content on this site may be generated or supported by AI tools. You should verify details directly with the provider.
Finder is one of Australia's leading comparison websites. We are committed to our readers and stand by our editorial principles.
Our comparison service does not include every product or every provider in the market. Some product issuers offer their products under multiple brands or through associated companies. Where we can, we identify the underlying issuer so you can compare like with like, but you should always check with the provider directly to confirm which brand you are dealing with.
Finder is a comparison website and an intermediary. We are not a product issuer and we do not provide personal financial or credit advice. When you click a link to a product, or apply for a product through our site, you deal directly with the product issuer. We may receive a referral fee, commission or other payment from the issuer if you click through, apply or take out a product. We describe these arrangements in more detail under 'How we make money' below.
Product features, fees, terms and eligibility criteria are set by the product issuer and may change. We rely on information supplied by issuers when we present product details on our site. Before you apply for or take out any product, you should confirm the details directly with the issuer.
We earn revenue from Finder in four principal ways:
Referral fees and commissions. When you click a product link, complete an enquiry form or apply for a product through our site, we may receive a referral fee, commission or other payment from the product issuer. We may also receive payment based on the volume of leads or conversions we send to an issuer.
Sponsored placements. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement between Finder and the issuer. These labels always indicate a paid placement. We do not use them for editorial choices.
Display advertising. Banner advertising, newsletter advertising and similar display ads on our site are paid by advertisers.
Content sponsorship. Some articles, videos and social media posts are sponsored by an issuer and are clearly labelled as such.
Our editorial opinions, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements. A 'Top Pick' is an editorial choice made by our writers and editors based on the criteria described on each comparison page. A 'Top Pick' is not a personal recommendation and does not mean the product is appropriate for your circumstances.
If you would like to know whether we have a commercial arrangement with a specific product issuer, please contact us.
When products are grouped in a table or list, the default order can be influenced by commercial arrangements we have with product issuers. In some categories, sponsored or featured products appear in the top positions of the table by default, and are always labelled as such.
Other factors that influence default order include price, fees and features, and (where relevant) our editorial view of the product.
You can re-sort every comparison table using the controls above the table. You can filter by product features that matter to you. The order you see after re-sorting or filtering is not influenced by commercial arrangements.
Some content on this site is generated or supported by artificial intelligence tools, including our AI-powered assistant FinderBot. AI-generated content may contain errors. Please verify important information directly with the product issuer before making a financial decision. For more information about FinderBot, see the FinderBot Terms of Use and FinderBot Privacy Collection Notice.
Please read our website terms of use and privacy policy for more information about our services and our approach to privacy.
We update our data regularly, but information can change between updates. Confirm details with the provider you're interested in before making a decision.
Thank you for your feedback
Our goal is to create the best possible product, and your thoughts, ideas and suggestions play a major role in helping us identify opportunities to improve.