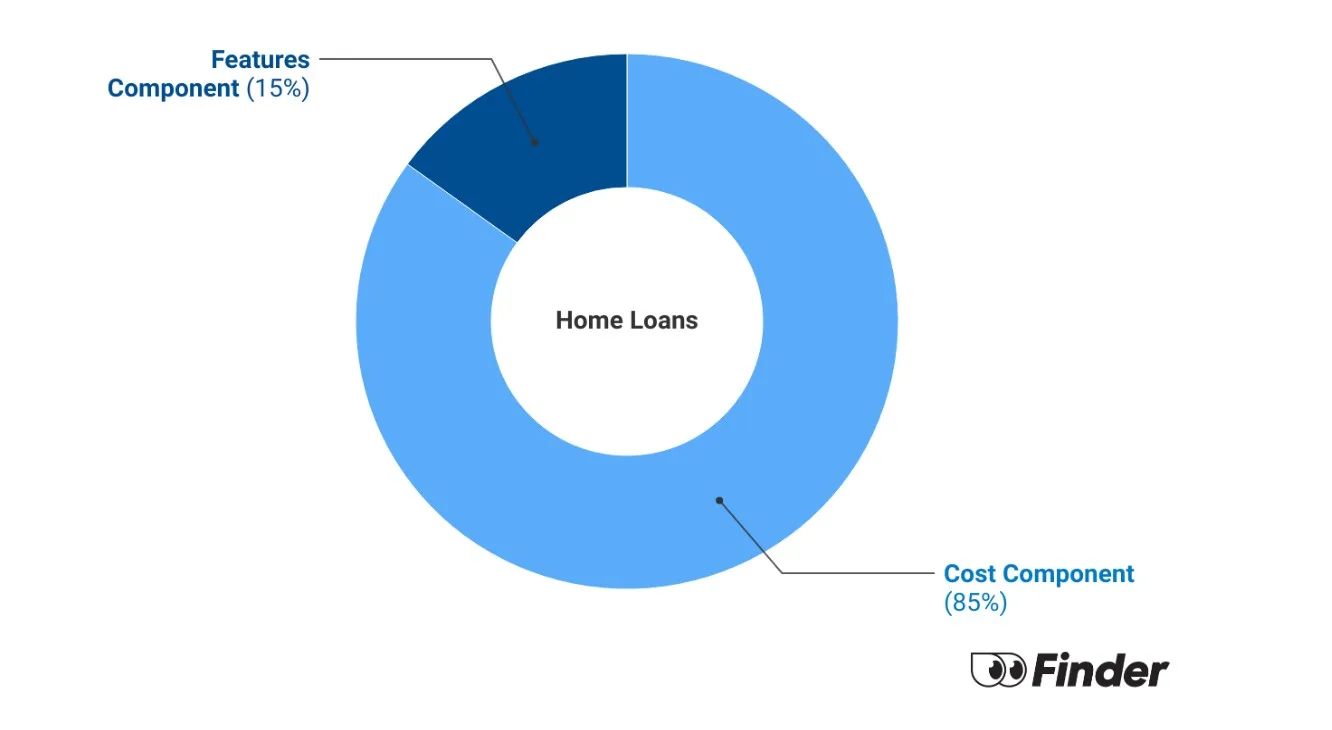
These home loans offer low costs, coupled with a host of features, giving the best overall value.
7+
Great
These home loans may have slightly higher interest rates or fewer features but overall, a competitive offering.
5+
Standard
Usually the home loans would offer above average rates. They may still include some competitive features.
0+
Basic
Higher costs and/or fewer features.
Key takeaways
An owner-occupier home loan is used for the purpose of purchasing a home that you wish to live in.
Owner-occupier loans are treated differently from investment loans for tax purposes.
If you convert your home to an investment property, you will need to inform your lender.
What is an owner occupier?
An owner-occupier is someone who lives in a residential property as their principal place of residence. That is, you live in your own home. They are different from an investor, who purchases a property to use as an investment to create wealth, not as a place to live.
What does 'principal place of residence' mean?
The Australian Tax Office considers a property to be your main residence if:
You live in the home with your family and your belongings are there.
You receive mail and are registered on the electoral roll at that address.
You have utilities connected to the property.
For taxation purposes, the ATO also considers other factors, such as whether the home has been used to produce income that can be taxed. If your property is your principal place of residence, you can claim an exemption from capital gains tax (CGT) when selling your home.
How are owner-occupier loans different from other loans?
The key difference between an owner-occupier home loan and other home loans (such as investment loans) is the loan's purpose. For an owner occupier home loan you must be planning to live in the home you're buying, not renting it out.
In terms of mortgage features and loan details, owner occupier home loans are like other loans in that they have an interest rate and comparison rate, rate types, minimum and maximum loan amounts, various loan fees and maximum (and maximum insured) loan to value ratios.
What to look for in an owner occupier home loan vs an investment loan
The interest rate. Interest rates tend to be lower than investment loans (if looking at otherwise similar mortgages). This is because lenders regard investments as higher risk than homes.
Rate types. OO loans can be either fixed or variable. This is no different to investment loans. You can also choose to split your rate into fixed and variable portions.
Loan to value ratio.Loan to value ratio (LVR) refers to the amount you can borrow in relation to the value of the property. The higher the LVR, the more you can borrow and the smaller your deposit needs to be. While both types of loans can have maximum insured LVRs of up to 95% (meaning you only need a 5% deposit), it is more common on OO loans. A lender may require a bigger deposit for an investment loan.
First home owner grants. If you've never owned property before, you may qualify for various government grants and stamp duty concessions or exemptions. This is something you can't get if you're buying an investment. Keep in mind that grants and concessions differ by state and territory, so you will need to check your local policies.
Repayment type. Owner-occupier loans can have either principal and interest or interest only repayments, just like investment loans. Interest only loans are particularly popular with investors as a way of minimising non-tax-deductible investment costs. But owner-occupiers may use them too if they want to minimise their repayments in the short term.
Features. Owner-occupier loans may come with features like a redraw facility or an offset account. These features are available on investment loans too.
Our expert says: Different borrowers need different loan structures
"While owner occupier home loans can look similar to investment loans and other products, the specific needs of the borrower may differ.
For example, an investor may care more about getting a loan with interest only repayments while an owner-occupier may care about getting a lower interest rate. A first home buyer with a small deposit saved may look for a loan with a high LVR and have their parents act as a guarantor to help them qualify for the home loan.
For borrowers who want to build their new home before they live in it, they too will need a different structure. A construction loan can provide the finance in stages depending on the stage of construction."
Can I change from an owner occupied property to an investment property?
If you convert your home to an investment property, you will need to switch your home loan to a new investment loan. Depending on your lender's policies, you can either apply for a new investment loan or make a variation to your current loan and convert it to an investment loan. Your lender may have a variation form to complete or you may have to call and speak to a lending specialist.
You can also refinance to a new loan with a new lender if you think there's a better deal available. Just be sure to compare investment loan rates and look at exit and switching fees.
Speaking to a mortgage broker is also a good idea, as they can present you with multiple options and help you determine the optimal way to structure your current or new mortgages.
What does the ATO say about changing from an OO property to an investment?
When turning your home into an investment property, the ATO recommends you keep records of details related to the property and the income you generate from the property, such as the following:
Your costs to purchase the property and the date you signed the contract. This is used to calculate your capital gains when you sell the property.
Records of any rental income
Records of all expenses incurred in maintaining or repairing the property, which you can claim as deductions.
Frequently asked questions about owner occupier home loans
Interest only home loans make sense for some property investors because they can claim interest costs on tax (but not principal). Owner-occupiers can't do this and are generally better off with principal and interest repayments.
This is because repaying your loan principal means you are actually repaying your debt. Borrowers who opt for interest only repayments initially end up paying more interest in the end.
Why would owner-occupier borrowers choose interest only then? A major reason is to stay afloat when you're struggling with mortgage repayments. If you've just lost your job or your income is reduced for any reason, switching temporarily to interest only repayments can help you keep your mortgage going without missing repayments.
It's an option that can help you stay on top of your mortgage in the short term, but it will cost you more in the long run.
When you sell your own home, you don't need to pay capital gains tax (CGT). This is a tax charged on investors who sell a property at a profit. Owner-occupiers can claim the main residence exemption mentioned above.
Investors can get a 50% discount on capital gains tax if they have owned the property for more than 12 months.
But investors do have the advantage of being able to claim tax deductions on expenses related to owning and maintaining an investment property. This includes the interest charged on a home loan.
Owner-occupiers can't claim these maintenance or interest costs back on tax. However, if you run a home office or work from home, there are some items and expenses owner occupiers can claim.
There's not really a 'best' home loan. Although the home loan with the lowest rate might be the best loan for some people, it won't necessarily have the features and flexibility that other borrowers require. For example, many borrowers want to know they can maximise their savings with an offset account.
The Finder Score crunches 7,000 home loans across 120+ lenders. It takes into account the product's interest rate, fees and features, as well as the type of loan eg investor, variable, fixed rate - this gives you a simple score out of 10.
To provide a Score, we compare like-for-like loans. So if you're comparing the best home loans for cashback, you can see how each home loan stacks up against other home loans with the same borrower type, rate type and repayment type. We also take into consideration the amount of cashback offered when calculating the Score so you can tell if it's really worth it.
Rebecca Pike is Finder’s money editor, with over 7 years of experience in mortgages and personal finance. A frequent TV and radio commentator, she frequently appears on Sunrise and 7News, Today and 9News, as well as Sky News, Channel 10 and across radio and print. Rebecca previously served as Editor of Mortgage Professional Australia. She has a Master’s degree in Journalism as well as ASIC-recognised certifications in Tier 1 Generic Knowledge and Tier 2 General Advice Deposit Products, which comply with ASIC guidelines.
See full bio
Rebecca's expertise
Rebecca
has written
283
Finder guides across topics including:
If you’re having trouble securing a home loan through traditional means, there are some government programs that might help you achieve your property goals.
Pensioners can have a tough time getting a home loan because each lender treats pension payments differently. Here are some tips you can use to find out whether or not you could get a home loan.
If you haven't sold your house yet, but want to buy your next one before the sale is completed a bridging loan may be able to help. Read on to discover how bridging finance can help.
Low doc home loans allow you to get a mortgage if you're self-employed or don't have regular payslips. check your eligibility and compare competitive offers now.
Important information about this website
Finder is a comparison service. We do not compare every product or every provider in the market.
We make money through commercial arrangements with some of the providers on this site. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement.
Our editorial content, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements.
The default order of products in our tables can be influenced by commercial arrangements. You can re-sort or filter using the controls above each table.
Some content on this site may be generated or supported by AI tools. You should verify details directly with the provider.
Finder is one of Australia's leading comparison websites. We are committed to our readers and stand by our editorial principles.
Our comparison service does not include every product or every provider in the market. Some product issuers offer their products under multiple brands or through associated companies. Where we can, we identify the underlying issuer so you can compare like with like, but you should always check with the provider directly to confirm which brand you are dealing with.
Finder is a comparison website and an intermediary. We are not a product issuer and we do not provide personal financial or credit advice. When you click a link to a product, or apply for a product through our site, you deal directly with the product issuer. We may receive a referral fee, commission or other payment from the issuer if you click through, apply or take out a product. We describe these arrangements in more detail under 'How we make money' below.
Product features, fees, terms and eligibility criteria are set by the product issuer and may change. We rely on information supplied by issuers when we present product details on our site. Before you apply for or take out any product, you should confirm the details directly with the issuer.
We earn revenue from Finder in four principal ways:
Referral fees and commissions. When you click a product link, complete an enquiry form or apply for a product through our site, we may receive a referral fee, commission or other payment from the product issuer. We may also receive payment based on the volume of leads or conversions we send to an issuer.
Sponsored placements. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement between Finder and the issuer. These labels always indicate a paid placement. We do not use them for editorial choices.
Display advertising. Banner advertising, newsletter advertising and similar display ads on our site are paid by advertisers.
Content sponsorship. Some articles, videos and social media posts are sponsored by an issuer and are clearly labelled as such.
Our editorial opinions, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements. A 'Top Pick' is an editorial choice made by our writers and editors based on the criteria described on each comparison page. A 'Top Pick' is not a personal recommendation and does not mean the product is appropriate for your circumstances.
If you would like to know whether we have a commercial arrangement with a specific product issuer, please contact us.
When products are grouped in a table or list, the default order can be influenced by commercial arrangements we have with product issuers. In some categories, sponsored or featured products appear in the top positions of the table by default, and are always labelled as such.
Other factors that influence default order include price, fees and features, and (where relevant) our editorial view of the product.
You can re-sort every comparison table using the controls above the table. You can filter by product features that matter to you. The order you see after re-sorting or filtering is not influenced by commercial arrangements.
Some content on this site is generated or supported by artificial intelligence tools, including our AI-powered assistant FinderBot. AI-generated content may contain errors. Please verify important information directly with the product issuer before making a financial decision. For more information about FinderBot, see the FinderBot Terms of Use and FinderBot Privacy Collection Notice.
Please read our website terms of use and privacy policy for more information about our services and our approach to privacy.
We update our data regularly, but information can change between updates. Confirm details with the provider you're interested in before making a decision.
Our goal is to create the best possible product, and your thoughts, ideas and suggestions play a major role in helping us identify opportunities to improve.