Why did my home loan interest rate change?
Variable interest rates can change at any time. It's usually because of the RBA cash rate, but not always.
If your existing home loan interest rate has changed, that probably means you're on a variable rate home loan.
Variable rate home loans are home loans with interest rates that can change throughout your loan. This is usually because the Reserve Bank of Australia (Australia's central bank) has decided the national cash rate needs to change.
The RBA meets 8 times a year to look at the economic situation and decide whether rates need to increase or decrease (more on that below).
The cash rate is the rate the RBA charges banks for overnight loans.
When deciding to move on the cash rate, the RBA takes several factors into account, such as employment, inflation, gross domestic product, consumer spending and confidence and the performance of the housing market.
The Reserve Bank moves the cash rate to try to balance out growth and inflation.
When inflation is too high, the RBA might increase the cash rate so that mortgage repayments increase. In turn, people have less money to spend on other things and prices of goods will drop.
When inflation is too low, the RBA might cut the cash rate so that people have more money to spend by making it easier to pay off debt.
Although the RBA is the most common reason your home loan interest rate might have changed, it's not the only reason.
A few years ago borrowers' interest rates changed even when there was no cash rate decision. This was put down to global funding pressures on the banks who said they couldn't afford the low interest rates of the time.
The money banks lend you has to come from somewhere, of course.
For most lenders, the source of this money is a mix of deposits and what's known as wholesale debt.
Deposits is the money people and businesses put into their savings accounts or term deposits. According to the RBA, deposits make up about two-thirds of Australian banks' total funding. Yes, those deposits are still your money but banks use them to invest.
Debt makes up around a third of banks' funding, with some leftover coming from equity funding (shares on the stock market and bonds, for example). The banks make money from the interest they charge on debt they lend to borrowers.
Regulatory change can also affect interest rates.
In Australia, banks are regulated by the Australian Prudential Regulation Authority (APRA).
APRA sets capital requirements for banks, which means it determines the ratio of money a bank has to hold in reserve for every dollar it loans out. After the global financial crisis, this ratio increased across the globe.
Not all lenders are regulated by APRA, though. It only oversees what are known as Authorised Deposit-taking Institutions (ADIs). This includes banks, mutual banks, credit unions and building societies.
Many online lenders don't fall under these regulations and because of that, they can often offer a sharper rate than their ADI competitors.
This doesn't always mean, though, that non-bank lenders are totally immune to regulatory change. While they may not be directly impacted by higher capital requirements, many non-bank lenders source at least some of their funding from banks. This creates the possibility that regulatory changes impacting banks can have a flow-on effect for non-banks.
In weighing up the decision to change rates, banks often try to balance the desires of their customers with the desires of their shareholders. While bank profitability tends to make headlines, the number banks really pay attention to is their Return on Equity (ROE).
A bank’s ROE is the amount of net income a bank generates as a percentage of its shareholders’ investment. Cutting rates on home loans will often reduce a bank’s ROE, while raising rates will increase it. In answering to its shareholders, a bank wants to deliver the highest ROE possible without also alienating borrowers. It’s this balancing act that can see a bank move on rates outside of the RBA.
Banks might not come out and say it, but their appetite for growth can play a huge role in the competitiveness of their rate offering. In setting their home loan strategy, banks make a decision about how fast they want to grow their total portfolio of home loans.
Banks often refer to growing at, above or below system growth. System growth is the average growth of the home loan market across all lenders. If a bank decides it wants to grow above system, it means it has a higher appetite for home loans.
To achieve this, it might cut its interest rates independent of the RBA in order to create more home loan demand. If it decides it wants to slow down its growth, it might not be as concerned with bringing a competitive offering to the market. It might even choose to raise rates in order to blunt home loan demand.
"You should never be complacent with your home loan interest rate. At least once a year, regardless of whether or not your rate has changed, you should check how it compares to the rest of the market. Banks and lenders are very good at offering the best rates to new customers instead of existing ones."
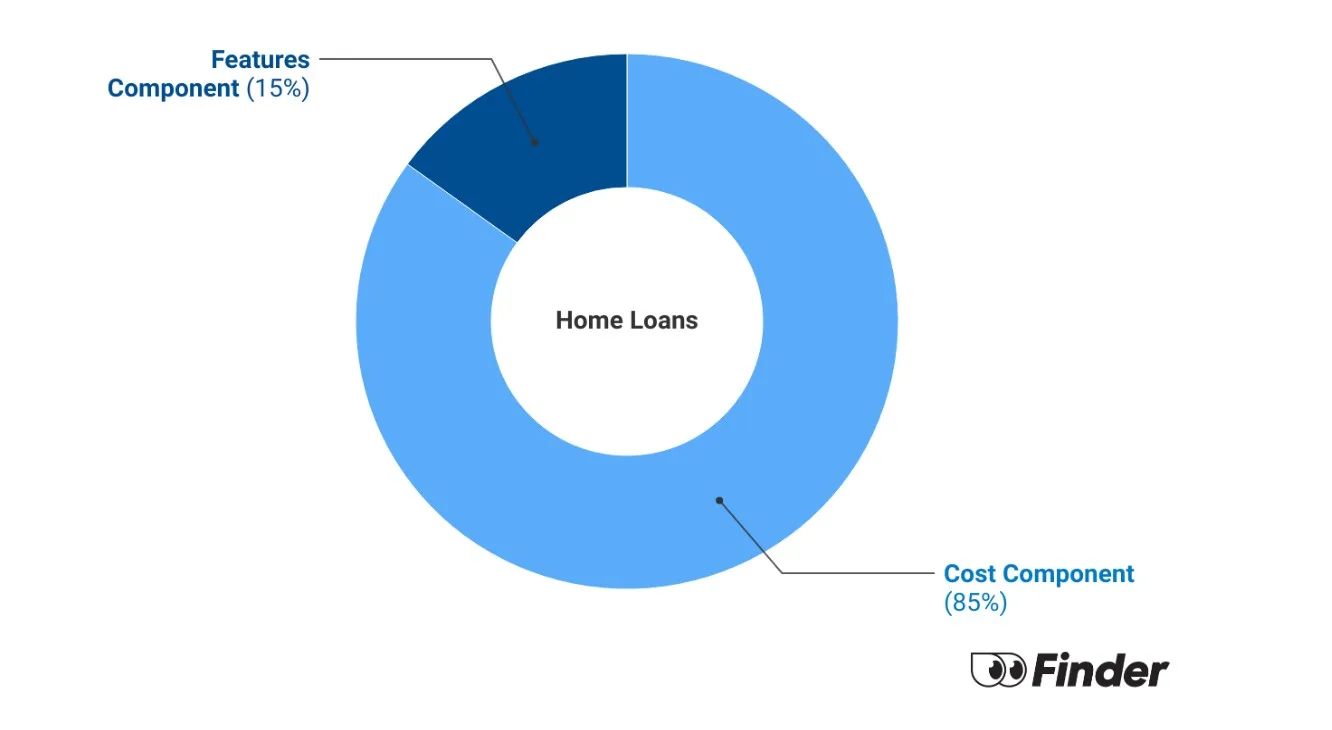
The Finder Score crunches 7,000 home loans across 120+ lenders. It takes into account the product's interest rate, fees and features, as well as the type of loan eg investor, variable, fixed rate - this gives you a simple score out of 10.
To provide a Score, we compare like-for-like loans. So if you're comparing the best home loans for cashback, you can see how each home loan stacks up against other home loans with the same borrower type, rate type and repayment type. We also take into consideration the amount of cashback offered when calculating the Score so you can tell if it's really worth it.
Read our detailed review of reverse mortgage lender Household Capital.
We compile the average home loan interest rates in the market and update them monthly.
Your guide to home loan offers from First Option Bank.
Compare current bank interest rates for home loans, credit cards, personal loans, savings accounts and term deposits to find the best deal for you.
Illawarra Home Loans is a Wollongong mortgage broker that has been arranging home loans since 1989.
Searching for a home loan for contractors? When you don't earn a regular wage, find out how you can still get a home loan.
Find the cheapest home loan rates and learn how to decide which one best fits your needs and will save you the most money.
Find a great deal on a variable interest rate home loan from lenders large and small. Start comparing and saving today.
Learn how to compare rates to find the best home loan and start saving money on your mortgage today.
Compare conveyancing services to find a professional who can help you manage the legal side of buying or selling a property.