Do you run a business from home?
You might find our guide to insuring a home-based business more useful.
By
Gary Ross HunterUpdated
Here's a list of the providers who offer home office insurance. Our table doesn't include prices because quotes are based on your specific circumstances, such as the value of your house and the contents inside it. Compare features first, then you can click through to get a personalised quote.
Looking for other options? Check out these similar products.
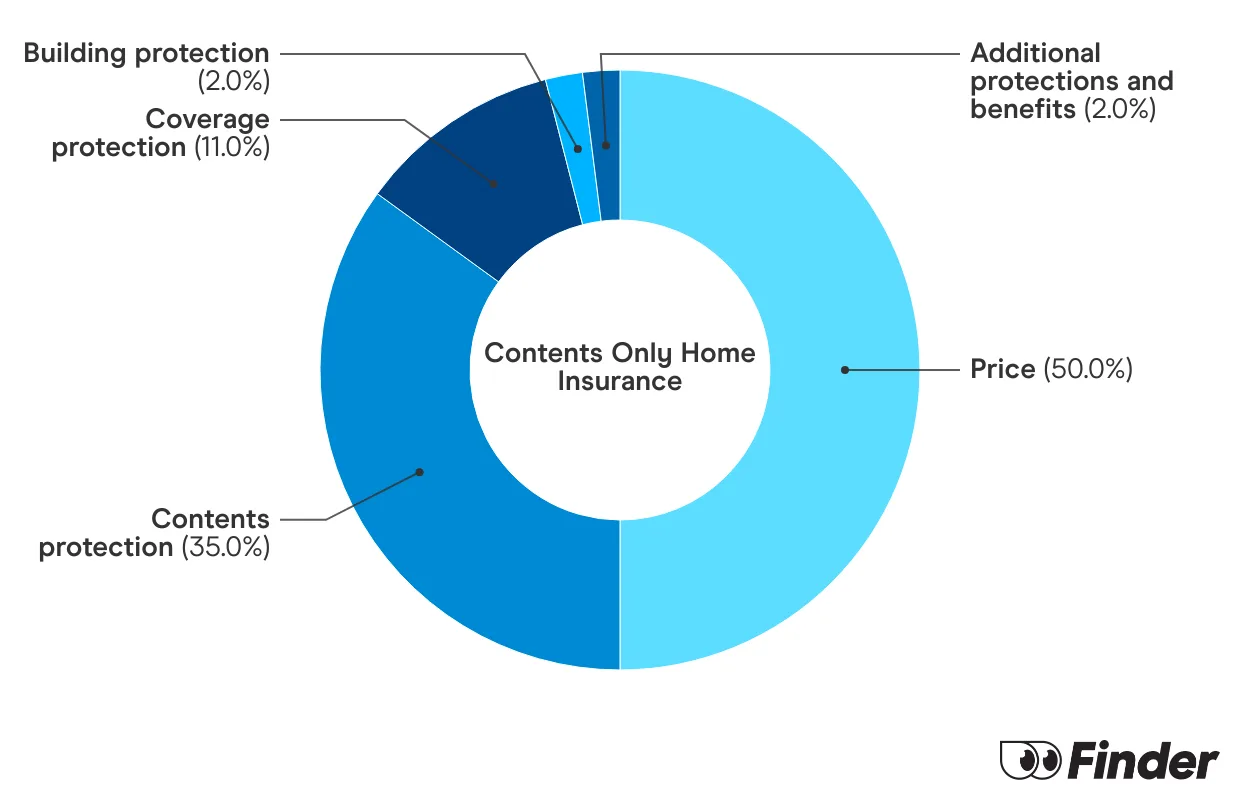
How we picked theseWe crunch eligible home insurance products in Australia to see how they stack up. We rank over 50 products on 16 different features, including price. We end up with a single score out of 10 that helps you compare home insurance a bit faster. We assess home and contents, building only and contents only products individually.
You can get home office insurance with a home and contents insurance policy.
If you have a home office, it can cover clerical items kept in your home. This can include computers, chairs, monitors, headsets, keyboards and other bits and pieces you use to get on with your day job.
It'll be covered under the contents section of your policy, just make sure to check the cover limit.
Here are the home office items that can be covered by a home insurance policy.
You might find our guide to insuring a home-based business more useful.
Yes, it can. If you keep your tools at home, like in a home office or garage, contents insurance can cover you up to a certain amount (often between $1,000 and $5,000) if you get it included under home office insurance. Keep in mind that this only applies when you keep them at home. If you want to get cover for outside the home, you'll need to look for a home and contents insurance policy that allows you to add portable contents cover. You can find out more about insuring tools of trade here.
Household accidents are common. Here's some reasons it might be worth adding accidental damage cover to your policy:
Personal effects cover is for portable items that can be taken away from the home. It's a good idea to get if you also take some of your home office appliances out with you.
There are two types of cover: unspecified personal effects and specified personal effects. Both can protect against accidental loss or damage to a wide range of portable items including cameras, bags, headsets, glasses, laptops and other equipment you use for work.
With the former, you don't need to list the items; you simply choose an individual item limit and a total claim limit. However, you need to list the items with specified personal effects and you can protect them individually for an agreed amount. Taking into consideration your home office equipment,
Every policy has exclusions. With home office insurance, you'll probably find that you won't be covered for:
With working from home now routine for many of us, it's a good idea to update your home insurance policy to ensure your home office is also covered.
Standard home contents policies usually have a sub-limit for home office equipment like computers and monitors. This limit can vary significantly between insurers and policies. For high value items you might need to specify them on your policy or take out additional cover.
Adding specific home office cover or increasing your contents sum insured to account for office equipment may increase your premium. However the exact amount will depend on the value of your equipment, your chosen insurer and any additional benefits you select.
If your employer provides your home office equipment such as a laptop, monitor or chair it is generally their responsibility to insure these items. It is always best to confirm this with your employer as some policies may require you to include it in your home contents cover.
Yes even if you rent your home you can get home office insurance as part of a contents insurance policy. This protects your work equipment, furniture and accessories from insured events like theft or fire. Your landlord's building insurance will not cover your personal or work contents.
No standard home office insurance as part of a home contents policy typically does not cover loss of income or business interruption if your equipment is damaged. For this type of cover you would usually need a specific business insurance policy.
Your home office items are protected against common insured events listed in your home and contents policy. These typically include fire, theft, storm, flood and malicious damage. Always check your Product Disclosure Statement (PDS) for a full list of covered events and any exclusions.
When making a claim for home office items you will generally need to provide proof of ownership and value. This could include purchase receipts, photographs, serial numbers or valuations. Keeping an up-to-date inventory of your equipment is highly recommended.
Gary Ross Hunter has over 6 years of expertise writing about insurance, including life, health, home, and car insurance. Having reviewed hundreds of product disclosure statements and published over 800 articles, he loves simplifying complex insurance topics for everyday readers. Gary has contributed to major outlets like Yahoo Finance, The Sydney Morning Herald, and news.com.au, and holds a Bachelor of Arts (Honours) in English Literature from the University of Glasgow, along with a Tier 2 General Advice certification, ensuring his work adheres to ASIC’s RG146 standards. See full bio
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
Find out how many house break-ins happen in Australia each year, why the numbers are rising and what it means for your home insurance.
Knowing the difference between fixtures and fittings can help you decide which home insurance policy is right for you.
From gazebos to furniture to water features, outdoor living home insurance can cover a range of things we keep outside.
Find out how home insurance can cover you for cyclones.
Want to know the difference between fair wear and tear and accidental damage? Find out here.
A surprising range of factors will shape your jewellery insurance options. Find out how to make the best choice.
Compare features and benefits of CBA's home insurance policy. Discover if it's right for you with this handy guide.
Find out what you will be covered for with RACV Home Insurance.
Follow these steps to find affordable home insurance that won't leave you stranded.
What you need to know about finding the best home insurance for you. Compare policies and learn what questions to ask when researching insurance policies.
Finder is a comparison service. We do not compare every product or every provider in the market.
We make money through commercial arrangements with some of the providers on this site. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement.
Our editorial content, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements.
The default order of products in our tables can be influenced by commercial arrangements. You can re-sort or filter using the controls above each table.
Some content on this site may be generated or supported by AI tools. You should verify details directly with the provider.
Finder is one of Australia's leading comparison websites. We are committed to our readers and stand by our editorial principles.
Our comparison service does not include every product or every provider in the market. Some product issuers offer their products under multiple brands or through associated companies. Where we can, we identify the underlying issuer so you can compare like with like, but you should always check with the provider directly to confirm which brand you are dealing with.
Finder is a comparison website and an intermediary. We are not a product issuer and we do not provide personal financial or credit advice. When you click a link to a product, or apply for a product through our site, you deal directly with the product issuer. We may receive a referral fee, commission or other payment from the issuer if you click through, apply or take out a product. We describe these arrangements in more detail under 'How we make money' below.
Product features, fees, terms and eligibility criteria are set by the product issuer and may change. We rely on information supplied by issuers when we present product details on our site. Before you apply for or take out any product, you should confirm the details directly with the issuer.
We earn revenue from Finder in four principal ways:
Referral fees and commissions. When you click a product link, complete an enquiry form or apply for a product through our site, we may receive a referral fee, commission or other payment from the product issuer. We may also receive payment based on the volume of leads or conversions we send to an issuer.
Sponsored placements. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement between Finder and the issuer. These labels always indicate a paid placement. We do not use them for editorial choices.
Display advertising. Banner advertising, newsletter advertising and similar display ads on our site are paid by advertisers.
Content sponsorship. Some articles, videos and social media posts are sponsored by an issuer and are clearly labelled as such.
Our editorial opinions, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements. A 'Top Pick' is an editorial choice made by our writers and editors based on the criteria described on each comparison page. A 'Top Pick' is not a personal recommendation and does not mean the product is appropriate for your circumstances.
If you would like to know whether we have a commercial arrangement with a specific product issuer, please contact us.
When products are grouped in a table or list, the default order can be influenced by commercial arrangements we have with product issuers. In some categories, sponsored or featured products appear in the top positions of the table by default, and are always labelled as such.
Other factors that influence default order include price, fees and features, and (where relevant) our editorial view of the product.
You can re-sort every comparison table using the controls above the table. You can filter by product features that matter to you. The order you see after re-sorting or filtering is not influenced by commercial arrangements.
Some content on this site is generated or supported by artificial intelligence tools, including our AI-powered assistant FinderBot. AI-generated content may contain errors. Please verify important information directly with the product issuer before making a financial decision. For more information about FinderBot, see the FinderBot Terms of Use and FinderBot Privacy Collection Notice.
Please read our website terms of use and privacy policy for more information about our services and our approach to privacy.
We update our data regularly, but information can change between updates. Confirm details with the provider you're interested in before making a decision.
Thank you for your feedback
Our goal is to create the best possible product, and your thoughts, ideas and suggestions play a major role in helping us identify opportunities to improve.