
Key terms for interest-free days
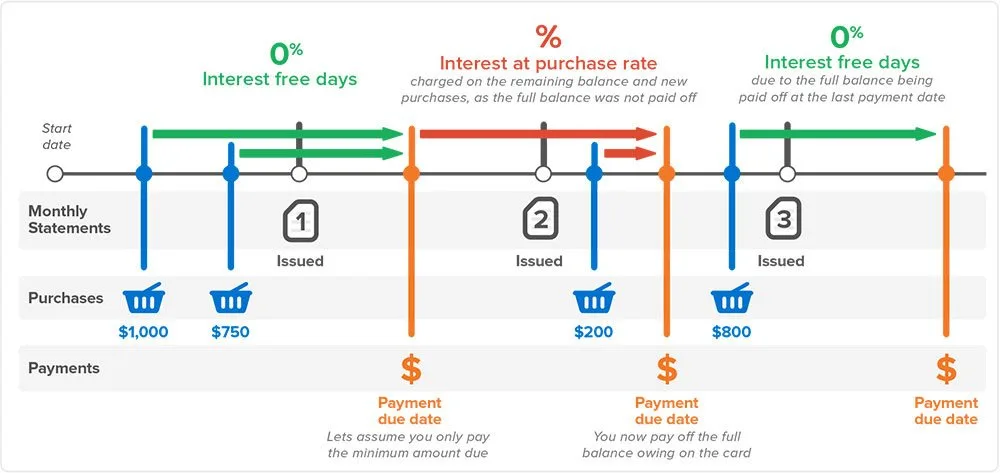
- Statement period or billing cycle. The statement period shows activity on your credit card account and usually runs for 30 days, or from when your last statement was issued to when the next one is issued.
- Payment due date. This date is listed on your statement and tells you when you need to pay at least the minimum amount. If you want to get interest-free days, you'll usually have to pay the total balance by the due date.
- Closing balance or payment closing balance. The total you need to pay by the due date on your statement if you want to get interest-free days for the next statement period. A "closing balance" is usually the total of what's owed on your account.
- Minimum monthly payments. This is the minimum you need to pay by the due date on your statement to avoid late fees and a late payment listing on your credit report. You usually can't get interest-free days for purchases if you only pay this amount.
- Purchase rate. The interest rate charged on purchases. Interest-free days help you avoid this interest charge.

For those that are confused, Yes any purchases in May (Say the 1st of May) would be part of the next statement, and would have 55 interest free days until 25 June… BUT ONLY IF YOU PAID YOUR BALANCE IN FULL FIRST. If you paid the card off to $0.00 on 1 May then your purchase would be interest free until 25 June, if your balance was still outstanding, then even a purchase on 24 May would only have 1 day interest free.
So basically to reset your interest only days and not pay interest:
Pay off the balance of the card before the due date
AND
1.Pay it off on the 1st day (in the example 1 May) of the statement will give you 55 days interest free (in the example up to 25 June)
OR
2. Pay it off on the due date(in the example 25 May) will give you 30 days interest free for purchases before the statement start date (in the example 1 June)
OR
3. If you pay it off on the due date (in the example 25 May) do not use it until the start of the next statement period (in the example 1 June) The you would not have to pay it off until the following months due date (25 July).
Your interest only days ONLY reset after the balance has reached $0.00 so if you had $450 of costs in April, PAID OFF $350 1 May, then SPENT $200 on 24 May, and PAID OFF the $100 left over from the $450 on 25 May, on 26 May you would immediately start paying interest on the outstanding $200 because you never reduced the balance to $0.00.
My suggestion is to have 2 cards, preferably ones that don’t have an annual fee, then simply alternate the cards each month so you can have the full interest free days.
Eg:
Jan:Use card 1
Feb: Use Card 2, Pay off Card 1
Mar: Use Card 1, Pay off Card 2
Apr: Use Card 2, Pay off Card 1
May: Use Card 1, Pay off Card 2
Jun: Use Card 2, Pay off Card 1
etc…
As long as you can pay off the cards, you don’t have a problem, however if having 2 cards just means you will spend more, I would advise against it.
Hi I need help in understanding what may be the best route for me, I owe $8500 on a credit card( which i would like to cancel as soon possible), and need to know which bank may best suit me, I have searched your sight and have been given advice to look into a Balance Transfer, is this a better option than a Personal loan in the long run, I believe that I can afford to pay at least $500 plus each fortnight,
Thank you
Regards
Hi Erin,
Thanks for your question.
There are a number of lenders that can assist you with consolidating your debts. If you are transferring multiple debts from more than one credit card, you need to make sure that the combined debt does not exceed your balance transfer limit.
You can also consider consolidating your credit card debt to a personal loan and also see if you can take advantage of other debt consolidation methods available.
Before applying, please ensure that you meet all the eligibility criteria and read through the details of the needed requirements as well as the relevant Product Disclosure Statements/Terms and Conditions when comparing your options before making a decision on whether it is right for you.
I hope this helps.
Cheers,
Jacob
I thought I understand, but then
you wrote
“if your statement and balance was due on the 25th of the current month, and you made a purchase on the 12th, you only have 13 interest free days.”
Wouldn’t a purchase on the 12th be part of the next months balance. Wouldn’t it have to be paid by the 25th on the *next* month?
everything ok i understood but what if i made the first purchase on april 15 , when my interest will start?
Thank you to the person who wrote and published this information. It was extremely helpful. You have explained it clearly and I now understand why I was charged interest on my credit card despite assuming I had paid off the balance before interest is charged.