Looking for other options? Check out these similar products.
How we picked theseKey takeaways
- Budget Direct often offers the cheapest comprehensive car insurance for P-platers, at around $2,071 annually.
- Adding yourself as an additional driver to a parent's policy can often lower your premiums.
- Consider comprehensive cover if you cannot afford repairs, as policies like ROLLiN' sometimes offer no age-based excess.
Finder Score for car insurance
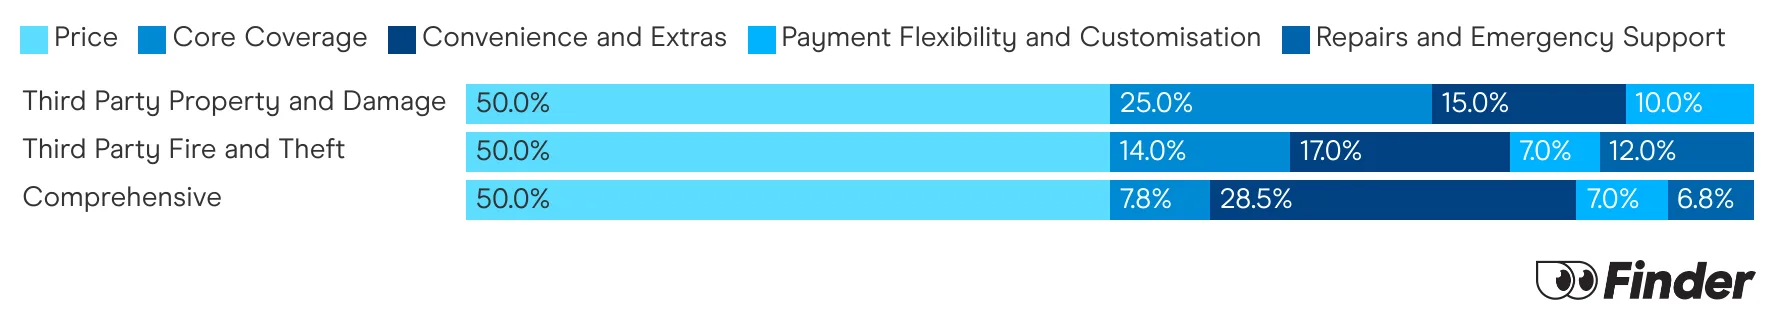
We analyse over 30 car insurance products across insurance providers, and rate each one for price and features. We collect up to 36 quotes per product, for male and female drivers in New South Wales, Victoria, Queensland, South Australia, Tasmania and Western Australia. Quotes are collected for 20 year olds, 30 year olds and 60 year olds, assuming an excess of $850 for a 2020 Toyota Corolla 4 door sedan model, with an average 15,000 kms driven each year. While we are not allowed to display actual quotes, our Finder Score aims to serve as an indicative guide to how cost and feature competitive a product might be for you.
Our feature score assesses each product for more than 15 features across loss and damage coverage, repairs and assistance coverage, personal items coverage and policy coverage. Features we assess include but are not limited to legal liability, essential repairs, new car replacement, car hire events, roadside assistance, agreed or market value, windscreen damage and natural disaster coverage.
Best car insurance for P-platers
Top Pick: Bingle
The main thing most p-platers need is an insurer that will actually give them cover. That and to save a little money. If you can get cover, it’s going to be more expensive, because p-platers are considered much higher risk.
So it’s with that lens that we picked Bingle as the best car insurance for p-platers, whether it’s their comprehensive or third party options. Not only do they not exclude p-platers from cover, like many car insurance companies do, but they are the cheapest to do so.
It’s worth noting that Bingle doesn’t have all the bells and whistles as some of the more expensive insurance companies, at least by default. But if you, like most p-platers, are prioritising affordability, then Bingle car insurance could be the best car insurance for you.
Getting car insurance as a P-plater
There are 3 main ways you can get cheaper car insurance cover as a P-plater. First, adding yourself as an additional driver to your parents' car (as long as they're still the main driver) can lower costs. If that's not an option, a third party policy could be good if you don't own an expensive car. Otherwise, think about getting cheap comprehensive cover.
How much does comprehensive car insurance for P-platers cost?
Looking for other options? Check out these similar products.
How we picked these-
To determine these insurance costs, we sourced comprehensive car insurance quotes for a 19-year-old male and female driver living in postcode 2011 (NSW). The profile used for these quotes assumes a 2020 Toyota Corolla Ascent Sport Direct Shift CVT with an annual mileage of 15,000km. We selected an excess as close to $850 as possible across all providers to ensure a fair comparison. These quotes were obtained in March 2026.
$188
Price based on 100+ responses about their monthly premium in September 2026.
"When I was a p plater, the only insurance I was able to get was NRMA. No one else would cover me. It was actually a real pain in the bum, because the NRMA was charging an extra couple of hundred dollars a year for the same cover. I was pretty poor at the time, so the only way I could save was to take out third party property rather than comprehensive cover."
What cover option is best for P-platers?
Not sure which cover type to go for? Here's the lowdown on each cover type to help you make a decision.
Comprehensive Cover: If you want top cover, this is the option for you. It covers theft, vandalism, storms, flood, hail, fire, key replacement, emergency accommodation, hire cars, accidental damage (to name a few), plus everything covered by cheaper policies.
Best for: P-platers who want peace of mind knowing they have the highest cover available.
Third Party Fire and Theft Cover: As the name suggests, this cover type ensures you are protected if your car is stolen. It also covers you for fire damage and if your car causes damage to someone else's property.
Best for: P-platers who need a bit more cover without the pricetag.
Third Party Property Damage Cover: It's the most basic policy, providing cover for any damage you may cause to someone else's vehicle or property. However, it won't cover the expense of repairing damage your vehicle incurs as a result.
Best for: Those P-platers with cheaper cars or who are on a really strict budget.
Compulsory third party (CTP): CTP is mandatory for every registered vehicle in Australia, but how you buy it depends on your state. In NSW it is called a green slip and you buy it separately before you can register. Everywhere else it is paid as part of your rego, and in some states, including Queensland, you still choose which insurer provides it. CTP protects you if you are at fault in an accident that injures someone else.
Best for: Everyone – it's mandatory!
Expert tips for p-platers looking at their car insurance options
"If you would struggle to pay for repairs to your own car, or your parents if you’re using theirs, then comprehensive car insurance is probably your best bet as a P-plater. It will cost more than a third party policy initially but once you’ve held cover for a while, and you don’t need to claim, prices typically come down."
"As a P-Plater, every birthday you become a little less risky to an insurer, because your experience on the road translates to a lower chance of having an accident. So, make sure you shop around every 12 months and compare policies to get the best possible deal."
What other factors impact the cost of car insurance for P-platers?
There are several other factors that can affect the cost of car insurance for drivers under the age of 25:
- Your gender. Men, especially young ones, are considered more likely to engage in risky driving behaviours than women, so generally have to pay more for car insurance.
- Where you live. Some suburbs have a much higher rate of car theft than others.
- Where the car is kept. If your car is locked in a secure garage overnight, you'll pay much less for cover than if it were parked on the street.
- How often you drive. Vehicles driven frequently are more likely to be involved in an accident than those only driven occasionally.
- The excess you choose. If you have the flexibility to vary your excess, selecting a higher excess will allow you to pay cheaper premiums.
- Any discounts that apply. You may be able to take advantage of discounts to lower the cost of your premium, such as savings for buying online or discounts for insuring multiple vehicles.
Frequently asked questions
-
If you're a P-plater under the age of 25, statistically speaking, you're more likely to be involved in an accident due to a lack of driving experience.
-
There is no universal best car insurance for young drivers because what you need will depend on your personal circumstances. To help find what's best for young drivers, it's worth looking at a range of insurers to understand how they treat young drivers. For example, RoLLiN' car insurance does not add an excess for claims involving a young driver as long as they're listed on the policy. Other insurers will charge an additional excess of around $600. There's no 'best' car insurance for young drivers but there certainly are features of policies - like excesses for those under 25 - that can be appealing for p-platers, and those may be worth considering in your search.
-
According to Finder's research of 5 providers, Budget Direct offers the cheapest comprehensive car insurance policy for p-platers, at around $2,071 a year, while other providers charge between $2,238 and $5,363 for their comprehensive policies.
-
There's no requirement for P-plate drivers to invest in their own car insurance policy, so there's no problem with remaining insured on your parents' policy (as long as they don't mind).
It will often work out cheaper to share cover with mum and dad on the one family policy than for you to go out and purchase a separate policy. You'll need to be listed as a driver on your parents' policy and this will obviously mean their premiums will increase. They might ask you to chip in to cover the cost but if you're lucky they'll foot the bill. However, keep in mind that this option is only viable if the vehicle is owned by the policyholder and they're the main driver – it can't be done if you're the car's legal owner.
-
You might be tempted to save money on P-plate car insurance by putting the policy in your mum or dad's name even though they don't own the car. However, this practice, known as "fronting", is not a good idea. If you try to put your policy in a parent's name when you're the main driver, you run the risk of any claim you make being rejected or your entire policy voided, which can have expensive consequences.
-
Yes. The more expensive your car, the more it will cost to insure. Other vehicle-related factors that influence the cost of cover include:
- Some vehicles stand up to collision damage more than others and are cheaper to repair
- How easy it is to find the necessary parts to repair some vehicles
- Security and alarm systems installed on your vehicle can deter thieves and lower the cost of premiums
- Some makes and models are more popular with thieves and cost more to insure
- Some makes and models are statistically more likely to be involved in an accident
- Older cars are generally cheaper to insure because they have lost a lot of their value and cost less to replace
-
Yes, there are often car insurance deals and discounts available which can be really helpful for p-platers who are looking to reduce the cost of their premium.
Sources
Gary Ross Hunter has over 6 years of expertise writing about insurance, including life, health, home, and car insurance. Having reviewed hundreds of product disclosure statements and published over 800 articles, he loves simplifying complex insurance topics for everyday readers. Gary has contributed to major outlets like Yahoo Finance, The Sydney Morning Herald, and news.com.au, and holds a Bachelor of Arts (Honours) in English Literature from the University of Glasgow, along with a Tier 2 General Advice certification, ensuring his work adheres to ASIC’s RG146 standards. See full bio
- Health, home, life, car, pet and travel insurance
- Managing the cost of living
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
More guides on Finder
-
RAA Roadside Assistance Review
Find out what RAA Roadside Assistance covers you for and how much it costs.
-
24/7 Roadservices Roadside Assistance review
Find out what 24/7 Roadside Assistance covers you for and how much policies cost.
-
RACQ Roadside Assistance Review
RACQ offers strong benefits and service, but drivers can expect to pay higher premiums.
-
TIO Car Insurance
Your guide to TIO Car Insurance.
-
Moped and scooter insurance
Moped and scooter insurance protects you from common risks like theft, natural disasters and property damage.
-
Free windscreen replacement insurance
Discover why taking out windscreen replacement cover for your car could save you pennies in the long run.
-
Suncorp car insurance review
Suncorp’s benefit limits are high in comparison to many other providers, but its policies are more expensive than most.
-
Horse Float Insurance
Compare horse trailer insurance options and get suitable cover for damage, theft, liability and vandalism.
-
RAA car insurance review
Compare policies from RAA and find the right car insurance for your car, motorcycle, caravan or trailer
-
Allianz car insurance review
With a higher-than-average price but no particularly impressive benefits, Allianz was outperformed by many other car insurers in the 2024 Finder Insurance Awards.