Key takeaways
- Standard car insurance usually won’t cover you while ridesharing, so you need to tell your insurer you drive for Uber or DiDi, or your claims could be denied.
- All major rideshare services require at least CTP and third party property damage cover. For damage to your own car, you’ll need comprehensive cover.
- Not every insurer covers rideshare, and some cap how many hours you can drive, so it pays to compare.
Compare car insurance for rideshare drivers
Looking for other options? Check out these similar products.
How we picked theseFinder Score for car insurance
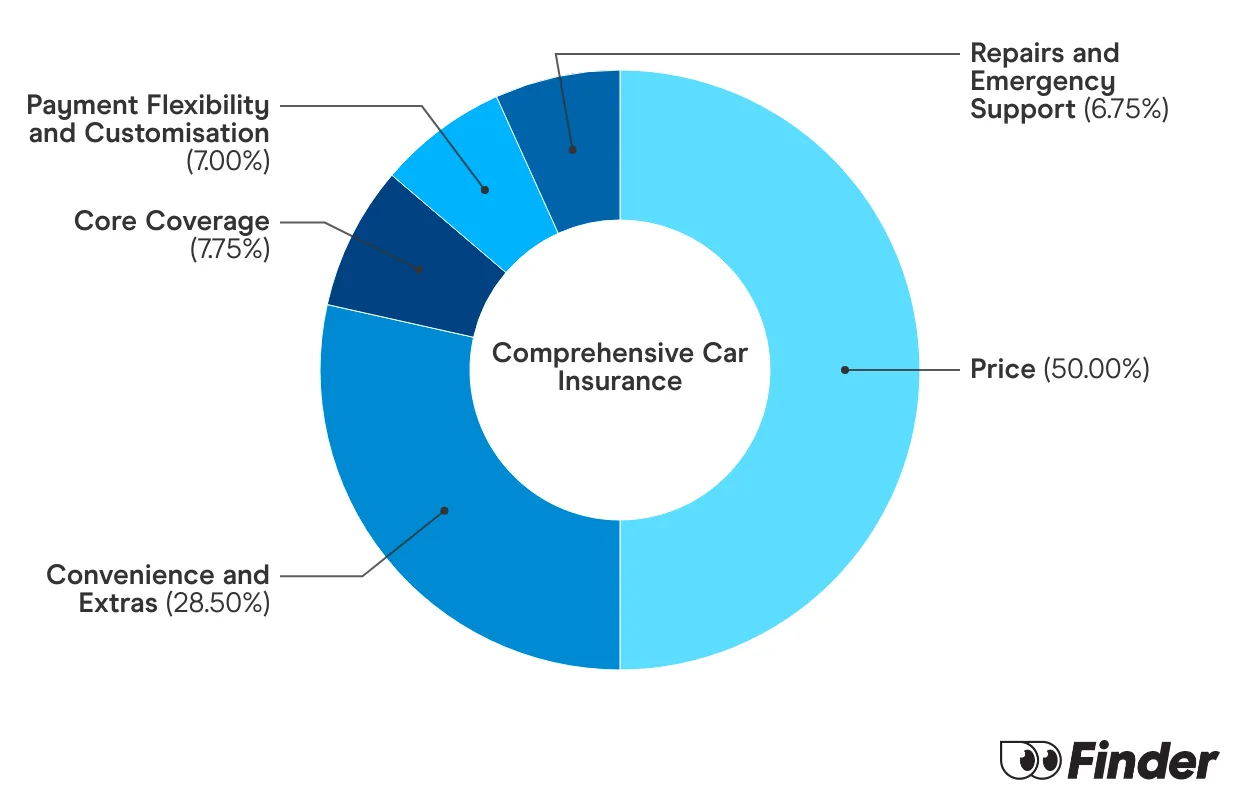
We analyse over 30 car insurance products across insurance providers, and rate each one for price and features. We collect up to 36 quotes per product, for male and female drivers in New South Wales, Victoria, Queensland, South Australia, Tasmania and Western Australia. Quotes are collected for 20 year olds, 30 year olds and 60 year olds, assuming an excess of $850 for a 2020 Toyota Corolla 4 door sedan model, with an average 15,000 kms driven each year. While we are not allowed to display actual quotes, our Finder Score aims to serve as an indicative guide to how cost and feature competitive a product might be for you.
Our feature score assesses each product for more than 15 features across loss and damage coverage, repairs and assistance coverage, personal items coverage and policy coverage. Features we assess include but are not limited to legal liability, essential repairs, new car replacement, car hire events, roadside assistance, agreed or market value, windscreen damage and natural disaster coverage.
Rideshare insurance pricing
We got quotes from a few popular car insurers to see what a quote for a rideshare driver could look like. Keep in mind, the below costs are only for the driver profile we used and your own costs will differ based on your age, car, suburb and driving experience.
| Provider | ~Annual cost |
|---|---|
| QBE | $3,305.26 |
| Kogan | $3,749.93 |
| Bingle | $4,021.10 |
-
To get these quotes, we used the following details:
- 35yr old male
- Sydney based postcode
- Drives a 2019 Toyota Corolla
- Drives up to 15 hours for a rideshare service
These quotes were sourced in April 2026.
Which insurers cover Uber and rideshare drivers?
Not every car insurer will cover you for ridesharing, so this is the first thing to check. Some cover it as standard once you declare it, some cap how many hours you can drive, and others won't cover it at all.
Insurers that currently offer rideshare cover include Youi, ROLLiN', QBE, AAMI and ANZ, though conditions can apply. ANZ, for example, only covers you if you drive under a set number of hours each week. Some popular insurers won't cover your car for ridesharing at all, including Budget Direct, Qantas, Coles and Huddle. If you're with one of these and you start driving for money, you may not be covered.
The table below shows which insurers cover rideshare and where hour limits apply. Always confirm the details in the product disclosure statement (PDS), as cover and conditions can change.
| Insurer | Covers rideshare? | Hour cap |
|---|---|---|
| Youi | Yes | Check PDS |
| ROLLiN’ | Yes | Check PDS |
| QBE | Yes | Under 32 hours per week |
| AAMI | Yes | Check PDS |
| ANZ | Yes | Under 31 hours per week |
| Bingle | Yes | — |
| Kogan | Yes | — |
| Budget Direct | No | — |
| Qantas | No | — |
| Coles | No | — |
| Huddle | No | — |
Why is rideshare car insurance important for rideshare drivers?
If you haven't told your insurer that you're an Uber driver or other rideshare driver, it may refuse to cover you for any accidents that occur while you're working.
Many insurers still don't cover ridesharing. For example, popular insurers such as Budget Direct, Qantas, Coles and Huddle do not cover your car at any time for ridesharing. Others, such as ANZ, will only cover you if you drive less than 31 hours per week, while QBE covers rideshare driving up to 32 hours per week.
All of the main rideshare services in Australia (Uber and DiDi) require you to have compulsory third party insurance (CTP) and third party property insurance. We've outlined more about specific requirements below.
How to find the cheapest rideshare insurance
Rideshare cover costs more than a standard personal policy, because you're on the road more and carrying passengers for money. But there are ways to keep the price down.
- Compare insurers that cover rideshare. Since only a handful offer it, get a quote from each and compare. Prices vary a lot, in Finder's sample quotes, annual premiums ranged from around $3,300 to $4,000 for the same driver profile.
- Match your cover to your hours. If you only rideshare part-time, check whether a policy with an hours cap is cheaper, just make sure you stay under the limit.
- Increase your excess. A higher excess usually lowers your premium, as long as you could afford it if you had to claim.
- Look for new-customer discounts. Several insurers offer online sign-up discounts, so factor those in when you compare.
Rideshare car insurance requirements for different services
Rideshare platforms typically offer some kind of liability cover, but in most cases, you'll need to take out your own individual car insurance policy too. Here are the insurance requirements of each rideshare company in Australia.
Uber
| What insurance do I need? |
|
| Driving requirements | You must
|
DiDi
| What insurance do I need? |
|
| Driving requirements | You must
|
Shebah
| What insurance do I need? |
|
| Driving requirements | You must
|
Rydo
| What insurance do I need? |
|
| Driving requirements | You must
|
How do I find the right rideshare car insurance cover?
Watch out for a cap on hours you can drive
A small number of rideshare insurance policies will only cover you if you drive less than a specified amount per week, often around 32 hours (we've outlined these in the table above). If you're ridesharing for more than that, opt for a provider with no limit.
Decide what level of cover you want
You are required by most rideshare services to have CTP and third party property insurance. This doesn't cover you for damage to your own car though; if you want cover for that, you should get a comprehensive car insurance policy.
Decide what you want covered
All comprehensive rideshare insurance policies should cover you for damage to your own car (usually up to the market value), other people's cars and property, floods, hail, fires and storms. However, features such as a hire car after an accident and windscreen cover, are sometimes optional. (Good to know: you won't be covered for ridesharing a hire car with most insurers but you can still use the vehicle for personal use).
Compare quotes
It's simple to apply for car insurance quotes online, so get multiple policies for a better idea of how much rideshare car insurance costs.
"Don't just assume that your car insurance will cover you for ridesharing – lots don't. You will need to contact them and let them know. Fortunately, there are a handful that do. It's worth getting a quote from each of them to see who is cheapest."
"Moving across to an insurer that offers rideshare cover isn't hard. The switching process is simple once you've found a replacement policy that meets your rideshare needs. I reviewed more than a dozen policies – most insurers charge no more than $40 in cancellation fees."
"If you’re unsure if your insurer offers coverage for ridesharing, it’s always best to check. It’s usually pretty straightforward; you can give them a call, go online and ask their live chat or just use “command+f” to search the PDS for “rideshare”. If it’s still not made clear, it could mean you won’t be covered and it’s time to start looking elsewhere."
What does rideshare car insurance cover if I have an accident?


There are a few injuries and accidents where rideshare car insurance won't cover you. For example, certain personal injuries, such as broken bones, or cover if you can't work. This is where your rideshare platform's injury insurance can help.
Frequently asked questions
-
If you drive for Uber, DiDi or another ridesharing service then yes, you will need rideshare car insurance. An ordinary car insurance policy only covers private use of your vehicle and doesn't cover you if you use your car to carry passengers for profit.
-
The exact process varies between insurers, but you'll typically be able to select the ridesharing option during the application process when asked if you use your car for business purposes.
-
You don't need a special business car insurance policy to drive for Uber. You simply need to select that you will use your car for business purposes when you take out car insurance. Insurers will ask you this during the application process.
-
Yes, if you drive for Uber or any other rideshare company, you'll need to tell your car insurance provider. If you don't, your car insurance policy might be void and any claims you make will be denied. Many insurers automatically exclude transporting passengers for money with a personal car insurance policy unless you let them know.
-
At a minimum, Uber requires drivers in Australia to have compulsory third party insurance (CTP) and third party property damage insurance (TPPD).
-
Yes, you should be able to claim tax deductions on your car insurance. However, you can only deduct the percentage proportional to how much you used the vehicle for work (e.g. business use). Keep a logbook of how much you worked to make calculating this easier. There are other business expenses you can claim, such as the following:
- Fuel expenses
- Your rideshare platform's fees
- Car registration
- Repair and maintenance costs
- Cleaning costs
- Parking fees
- Depreciation on your car's purchase price if you are the owner of the car
- Rental fees if you lease or rent the car
- Tolls that were not covered by your rideshare platform
- Mobile and internet expenses if you use your phone for ridesharing
Make sure you keep receipts and bank records related to these expenses so that you can claim a percentage of them come tax time.
-
The cost of this policy addition will depend on how frequently you rideshare as well as where you live, the type of car and your driving history.
-
Your CTP insurance covers medical and liability costs sustained by passengers in vehicle accidents while you're driving. Uber's insurance policy can also cover passenger medical and liability costs where your own insurance won't. You will need to pay the excess that applies to this cover.
-
Yes. A rideshare car insurance policy typically also covers you for the private use of your car.
-
Yes, driving for Uber or any other rideshare company will likely increase your car insurance costs. There are more risks involved so your premiums are likely to increase. These risks can include potential legal fees if you're involved in a crash or a passenger opening the door and causing an accident. You're also using the car more often, so there's a greater chance of an accident occurring. You might pay a higher premium, but if something happens, you'll be covered.
-
Uber drivers in Australia must have compulsory third party (CTP) insurance for their state or territory of residence and a minimum of third party property damage insurance, with the driver listed as a policyholder or named insured driver.
-
If you do not inform your insurer that you use your vehicle for rideshare services, your car insurance policy might be void and any claims you make could be denied. Many personal car insurance policies automatically exclude transporting passengers for payment.
-
Yes, a comprehensive rideshare insurance policy typically covers you for both ridesharing activities and personal use of your vehicle. Some providers, such as Suncorp, specifically mention 24/7 coverage.
-
Yes, your Compulsory Third Party (CTP) insurance generally covers compensation claims if you cause injury or death to your passengers in a car accident. Some rideshare policies may also offer additional personal accident benefits.
-
CTP (Compulsory Third Party) insurance is mandatory across Australia and protects drivers against the financial impact of causing injury or death in a motor vehicle accident, including coverage for any passengers. It is a legal requirement for vehicle registration and the minimum insurance requirement for all major rideshare providers.
Sources
Gary Ross Hunter has over 6 years of expertise writing about insurance, including life, health, home, and car insurance. Having reviewed hundreds of product disclosure statements and published over 800 articles, he loves simplifying complex insurance topics for everyday readers. Gary has contributed to major outlets like Yahoo Finance, The Sydney Morning Herald, and news.com.au, and holds a Bachelor of Arts (Honours) in English Literature from the University of Glasgow, along with a Tier 2 General Advice certification, ensuring his work adheres to ASIC’s RG146 standards. See full bio
- Health, home, life, car, pet and travel insurance
- Managing the cost of living
Ceyda Erem is Finder’s senior writer for insurance and has almost 10 years of experience writing about personal finance. Formerly a copywriter for several business and finance clients, Ceyda has written hundreds of articles, guides, blogs and more to ensure Australians stay in the loop about how to best manage their money. She has a Bachelor of Arts, Majoring in Writing from Macquarie University. See full bio
- Insurance
- Compare car insurance for rideshare drivers
- Rideshare insurance pricing
- Which insurers cover Uber and rideshare drivers?
- Why is rideshare car insurance important for rideshare drivers?
- How to find the cheapest rideshare insurance
- Rideshare car insurance requirements for different services
- How do I find the right rideshare car insurance cover?
- What does rideshare car insurance cover if I have an accident?
- Frequently asked questions
- Sources
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
More guides on Finder
-
Cheap car insurance Australia October 2026
Here's a guide to getting affordable car insurance that will still cover the essentials.
-
AAMI Roadside Assistance review
AAMI roadside assistance: Find out what's covered, how much it costs & more.
-
Roadside Assistance Victoria
Your guide to getting roadside assistance in Victoria.
-
TIO Car Insurance
Your guide to TIO Car Insurance.
-
Moped and scooter insurance
Moped and scooter insurance protects you from common risks like theft, natural disasters and property damage.
-
Blue Badge Insurance
Our review of Blue Badge Insurance, who offers comprehensive motor insurance and mobility equipment cover for Australians with disabilities and limited mobility.
-
How to cancel your car insurance policy
Your guide to cancelling your car insurance policy.
-
Free windscreen replacement insurance
Discover why taking out windscreen replacement cover for your car could save you pennies in the long run.
-
Horse Float Insurance
Compare horse trailer insurance options and get suitable cover for damage, theft, liability and vandalism.
-
Best car insurance Australia October 2026
Explore our analysis and see how you can find the best car insurance for your needs.