Are outdoor living areas covered by home insurance?

From ponds to pergolas, barbeques to bar fridges, here's how insurance can cover your outdoor living area and the things you keep outside.
4.6 based on 835 reviews

Key takeaways

  • Home insurance can cover outdoor living areas, including permanent structures and fixtures.
  • Contents insurance will cover things that aren't permanently attached, like furniture.
  • Permanent outdoor structures are usually covered within your building sum insured, so make sure it's high enough to rebuild them; high-value items may need to be listed separately.

Protect your outdoor living area with home insurance

8 of 66 results
Finder Score Outdoor Contents Building Cover Home Contents Cover Sum Insured Safeguard Online Discount
Yes
Yes
No
Our verdict: With a a range of options available, Youi Building and Contents Insurance is a great pick for homeowners who are after a policy that allows them to find cover to suit their needs.
Get a quote View details
Compare product selection
Yes
Yes
Yes
Discount: Get 20% off your first year with a combined policy. T&Cs apply.
Our verdict: Finder's Top Pick for Floods plus cover for other common claims such as fire and theft.
Get a quote View details
Compare product selection
Yes
Yes
Optional
Yes
Discount: Up to 30% (15% Online + Up to 15% Combined) off your first year's premium for a new combined Home and Contents policy purchased online. T&Cs apply.
Our verdict: The most popular insurer on Finder, Budget Direct prioritises low-cost cover.
Get a quote View details
Compare product selection
Coles Home Insurance logo
Yes
Yes
Optional
Yes
Discount: Save up to 30% (15% Online + Up to 15% Combined) off your first year's premium when you take out a new Combined Home & Contents Insurance policy online. T&Cs apply.
Our verdict: This covers what you'd expect in a home and contents policy; fire, storm and theft. There are plenty of optional extras available for those who'd like more thorough coverage.
Get a quote View details
Compare product selection
Qantas Home Insurance logo
Yes
Yes
Optional
Yes
Bonus points offer: Earn up to 35,000 Qantas Points for joining by 25 November 2026. Plus save up to 30% on your 1st year’s premium - 15% when you take out a new policy online, and up to 15% when you combine home and contents. T&Cs apply.
Get a quote View details
Compare product selection
Kogan Home Insurance logo
Yes
Yes
Yes
Discount: Get up to 10% off your first year's premium when you apply online and $10 monthly Kogan credit (valid on $100+ purchases) for active policyholders. T&Cs apply.
Get a quote View details
Compare product selection
Huddle Home Insurance logo
Yes
Yes
Yes
Discount: Get 10% off your premium when you purchase Home and Contents Insurance. T&Cs apply.
Get a quote View details
Compare product selection
Seniors Home Insurance logo
Yes
Yes
Yes
Discount: Get up to 20% off when you buy a combined home and contents policy. This includes a 10% discount for purchasing a combined policy and an additional 10% discount for valid Seniors Card holders. Terms, conditions, underwriting criteria and minimum premiums apply, which may reduce discount.
Our verdict: Make sure your rebuild costs are accurate though – Australian Seniors don’t do underinsurance cover.
Get a quote View details
Compare product selection
loading
Showing 8 of 8 results

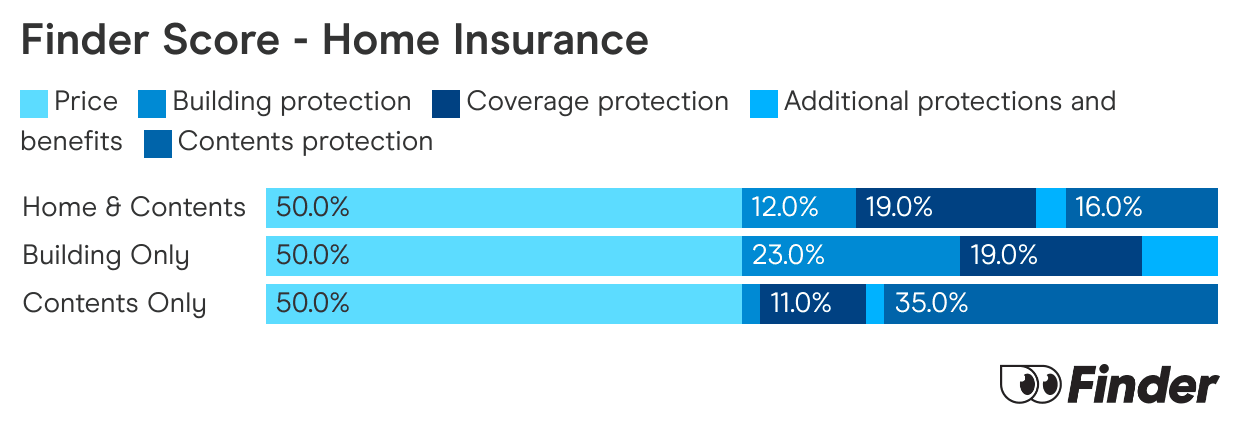
Finder Score - Home insurance

We crunch eligible home insurance products in Australia to see how they stack up. We rank over 50 products on 16 different features, including price. We end up with a single score out of 10 that helps you compare home insurance a bit faster. We assess home and contents, building only and contents only products individually.

Read the full methodology

Does home insurance cover outdoor living areas?

Yes but it depends on what type of home insurance policy you have. In outside areas insurers will generally differentiate between:

  • Permanent fixtures
  • Contents and fittings: things that aren't permanently attached, like portable barbeques and outdoor furniture

Take a look at how each type of home insurance can cover your outdoor areas:


Home/building insurance

Can protect permanent outdoor structures like pools, sheds and pizza ovens from physical damage


Contents insurance

Can cover the things you keep in those structures and elsewhere outside like prized potted plants or a bar fridge


Home and contents insurance

Provides cover for both the physical structure of your outdoor setting and the contents within it, giving the broadest protection

What's a permanent fixture?

Home insurers' definitions can vary slightly, but basically, if it's permanently attached to the property, it's a permanent fixture. Examples include:

  • Outdoor kitchens (including any cupboards and drawers)
  • Barbeques and cooking areas
  • Pergolas and gazebos
  • Decks, verandas and balconies

If one of the above is damaged or lost in an insured event, home insurance can cover it, whereas a straight contents policy won't.

Keep in mind there's a difference between:

  • Fixtures, which are permanently attached to the property, like (in an outdoor kitchen) built-in shelving, light fixtures and stovetops.
  • Fittings, which are freestanding and/or not permanently attached. Examples could include desk lamps, coffee tables and fridges.
Home/building insurance can cover your fixtures, contents insurance can cover your fittings. A home and contents insurance can cover both.

Do I have to list my outdoor fixtures and items on my insurance?

Not usually. Building cover generally includes permanent outdoor structures and fixtures, like fences, sheds, garages and paved areas, within your sum insured, so you don't have to itemise them. What matters is that your sum insured is high enough to rebuild them, so if you've added a deck, pool or outdoor kitchen, increase it. High-value items and anything worth more than your policy's standard limits may need to be listed separately, so check your PDS.

Because home and building insurance and contents insurance cover different things, you'll need to differentiate between permanent fixtures and their contents (including fittings) when you work out your sums insured.

What incidents will I be covered for?

With combined home and contents insurance, you can be covered for repair or replacement costs if an outdoor structure and/or its contents are damaged, destroyed or lost because of:

  • Fire
  • Flood
  • Theft
  • Storm
  • Impact
  • Escape of liquid from your plumbing system or water features
  • Vandalism

For example, you could be covered if:

  • A barbeque or outdoor gas stove malfunctioned and caused fire damage
  • A tree or branch fell and damaged a pergola, outdoor table or garden ornament
  • An antique statue was stolen from your garden

You'll also have the option to include various add-ons, such as accidental damage insurance, that can broaden your cover.

When won't my outdoor living area be covered by home insurance?

Exclusions to your cover might apply if:

  • Your sum insured doesn't cover the full value of an outdoor structure or item, or you haven't listed something your insurer requires you to specify.
  • A pet damages an outdoor structure or item.
  • An outdoor structure or item is damaged or lost because of something that was foreseeable and preventable (e.g. you had a backyard bonfire that got out of hand).
  • An item in a garden bed is damaged or lost – home and building insurance generally ends where your garden beds start. If you have precious plants you want to insure, you can think about garden insurance.

Renovating your outdoor living area? Don't forget this!

If you're renovating an outdoor area, don't make the common mistake of forgetting to update the relevant maximum insured amounts in your policy so they'll reflect:

  • The money you've spent on the upgrade
  • Any new structures to be covered by your building insurance or items to be covered by your contents insurance (e.g. for a new furnished pergola and paved barbeque area)

After pouring money into a renovation, the last thing you want is for the upgraded area to be damaged and then to find you're not covered for its full value because you didn't update your policy.

Keeping the buildings, contents and all-important sums insured in your policy up to date is a key way to get the most out of your insurance.

When you do update your policy, take the opportunity to check whether you could be getting a better deal on your home insurance.

Frequently Asked Questions

Jessica Prasida's headshot
Travel Insurance Expert

Jessica Prasida brings a decade of experience in the travel industry, including over four years as a travel agent and branch manager at STA Travel. She holds a Bachelor of Business and a Master of Marketing from the University of Technology, Sydney, as well as a Tier 1 General Insurance qualification that complies with ASIC guidelines. An avid traveller herself, Jessica combines her professional expertise with a passion for ensuring safe and enjoyable journeys for all travellers. Jessica was a Travel Insurance Publisher at Finder from 2019 to 2024. See full bio

Cameron Thach's headshot
Co-written by

Writer

With a background in writing across education, Web3, and finance, Cameron’s mission is to create content that speaks directly to readers in a way that’s easy to understand, helping them navigate complex topics with confidence. Cameron studied a Bachelor of Commerce, Economics and Marketing at Macquarie University, graduating in 2019. See full bio

Get rewarded $$ for switching with Finder Rewards

Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.

Ask a question

You are about to post a question on finder.com.au:

  • Do not enter personal information (eg. surname, phone number, bank details) as your question will be made public
  • finder.com.au is a financial comparison and information service, not a bank or product provider
  • We cannot provide you with personal advice or recommendations
  • Your answer might already be waiting – check previous questions below to see if yours has already been asked

Finder only provides general advice and factual information, so consider your own circumstances, or seek advice before you decide to act on our content. By submitting a question, you're accepting our Terms Of Service and Finder Group Privacy & Cookies Policy.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

More guides on Finder

  • ALDI home insurance review

    ALDI offers home, contents and landlords insurance. Its policies have thorough coverage with generous benefit limits.

  • Defence Services home insurance review

    If you serve or have served, you are probably eligible for home insurance with the Defence Service Homes Insurance Scheme.

  • GIO home insurance review

    GIO home Insurance has one of the most comprehensive policies around, covering you for environmental upgrades, emergency accommodation + more.

  • Jewellery insurance

    A surprising range of factors will shape your jewellery insurance options. Find out how to make the best choice.

  • RAC home insurance review

    If you live in WA, RAC home insurance could be good for you. It comes with lots of benefits and savings, including RAC membership.

  • CBA Home Insurance Review

    Compare features and benefits of CBA's home insurance policy. Discover if it's right for you with this handy guide.

  • NAB home insurance review

    A review of NAB's home and contents insurance policies. Find out how NAB can cover your house and possessions, giving you peace of mind and protection against the worst.

  • Bank of Queensland Home Insurance

    Need home and contents insurance? Check out Bank of Queensland's Vero Secure Home Extra Insurance and Vero Secure Home Elite Insurance policies.

  • Budget Direct Home Insurance Review

    Here's a review of the home insurance products available from Budget Direct.

  • Suncorp home insurance review

    Compare the home insurance options available from Suncorp.

Go to site