Health insurance for chronic pain
Want more options than what Medicare can offer? Compare 30+ chronic pain health insurance policies.

Pain that lasts more than 3 months - or beyond the normal healing time of a condition following diagnosis, surgery or trauma - is considered chronic.
Common conditions linked to chronic pain include osteoporosis, arthritis and other musculoskeletal illnesses. But there are several uncommon chronic pain conditions as well. These can include kidney failure, heart disease and sleep apnoea.
Acute pain can become chronic pain if it is left untreated. This happens if a change occurs in the nervous system, which makes the body more sensitive to pain. The cause of chronic pain may also be unknown.
Chronic pain treatment generally involves managing and alleviating pain as opposed to eliminating it entirely.
Depending on your condition, it can be treated in a number of ways. Doctors can administer different forms of pain management to alleviate chronic pain. Some may require devices, such as an infusion pump, while others don't, like treatment of nerve pain by injection of a nerve block.
Treatment for chronic pain can include:
To get treatment for chronic pain with Medicare, you'll generally need to get a referral from your GP. Your doctor can prepare a Chronic Disease Management Plan for you. You are only eligible for this care if your GP feels you need it to deal with your chronic pain.
Depending on whether or not a provider accepts the Medicare benefit, you might have to pay the difference between the fee charged and the Medicare rebate. Otherwise, you should have no out-of-pocket expenses.
Management of chronic pain varies greatly. For example, you may receive non-drug treatments such as physiotherapy or acupuncture. Generally, Medicare does not cover most physiotherapy and occupational therapy or psychology services. It might cover acupuncture if it is part of your doctor's consultation.
If you want to ensure you're not out of pocket for these services, speak to your doctor to see if any specific items for health services are included as part of the Chronic Disease Management Plan.
If you want to access private hospital treatment - which can include choosing your own doctor and getting your own room - then bronze-level private health insurance is the minimum cover to consider. You'll find cover included under 'pain management'.
If you want comprehensive cover for chronic pain, you can consider gold-level hospital cover. Policies usually come with a 2-month waiting period, or 12 months if your chronic pain is a pre-existing condition.
Gold hospital health insurance provides benefits for a range of services related to chronic conditions. These may include:
With private health care, you might be able to receive care quicker as wait times for elective surgeries are often shorter than in the public system.
All prices are based on a single individual with less than $105,000 income and living in Sydney.
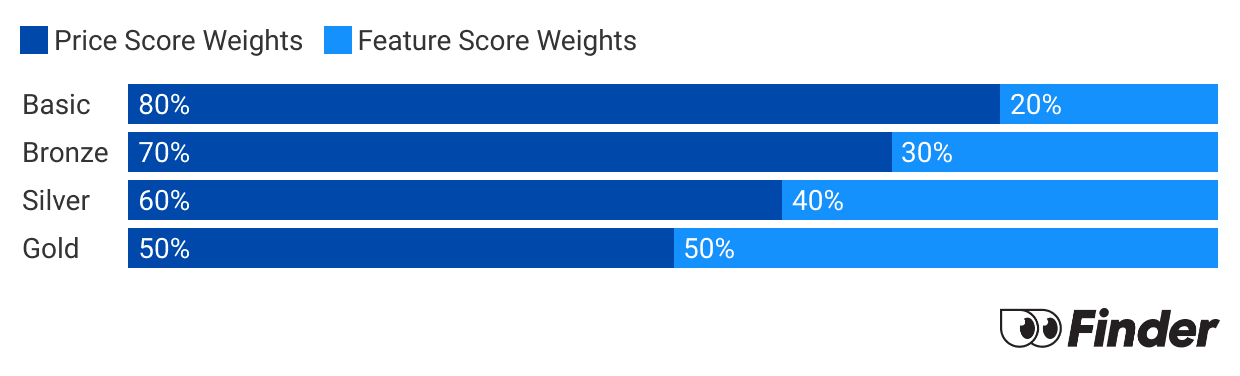
Each month we analyse our hospital insurance products and rate each one on price and features. What we end up with is a nice round number out of 10 that helps you compare hospital cover a bit faster.
Before we start scoring, we need to make sure we're comparing like-for-like. Just as it doesn't make sense to compare a bicycle with a Ferrari, it doesn't make sense to compare basic hospital policies to top-tier Gold policies. Each policy is given a price score and feature score. These are then combined to determine each policies's Finder Score.
Keep in mind that you'll probably need extras cover for chronic pain care done outside of hospital. While hospital cover helps pay for treatment and accommodation in a hospital during an illness or injury, extras cover helps cover the costs of ancillary health services you might need if you suffer from chronic pain.
Services like physiotherapy, remedial massage and natural therapies are included in extras cover and can be a really important part of chronic pain treatment.
Personal circumstances will dictate whether you feel you need extras on top of hospital cover. However, it's worth keeping in mind that if you don't have combined hospital and extras cover, you might be out of pocket for any care you receive outside of hospital.
Think you may have sleep apnoea? Here's what you need to know about public and private healthcare cover.
Doing a medical costs comparison could save you a lot of money. Here's how to reduce your out-of-pocket medical expenses.
Think you may need hernia surgery? See what's involved.
If you need knee surgery in Australia, see how private and public works and explore your options.
Think you may need hip surgery in the future? Compare your options for public and private treatment.
Medicare and private health insurance can work together to bring down the costs of your gender reassignment surgery.
Find out if being treated as an inpatient or an outpatient will affect your private health insurance cover.
Palliative care is the practice of easing the pain of a patient with a terminal illness and making them as comfortable as possible before death.
Find the answers to the most common questions about health cover excesses in this helpful guide.
Learn the pros and cons of private vs public health in this handy guide to the differences between public and private health insurance.