Looking for other options? Check out these similar products.
How we picked theseKey takeaways
- The lowest interest rate on the market in October is a variable rate of 5.79%.
- You could save $6,600 a year by switching from the average variable rate to 6.93%.
- The cheapest rate might not be the best loan: look out for fees and features, and remember you might end up with a higher rate if you want to borrow above 80% of the property value.
How to compare the cheapest home loan rates
You’d think it was as simple as looking at the lowest number in the table, right? Well, it can be. But there are some things to watch out for that could make your cheap home loan…not so cheap.
1. Ok yes, look at the rate
The starting point is to always look at the rate. The lower rate, the lower your repayments.
2. But then look at the fees
Some loans lure you in with a cheap attractive rate, but then you find it piles on a huge fee to apply and another fee to pay each month as well. Your cheap rate now costs you more per month than the slightly higher interest rate with no fees.
3. Then have a little glance at the comparison rate
Comparison rates are normally based on loans of $150,000 so they’re not always helpful. But if the comparison rate is much higher than the actual interest rate, you can bet there are other costs driving your repayments up.
4. Don't forget to look at the features
It’s all well and good getting a low interest rate but if you’re sacrificing access to features that could save you money in the long run, it’s not worth it. Take an offset account, for example. Using an offset account will mean you pay down the loan faster because it reduces the amount of interest you need to pay.
Is your rate the cheapest rate?
The lower the interest rate the lower the repayments
The number one factor in determining a cheaper home loan is a low interest rate.
Let's compare 2 otherwise identical home loans with slightly different interest rates.*
| Interest rate | 6.93% | 5.79% |
|---|---|---|
| Loan amount | $730,719 | $730,719 |
| Loan term | 30 years | 30 years |
| Monthly repayment | $4,950 | $4,400 |
| Monthly saving | N/A | $550 |
| Annual saving | N/A | $6,600 |
As you can see, with the lower interest rate, you save $550 a month – or $6,600< a year.
*We're using the average owner-occupier home loan size from the ABS, the average variable rate loan in Finder's database of the full market and the lowest variable rate available for refinancers.
How much can you save with a cheaper home loan?
We calculated this by using our loan repayment calculator. Try it out for yourself and see how much you could save.
What are the lowest home loan rates on the market?
Every month, we analyse the rates in our database to create a list of the market's cheapest loans.
The lowest variable interest rate in Finder’s database right now is 5.69%
The lowest fixed interest rate in Finder’s database right now is 5.79%
The cheapest rates over time.
Finder's lowest home loan rates
A graph showing 4 lines, for fixed and variable interest rates for investor and owner-occupier loans.
| Month | Variable (owner occupier) | Fixed (owner occupier) | Variable (investment) | Fixed (investment) |
|---|---|---|---|---|
| May-2018 | 3.49 | 3.69 | 3.79 | 3.89 |
| Jun-2018 | 3.52 | 3.69 | 3.79 | 3.89 |
| Jul-2018 | 3.49 | 3.69 | 3.79 | 3.89 |
| Aug-2018 | 3.54 | 3.74 | 3.93 | 3.84 |
| Sep-2018 | 3.49 | 3.74 | 3.89 | 3.84 |
| Oct-2018 | 3.54 | 3.74 | 3.79 | 3.84 |
| Nov-2018 | 3.54 | 3.74 | 3.79 | 3.84 |
| Dec-2018 | 3.49 | 3.69 | 3.74 | 3.84 |
| Jan-2019 | 3.49 | 3.74 | 3.74 | 3.89 |
| Feb-2019 | 3.49 | 3.74 | 3.74 | 3.84 |
| Mar-2019 | 3.49 | 3.74 | 3.74 | 3.84 |
| Apr-2019 | 3.48 | 3.74 | 3.91 | 3.84 |
| May-2019 | 3.48 | 3.59 | 3.74 | 3.69 |
| Jun-2019 | 3.24 | 3.39 | 3.69 | 3.69 |
| Jul-2019 | 2.89 | 3.19 | 3.49 | 3.39 |
| Aug-2019 | 2.89 | 2.98 | 3.29 | 3.09 |
| Sep-2019 | 2.89 | 2.74 | 3.19 | 3 |
| Oct-2019 | 2.69 | 2.74 | 2.99 | 3 |
| Nov-2019 | 2.69 | 2.68 | 2.99 | 2.84 |
| Dec-2019 | 2.69 | 2.68 | 2.99 | 2.84 |
| Jan-2020 | 2.69 | 2.68 | 2.99 | 2.84 |
| Feb-2020 | 2.69 | 2.68 | 2.99 | 2.84 |
| Mar-2020 | 2.49 | 2.68 | 2.79 | 2.84 |
| Apr-2020 | 2.44 | 2.09 | 2.79 | 2.39 |
| May-2020 | 2.39 | 2.09 | 2.79 | 2.29 |
| Jun-2020 | 2.39 | 2.09 | 2.79 | 2.34 |
| Jul-2020 | 2.19 | 1.99 | 2.79 | 2.34 |
| Aug-2020 | 1.99 | 1.99 | 2.74 | 2.29 |
| Sep-2020 | 1.99 | 1.98 | 2.59 | 2.29 |
| Oct-2020 | 1.99 | 1.9 | 2.59 | 2.29 |
| Nov-2020 | 1.99 | 1.98 | 2.64 | 2.29 |
| Dec-2020 | 1.99 | 1.89 | 2.33 | 1.99 |
| Jan-2021 | 1.99 | 1.88 | 2.33 | 1.99 |
| Feb-2021 | 1.99 | 1.88 | 2.33 | 1.99 |
| Mar-2021 | 1.99 | 1.69 | 2.33 | 1.99 |
| Apr-2021 | 1.95 | 1.69 | 2.24 | 1.99 |
| May-2021 | 1.95 | 1.69 | 2.24 | 1.99 |
| Jun-2021 | 1.9 | 1.67 | 2.24 | 1.99 |
| Jul-2021 | 1.89 | 1.67 | 2.24 | 1.89 |
| Aug-2021 | 1.89 | 1.69 | 2.32 | 1.99 |
| Sep-2021 | 1.85 | 1.69 | 2.32 | 1.99 |
| Oct-2021 | 1.85 | 1.59 | 2.24 | 1.89 |
| Nov-2021 | 1.85 | 1.59 | 2.24 | 1.89 |
| Dec-2021 | 1.77 | 1.59 | 2.24 | 1.89 |
| Jan-2022 | 1.85 | 1.79 | 2.17 | 2.14 |
| Feb-2022 | 1.77 | 1.79 | 2.14 | 1.99 |
| Mar-2022 | 1.77 | 1.84 | 1.99 | 1.99 |
| Apr-2022 | 1.79 | 1.84 | 1.99 | 1.99 |
| May-2022 | 1.79 | 1.84 | 2.14 | 2.39 |
| Jun-2022 | 2.04 | 2.09 | 2.39 | 2.69 |
| Jul-2022 | 2.44 | 2.59 | 2.79 | 3.59 |
| Aug-2022 | 3.05 | 3.59 | 3.24 | 3.99 |
| Sep-2022 | 3.14 | 3.99 | 3.59 | 4.29 |
| Oct-2022 | 3.54 | 4.19 | 3.84 | 4.19 |
| Nov-2022 | 3.44 | 4.49 | 4.19 | 4.59 |
| Dec-2022 | 4.29 | 4.6 | 4.57 | 4.84 |
| Jan-2023 | 4.29 | 4.64 | 4.59 | 4.79 |
| Feb-2023 | 4.39 | 4.94 | 4.64 | 5.09 |
| Mar-2023 | 4.64 | 4.99 | 4.97 | 5.19 |
| Apr-2023 | 4.64 | 4.99 | 5.14 | 4.99 |
| May-2023 | 4.64 | 4.99 | 5.14 | 4.99 |
| Jun-2023 | 5.34 | 5.24 | 5.29 | 5.44 |
| Jul-2023 | 5.39 | 5.23 | 5.89 | 5.56 |
| Aug-2023 | 5.39 | 5.23 | 5.79 | 5.53 |
| Sep-2023 | 5.39 | 5.48 | 5.79 | 5.54 |
| Oct-2023 | 5.39 | 5.48 | 5.74 | 5.56 |
| Nov-2023 | 5.59 | 5.48 | 5.74 | 5.56 |
| Dec-2023 | 5.74 | 5.48 | 5.69 | 5.58 |
| Jan-2024 | 5.69 | 5.48 | 5.69 | 5.58 |
| Feb-2024 | 5.69 | 5.48 | 5.69 | 5.58 |
| Mar-2024 | 5.69 | 5.48 | 5.69 | 5.58 |
| Apr-2024 | 5.69 | 5.48 | 5.94 | 5.58 |
| May-2024 | 5.69 | 5.48 | 5.94 | 5.58 |
| Jun-2024 | 5.69 | 5.48 | 5.94 | 5.58 |
| Jul-2024 | 5.69 | 5.48 | 5.94 | 5.58 |
| Aug-2024 | 5.69 | 5.59 | 5.94 | 5.69 |
| Sep-2024 | 5.69 | 5.59 | 5.94 | 5.69 |
| Oct-2024 | 5.69 | 4.99 | 5.94 | 4.99 |
| Nov-2024 | 5.69 | 4.99 | 5.94 | 4.99 |
| Dec-2024 | 5.69 | 4.99 | 5.94 | 4.99 |
| Jan-2025 | 5.69 | 4.99 | 5.94 | 4.99 |
| Feb-2025 | 5.38 | 4.99 | 5.54 | 4.99 |
| Mar-2025 | 5.44 | 4.99 | 5.84 | 5.29 |
| Apr-2025 | 5.64 | 4.99 | 5.79 | 5.29 |
| May-2025 | 5.59 | 4.99 | 5.79 | 4.99 |
| Jun-2025 | 5.34 | 4.99 | 5.59 | 4.99 |
| Jul-2025 | 5.34 | 4.99 | 5.59 | 4.99 |
| Aug-2025 | 5.34 | 4.94 | 5.59 | 4.99 |
| Sep-2025 | 5.09 | 4.64 | 5.34 | 4.89 |
| Oct-2025 | 4.99 | 4.64 | 5.34 | 4.69 |
| Nov-2025 | 4.99 | 4.64 | 4.99 | 4.69 |
| Dec-2025 | 4.99 | 4.64 | 5.34 | 4.74 |
| Jan-2026 | 4.99 | 4.79 | 5.29 | 4.99 |
| Feb-2026 | 4.99 | 4.94 | 5.29 | 4.99 |
| Mar-2026 | 5.1 | 5.2 | 5.35 | 5.2 |
| Apr-2026 | 5.19 | 5.49 | 5.35 | 5.59 |
| May-2026 | 5.35 | 5.7 | 5.6 | 5.7 |
| Jun-2026 | 5.69 | 5.99 | 5.85 | 5.99 |
| Jul-2026 | 5.14 | 5.99 | 5.85 | 5.99 |
| Aug-2026 | 5.69 | 5.99 | 5.85 | 5.99 |
| Sep-2026 | 5.69 | 5.79 | 5.94 | 5.89 |
| Oct-2026 | 5.79 | 5.79 | 5.94 | 5.89 |
-
Every month, we find the lowest home loan rates in our database for 4 different loan types. To ensure these products are not overly restrictive in eligibility criteria, every loan we select must meet the following criteria:
- Loans must be principal and interest loans with a maximum LVR of 80%, meaning you need a minimum 20% deposit.
- Fixed rates have terms of between 1 and 5 years.
- Mortgages are taken from Finder's database, with rates correct at the time of publication (updated every month).
What are the cheapest home loans at the big 4 in October 2026?
Interest rates can change depending on your circumstances, but as a guide, here are the cheapest home loans from the big 4.
| Bank | Cheapest Fixed Rate | Cheapest Variable Rate |
|---|---|---|
| ANZ | 6.69% | 6.5% |
| CBA | 6.78% | 6.34% |
| NAB | 6.79% | 6.69% |
| Westpac | 6.74% | 6.64% |
"I wanted to make sure I have one of the cheapest home loans on the market. So I found an online lender with a consistently low interest rate (I should know, I check rates every month). But I also made the sure the loan had an offset account. For me, being able to build up savings in the offset account speeds up my loan and cuts down my overall interest charges dramatically. This makes the loan much cheaper in the long run."
What to look for in a cheap home loan
At a very basic level, the cheapest home loan is the one with the lowest rate. But every borrower has different needs. So beyond a low rate, you need to get a loan that actually helps you achieve your property goals and financial needs.
A loan you can pay off ASAP
Home loans are normally taken out for 30 years, but the sooner you can repay the more you'll save! Most variable rate home loans allow you to make extra repayments and pay the loan early.
Fixed rate loans are less likely to allow extra repayments and will probably charge a break fee if you do repay early.
A loan that matches your strategy
The cheapest home loans are likely owner-occupier loans, but if you're buying an investment property they won't help you. You might also want an interest-only loan for the tax benefits if you're an investor.
A loan with an offset account
The money you'll save by using an offset account may very well mean you end up paying less than if you went for a lower rate without an offset account. Check out our guide on offset accounts to see if it could help you.
"If I had to credit just one thing with helping me repay my home loan in just 7 years, I'd say it was an offset account. This is a debt-busting secret weapon. You should keep every cent to your name in one of these – we're talking your savings for everything, your emergency cash stash and even your salary. You'll likely save tens of thousands of dollars and shave years off your time in debt."
3 extra tips to help you save money on your home loan
1. Choose your loan term carefully
Most borrowers choose 30-year loan terms.
If you picked a shorter loan term your monthly repayments would be higher, but you'd pay off your loan 5 years earlier, saving thousands in interest.
Let's look at 3 examples where the loan term changes:
| Loan term | 30 years | 25 years | 20 years |
|---|---|---|---|
| Interest rate | 6.25% | 6.25% | 6.25% |
| Loan amount | $600,000 | $600,000 | $600,000 |
| Monthly repayment | $3,694 | $3,958 | $4,386 |
| Total cost* | $1,329,949 | $1,187,405 | $1,052,537 |
*Total cost here refers to the amount of interest you pay over the life of the loan, plus the principal.
2. Find a loan with lower fees
Some lenders charge multiple loan fees that can add up to hundreds of dollars. But other lenders charge basically no fees at all (you still have to pay government fees like a mortgage registration fee).
If 2 loans have identical interest rates and features, the one with fewer fees will be the cheapest home loan.
3. Save a bigger deposit
Easier said than done, of course. But saving a bigger deposit means borrowing less money. And that instantly makes your home loan cheaper.
It saves you money in other ways too:
- You can avoid lenders mortgage insurance. LMI is paid if you have less than a 20% deposit.
- You can unlock lower rates. Many lenders offer lower interest rates for borrowers with a deposit of 20% or more.
Watch: How to find a lower home loan rate
Why you can trust Finder's home loan experts
Let us do the talking - we spoke to heaps of experts, brokers, banks and real humans to put 20+ hours into this guide. Our editors regularly talk to buyers, refinancers, investors and every one in-between to keep this information useful.
Rates obsessed - We track big banks, small banks, credit unions and digital banks because even 1 decimal place could save you big bucks (without getting annoying calls!).
Ready when you need it - Lending rates verified from 180+ products day and night. Whether you've remembered you need to refinance at 3am or live at an auction - our rates are up-to-date.
Frequently asked questions about getting a cheap home loan
-
Some of the market's cheapest home loans come in the form of special discount rate offers. These loans offer a cheap rate to entice you in but revert to a higher rate after a year or two.
Let's be clear, there's nothing bad about these deals. A low rate is a low rate. You just need to pay attention to the interest rate once the discount period ends and refinance to a better loan if your new rate jumps up. But every borrower needs to watch their rate, as lenders do move rates up and down (or keep you on your current rate while offering cheaper home loans to new customers!).
Also look at discharge or exit fees. You don't want to get hit with a big fee when trying to exit the loan later (although a small fee isn't so bad if the rate is very competitive).
-
Over the last couple of years, variable rates have typically been a little higher than fixed rates. But things are changing. Right now, variable rate loans are becoming lower than fixed rate loans. This is because the RBA held the cash rate at 4.35% in August 2026, but further rate rises are still possible. With hikes still on the table, it's more tempting to lock in a fixed interest rate to avoid future rate rises, so lenders are pricing fixed rates higher than variable rates accordingly.
Read more in our guide on the difference between fixed and variable rates.
-
Online lenders, fintechs and small digital banks tend to have cheaper home loan rates than bigger banks. If you're not comparing rates from these lenders, you might miss some of the best deals on the market.
Mortgage brokers are great at helping you find a home loan and handling mortgage paperwork. But they often don't have small online lenders in their panel of lenders, so you might miss out on a very low rate.
-
It's a myth that the Big Four always have much higher rates, but they are often higher than the best deals out there. But it's a very competitive market. There's often not much difference between a hot online deal and a big bank's lowest variable rate.
Many of the cheapest loans among Finder's partners (and the wider market) are from smaller banks and local credit unions. But banks are changing their rates and policies constantly, and the Big 4 can be low as well. This is why you really have to compare as many lenders as you can.
-
Some lenders offer special loans tailored to first home buyers that are worth checking out. You can use our comprehensive guide to learn more about getting a loan as a first home buyer.
And don't forget about first home buyers' grants offered by many state and territory governments.
-
Mortgage brokers compare loans for you and are experts at helping borrowers find appropriate products. If you're confused or need help, a broker can be very useful.
But you should also know that many of the market's lowest rates (including many listed on this page) are offered by small lenders that don't appear in a mortgage broker's panel. If the lender isn't in the broker's panel, they cannot help you.
But brokers are helpful for other reasons, and if you have more concerns than just finding the absolute lowest rate, then speaking to a mortgage broker is a good idea. Just do your own research as well.
-
Saving up for your home loan deposit is a serious challenge for everyone. However, there are ways to trim your expenses, build your deposit and find home loans that don't need large deposits. To master the art of saving for a home loan deposit, you should look at our in-depth, 6-part guide to home loan deposits.
-
You should always be comfortable with the lender you're planning on going with. If you're not aware of a lender, try calling it to find out about the company and its service level before lodging an application. Speak to previous customers or read customer reviews online.
Keep in mind that little-known lenders might be funded by a larger bank, as is the case with NAB-backed UBank or Firstmac-backed loans.com.au.
What is Finder Score?
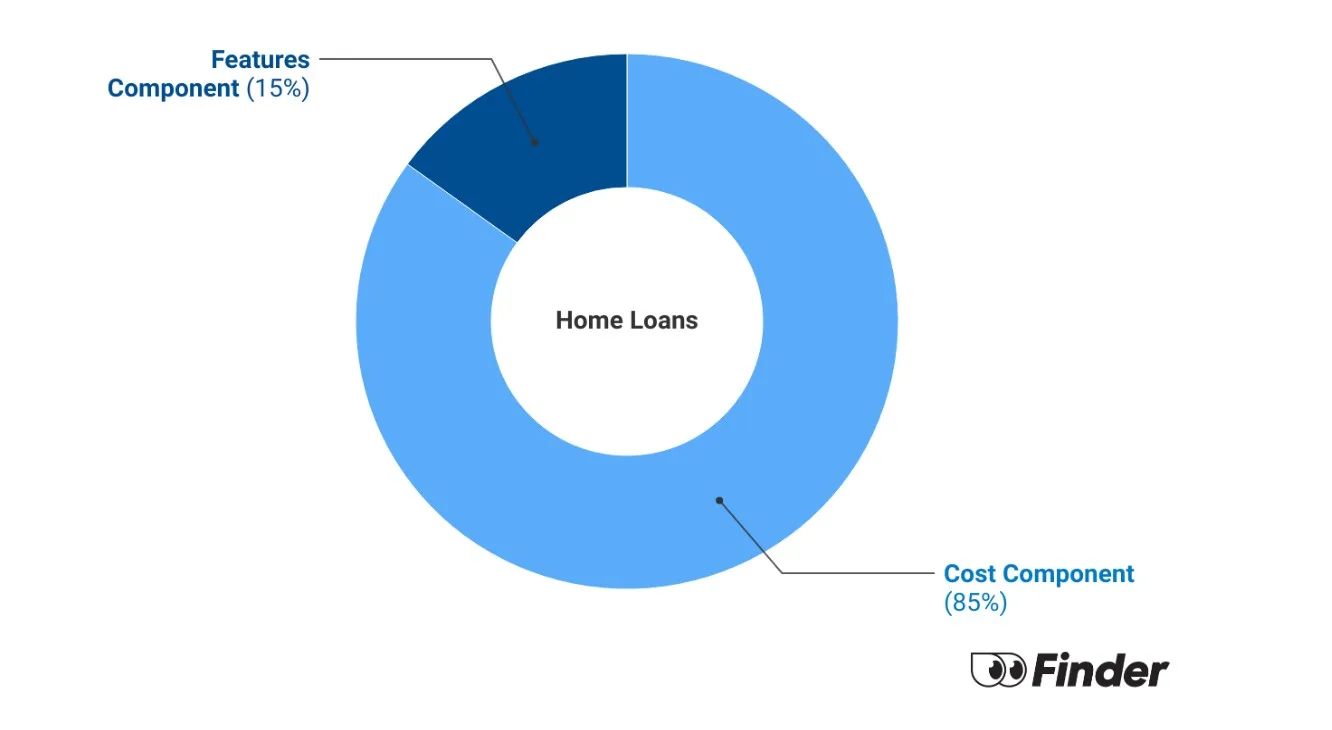
The Finder Score crunches 7,000 home loans across 120+ lenders. It takes into account the product's interest rate, fees and features, as well as the type of loan eg investor, variable, fixed rate - this gives you a simple score out of 10.
To provide a Score, we compare like-for-like loans. So if you're comparing the best home loans for cashback, you can see how each home loan stacks up against other home loans with the same borrower type, rate type and repayment type. We also take into consideration the amount of cashback offered when calculating the Score so you can tell if it's really worth it.
Sources
Richard Whitten is Finder’s Senior Money Editor, with over eight years of experience in home loans, property, credit cards and personal finance. His insights appear in top media outlets like Yahoo Finance, Money Magazine, and the Herald Sun, and he frequently offers expert commentary on television and radio, helping Australians navigate mortgages and property ownership. Richard started his career in education and textbook publishing in South Korea. He holds multiple industry certifications, including a Certificate IV in Mortgage Broking (RG 206) and Tier 1 and Tier 2 certifications (RG 146), as well as a Bachelor of Education from the University of Sydney and a Graduate Certificate in Communications from Deakin University. See full bio
- Home loans
- Credit cards
- Personal finance
- Money-saving tips
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
More guides on Finder
-
A guide for first home buyers
Use our complete first home buyer guide to make your first home purchase as stress-free as possible.
-
Digital and neobank home loans
Learn about the neobanks and digital challengers offering new, innovative home loans in Australia.
-
Big Four bank home loans – current rates and offers
Compare some of the home loans that are offered by Australia's Big Four banks.
-
How to negotiate a lower interest rate on your mortgage
Negotiate a better home loan rate with these tips and save on your repayments as well as thousands of dollars in interest over the course of your loan.
-
What is a mortgage discharge fee?
Here's everything you need to know about fees when exiting a home loan.
-
BankSA home loans
The largest financial institution in South Australia, BankSA offers an extensive range of financial products and services.
-
ING home loans
Thinking about getting a home loan from ING? Compare rates and learn more about this lender.
-
Lenders mortgage insurance (LMI)
Lender's mortgage insurance is the upfront charge that you pay when you borrow over 80% of your property's purchase price.
-
Best home loans with offset accounts
What is an offset account? It can save you thousands in interest and help you own your home sooner.