Expat income protection insurance
Will income protection cover you if you're working overseas?
Yes, many policies can. To be eligible for income protection while working overseas, you will generally need to do one of the following:
| Response | |
|---|---|
| I've never lied on an insurance policy | 93.6% |
| I lied on my current policy | 4% |
| I've lied on a past policy | 2.4% |
| Provider | Conditions |
|---|---|
 AIA Income Protection | If you travel overseas, AIA's income protection policy covers you 24 hours a day, seven days a week, anywhere in the world. You will need to inform the insurer of your travel plans when you apply for cover as this may alter the cost of your premiums. |
 RAC Disability Income Insurance | Once issued, insurance cover is provided worldwide and 24-hours a day, subject to any special terms and conditions we may apply to your cover. |
 AMP Elevate Income Insurance | When you are accepted for cover, AMP will offer insurance protection 24 hours a day, seven days a week, anywhere in the world. However, if you fall ill or are injured outside Australia or New Zealand, you may need to provide additional medical documentation and/or undergo an additional medical examination by a medical practitioner chosen by AMP. |
 Asteron Income Protection | When you apply for cover, you'll need to provide details about your travel plans, including your destinations and the purpose of your trip(s). 24/7 worldwide cover is available from Asteron, although special loadings and exclusions may apply to cover. |
 BT - Income Protection | BT income protection cover offers protection anywhere in the world all year round. However, special loadings and exclusions may apply to cover. |
 ClearView LifeSolutions Income Protection Cover | Unless the policyholder and the insurer agree on special cover terms at the time of application, ClearView offers income protection cover anywhere in the world. |
 CommBank Income Protection | Cover is provided 24 hours a day, seven days a week, anywhere in the world. However, specific exclusions may be applied to your policy for injuries sustained in certain countries, or specific circumstances (eg, terrorism) in certain countries that could lead to an injury. |
 Acenda Income Protection Insurance | When applying for cover, you'll need to provide details about your travel plans including your destinations, duration of trips and purpose of travel. Cover is offered 24 hours a day all around the world, but specific exclusion and loadings may be applied depending on where you are planning on visiting. |
 OnePath OneCare Income Secure Cover | OnePath offers protection 365 days a year anywhere in the world, subject to any specific terms and exclusions which may apply to your policy. |
 TAL Accelerated Protection - Income Protection Insurance | TAL offers a maximum benefit period of 90 days if you reside outside of Australia. Depending on your circumstances, exclusions and premium loadings may apply. |
 Zurich Income Replacement Insurance | Zurich Wealth Protection policies provide cover all year long, all around the world. However, if you are claiming income replacement benefits you will need to have a medical examination every 12 months in order to continue receiving benefits. |
With so many Australians working overseas in industries such as oil, gas and mining, there are plenty of insurance companies happy to cover Australians working abroad for periods at a time. The main requirement is that you can show you intend to return within three to five years.
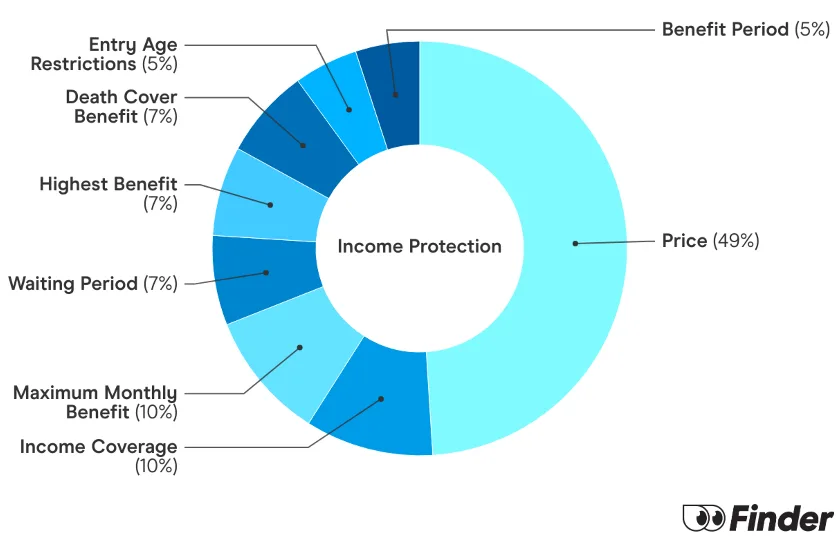
Income Protection is a little complicated and a lot overwhelming. That's why we made the Finder Score, to make it easier to compare Life Insurance products against each other. Our experts analysed over 21 products and gave each one a score rank out of 10, to make it easier to compare Income Protection products against each other.
But a higher score doesn't always mean a product is better for you. Your situation is unique, so your policy choice will be too. Don't think of Finder Score as the final word, but as a good place to start your life insurance comparison.
Yes, life insurance can cover you while you are overseas. Here's a breakdown of how it works:
Unlike income protection, it's possible to get Australian life insurance cover even if you don't plan on returning. There may be some more cover restrictions and your premiums might be higher, especially if you're in a country the Australian government considers dangerous, but you'll be covered as long as you continue to pay your premiums.
Insurers may require total and permanent disability insurance policies to be modified so that you have to return to Australia within a certain period of time after being unable to work. This clause is usually inserted so that you can receive treatment to Australian standards.
You should also be able to get trauma insurance if you're living overseas. Keep in mind though that if you're residing in a dangerous area or working in a dangerous job, you might not be able to get cover.
If you plan to go overseas for a significant period of time, then you need to let your insurer know. This is because it won't have factored the added risks of being overseas into your cover. As a result, you risk not being covered if something happens.
When you let your insurer know that you're going to be overseas, it's likely to raise your premiums to account for the added risk (and the potential cost of repatriation) and it may introduce specific conditions where you won't be covered.
How much could you save if you lived in a different city in Australia? Let's find out.
Income protection can be a valuable form of cover for Australians when its features are fully understood.
Find out what is and isn't covered by AAMI Income Protection and how to apply.
Income protection for couples ensures your partner isn't hurt financially if you are temporarily unable to work due to illness or injury.
Find out why income protection is still useful if you're over 60, and compare cover.
Salary continuance and income protection both serve to replace income in the event of injuries and illness. However, there are some key differences to know about.
Receive income cover for illness or injury with Suncorp Income Protection.
Life insurance and income protection serve two different purposes but can both offer valuable cover alone and when combined.
Find out how much your income protection insurance policy will pay out in the event of a claim. Receive quotes for income protection and apply securely.
Looking for the best income protection insurance but not exactly sure where to start? Compare the Finder Awards 2025 insurance winners.