Is income protection insurance tax-deductible?
Income protection insurance is tax deductible in most cases, but there's a few quirks to be aware of.
If you've bought a standalone income protection insurance policy, then you could get some money back on your annual tax return. Under Australian Taxation Office (ATO) rules, you're allowed to claim the cost of premiums you pay for insurance against the loss of your income, but note:
The ATO states that you won't be able to claim a deduction for any part of a premium if:
Income protection is all about insuring your earnings. So, you can't claim any tax benefits that are not deemed to be replacing income. This rules out claims on many life insurances that tend to pay out 'lump sum' benefits after certain events, like trauma insurance, critical illness insurance or TPD cover.
| Response | Male | Female |
|---|---|---|
| Yes | 7.98% | 6.15% |
| No | 4.45% | 4.04% |
For income protection that's held in your superannuation, the super fund is essentially the owner of the policy and so it's not something you would be able to claim tax against. That said, you may be entitled to receive a tax deduction if you are self-employed.
Ultimately, whether or not you can get a tax deduction will depend on your specific circumstances. That's why it's a good idea to seek professional advice from a qualified tax consultant.
This depends on your annual earnings and marginal tax rate. Consider the examples below for a policy that costs $800 p.a.
| Policyholder's annual earnings | Annual premium to insurer | Marginal tax rate | Tax refund | Final cost of cover |
|---|---|---|---|---|
| Over $190,000 | $800 | 45% | $360 | $440 |
| Between $135,001 and $190,000 | $800 | 37% | $296 | $504 |
| Between $45,001 and $135,000 | $800 | 30% | $240 | $560 |
| Taxable income | Tax on this income |
|---|---|
| 0 – $18,200 | Nil |
| $18,201 – $45,000 | 16 cents for each $1 over $18,200 |
| $45,001 – $135,000 | $4,288 plus 30c for each $1 over $45,000 |
| $135,001 – $180,000 | $31,288 plus 37c for each $1 over $135,000 |
| $190,001 and over | $51,638 plus 45c for each $1 over $190,000 |
| Taxable income | Tax on this income |
|---|---|
| 0 – $135,000 | 30 cents for each $1 |
| $135,001 – $190,000 | $40,500 plus 37 cents for each $1 over $120,000 |
| $190,001 and over | $61,850 plus 45 cents for each $1 over $180,000 |
Source: ATO
When it's time to complete your tax return, you'll be able to enter any claimable amount of your premium as a work tax deduction. This can usually be found in the "Other deductions" category of your return.
Your income protection provider should send you a tax statement annually. You could ask your insurer to send you one if you've not received a form in the run up to the end of the financial year.
Also, if you prepay your income protection before 30 June, you can claim your tax deduction in the current financial year, e.g. you pay 12 months of premium in advance to receive a tax deduction.
"I was diagnosed with cancer when I was 37. I was very fortunate that my road to recovery was quick and straightforward and my employer was great about giving me time off and holding my job for me during treatment. But my income protection policy and later my critical illness policy were a genuine lifeline – the money they provided meant we didn't need to stress about money, and could fully concentrate on my health."
| Question | Answer | Conditions |
|---|---|---|
| Are income protection insurance premiums tax-deductible? | Yes | Provided the benefit is paid in regular instalments replacing a regular income, and the policy is not held inside super. |
| Are benefits paid under an income protection policy taxable? | Yes | The benefit payments are treated as income by the Australian Taxation Office and are therefore taxable. |
| Do I pay GST on income protection premium costs? | No | GST is only payable on fire and general types of insurance, but not with this type of life insurance. |
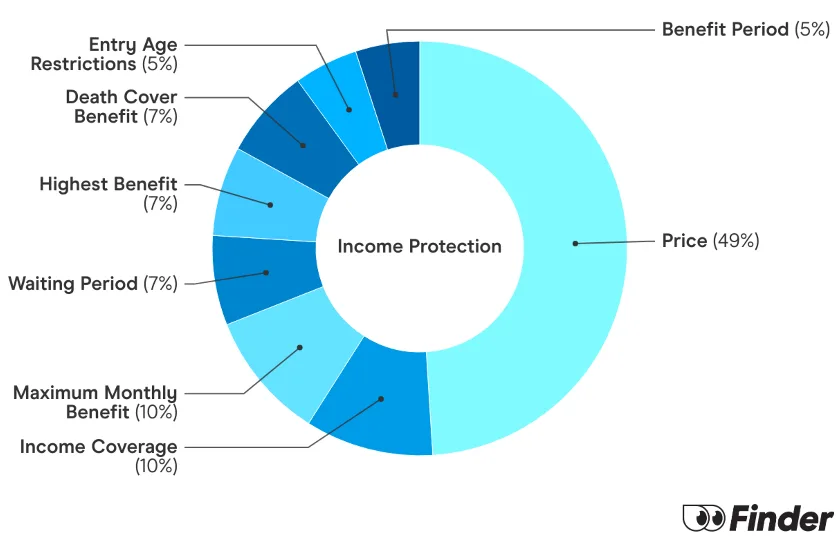
Income Protection is a little complicated and a lot overwhelming. That's why we made the Finder Score, to make it easier to compare Life Insurance products against each other. Our experts analysed over 21 products and gave each one a score rank out of 10, to make it easier to compare Income Protection products against each other.
But a higher score doesn't always mean a product is better for you. Your situation is unique, so your policy choice will be too. Don't think of Finder Score as the final word, but as a good place to start your life insurance comparison.
Real Income Protection Insurance has similar cover to many popular providers. However, optional extras are limited.
How much could you save if you lived in a different city in Australia? Let's find out.
Cover up to 85% of your salary with one of Aspect's flexible income protection policies.
Learn the built-in benefits of TAL income protection to understand how it could work for you. Compare features and get a quote today.
Find out why income protection is an important tool to combine with your entitled sick leave.
Find out how you can benefit from income protection even if you have a pre-existing condition, and which providers will cover you.
Receive income cover for illness or injury with Suncorp Income Protection.
Most providers no longer offer unemployment insurance in Australia if you're made redundant.
Rest Super has grown to become one of Australia's largest super funds with a range of protection options for members including life cover, TPD cover and long term income protection.
Looking for the best income protection insurance but not exactly sure where to start? Compare the Finder Awards 2025 insurance winners.