Key takeaways
- It'll make your premium more expensive, but you do need to tell your insurer if you're a smoker.
- Lying on your policy could result in claims being denied.
- If you've recently quit smoking, you may be able to update your policy.
How could an insurance company know if I smoked?
In the event of a claim on a life policy, the insurer will assess the policyholder's claim eligibility and verify the accuracy of the details provided in the application.
There are a few different ways an insurer can find out if you smoke:
- It can undertake medical tests to verify if you're a smoker in the event of a claim.
- It can run a verification process that can involve reviewing your Medicare and PBS (Pharmaceutical Benefits Scheme) records.
- It can contact the GP you had at the time of your application for more details.
If a policyholder has hidden the fact that they smoke, the insurance provider is entitled to refuse, or at best pay a smaller amount on, any claim made. This could come about, for example, if a coroner's report states that your death was linked to a smoking-related illness.
Your duty of disclosure when applying for life insurance
Regardless of the type of insurance being applied for, each applicant is required to answer each question in their application as truthfully as possible.
Under the Insurance Contracts Act of 1984, before entering into the insurance contract, applicants have a duty to disclose every matter that is known to be relevant to the decision of whether the company will accept the potential risk that they carry.
What questions will the insurer ask? Questions relating to your health, including your history of smoking. It's crucial that you answer these questions accurately so that the policy you're offered is valid.
So, you must admit to smoking, even if you do so only from time to time. In this context, smoking is defined as anything that contains nicotine such as cigarettes, chewing tobacco, vapes, e-cigarettes and patches.
Can I get an adjustment of my life insurance premium if I quit smoking?
Most life insurance providers will treat applicants as non-smokers if they have quit smoking 12 months before the application has been submitted. You could be asked to take a medical exam. This may involve a blood test for nicotine.
If you initially took out life insurance as a smoker and became a non-smoker further into your policy, it might be possible to have your premium adjusted to reflect a non-smoker status. An underwriter may investigate reasons for you stopping. For example, you may have been told to quit on medical advice after developing a smoking-related condition. If so, you may be required to provide medical evidence to the insurer.
Check your superfund for cover – another option for smokers
If your super fund offers life insurance, there's a good chance you're covered as a group (not as an individual). This means you may already have cover without smoking status being a factor. But keep in mind that holding insurance within your super does generally offer less generous benefits overall.
You may want to speak with a representative from your super fund to see what the rules are around life insurance when starting a new job or increasing the amount you are covered for.
How do life insurance rates compare for smokers and non-smokers?
Life insurance applicants that smoke can expect to pay hundreds of dollars more in life insurance premiums compared to those that don't smoke.
Non-smoker vs smoker
| Non-smoker | ||
|---|---|---|
| Ages | 25, 35, 45, 55 | 25, 35, 45, 55 |
| State | NSW | NSW |
| Occupation | Accountant (Not qualified) | Accountant (Not qualified) |
| Cover | $500,000 | $500,000 |
| Premium per year | $687.761 | $1566.48 |
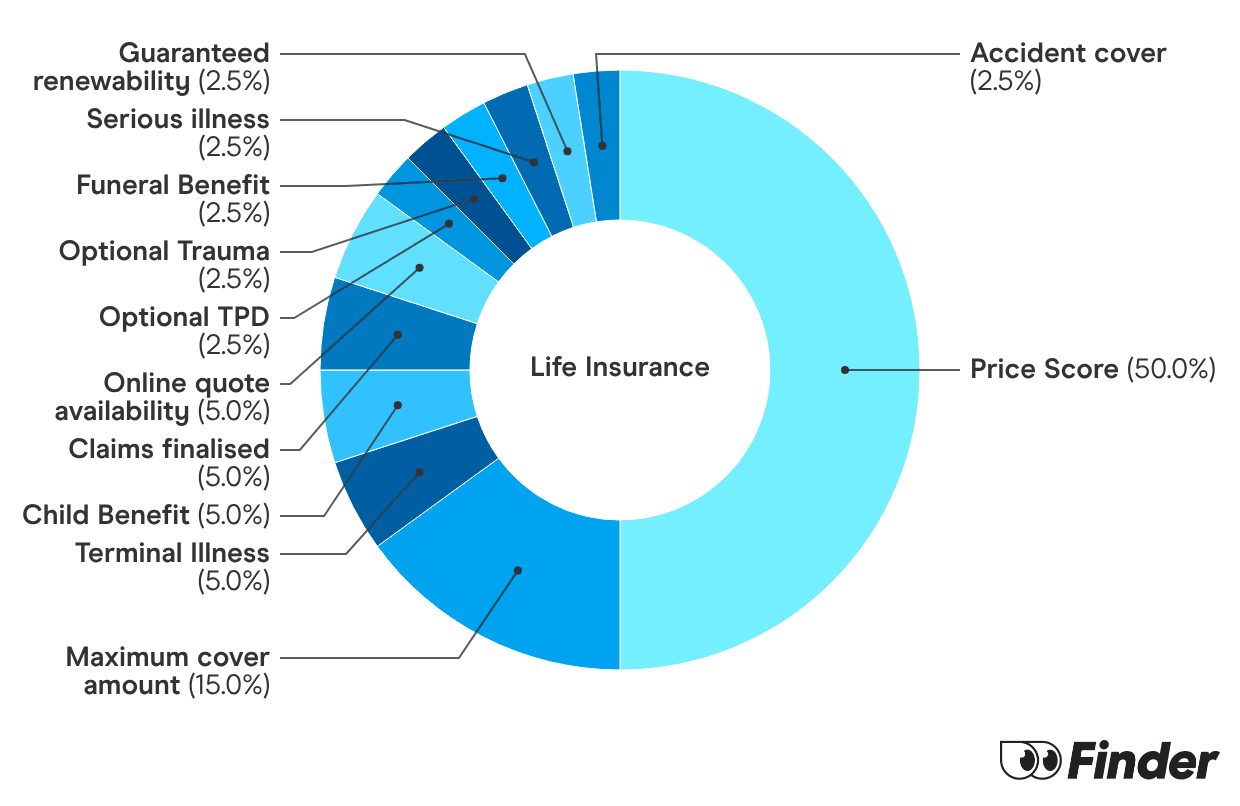
Quotes taken from research for the 2026 Finder Awards, the methodology of which can be read here. The prices above show the average cost for quotes with TAL across 4 age groups. Prices are indicative – what you pay will be based on your specific circumstances.
So, how can I get competitively priced life cover?
Whether someone smokes is by no means a reason to be deterred from taking out life insurance. If anything, it gives more reason to do so.
While all life insurance companies will charge a premium loading for people that smoke, there are a couple of ways to get affordable cover. Either compare some of the best providers with our simple comparison tool, or speak to an insurance specialist today.
Why compare insurance with Finder?
-
You pay the same price as buying directly from the insurer.
-
We're not owned by an insurer (unlike other comparison sites).
-
We've done 100+ hours of policy research to help you understand what you're comparing.
Frequently asked questions
-
Yes, you can still get life insurance if you are a smoker but you can expect to pay a higher insurance premium compared to a non-smoker.
-
To be considered a 'non-smoker' for life insurance, you'll usually need to be free of any smoking products for at least 12 months.
-
An insurer may not confirm your smoking status at the time of application but will when you make a claim. They can do this by requesting a medical test, reviewing your Medicare and PBS records or by contacting your current and past GPs.
-
You risk voiding your cover if you don't declare that you are a smoker to your life insurance provider. The insurer can then refuse to pay out if you or your beneficiaries make a claim.
-
Yes. Most life insurance providers consider e-cigarettes and vapes that contain nicotine to be the same as smoking cigarettes.
-
Finder writers are subject matter experts and use primary sources, in-depth research and interviews with other experts to ensure you're getting accurate, up-to-date information. Articles are fact checked in line with our editorial guidelines.
- NobleOak Life Insurance PDS (accessed February 2025)
- Medibank Life Insurance PDS (accessed February 2025)
- TAL Accelerated Protection Life Insurance PDS (accessed February 2025)
- ahm Life Insurance PDS (accessed February 2025)
- RAC Life Insurance PDS (accessed February 2025)
- AAMI Life Insurance PDS (accessed February 2025)
- Suncorp Life Insurance PDS (accessed February 2025)
- Real Family Life Cover PDS (accessed February 2025)
- Finder survey by Pure Profile of 1110 Australians
James Martin was the insurance editor at Finder. He has written on a range of insurance and finance topics for over 7 years. James often shares his insurance expertise as a media spokesperson and has appeared on Prime 7 News, Insurance News, 7NEWS and The Guardian. An experienced journalist, James' work has featured in publications including The Irish Times, Companies100 and In Business. He holds a Tier 1 General Insurance (General Advice) certification and a Tier 1 Generic Knowledge certification, both of which meet the requirements of ASIC Regulatory Guide 146 (RG146). See full bio
- Car, home, life, health, travel and pet insurance
- Managing the cost of living
- Money-saving tips
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
More guides on Finder
-
Why are women charged more than men for income protection?
Financial literacy advocate Pascale Helyar-Moray on what women do to avoid losing out to higher costs.
-
Denied life insurance? What’s next?
Was your life insurance application denied? This article looks at the top reasons why your application might have been denied and what you can do to get the right cover.
-
Life insurance underwriting
Find out how the underwriting process actually works if considering taking out cover.
-
Life insurance for smokers
Ever wondered how much more life insurance for smokers costs in Australia? Learn about how smoking and vaping can impact your policy.
-
What is life insurance?
Not sure what life insurance is? We take you through the basics of life insurance with our easy to understand guide.
-
Life insurance beneficiary rules Australia
Read our guide to updating life insurance beneficiaries and making sure your money goes to the right people.
-
No Medical Life Insurance
Depending on the applicant and the type of life insurance policy, there may be no medical tests required.
-
Variable age-stepped premiums vs variable premiums
finder's guide to choosing between variable age-stepped and variable insurance premiums.