Key takeaways
- If is possible to have multiple life insurance policies, and they should both pay out. With a few exceptions.
- More commonly, you could have multiple types of life cover, such as trauma insurance or income protection.
- Having multiple policies can be a really sensible idea if you have a distinct cost you want to cover, like a mortgage or business.
Compare life insurance options in Australia
You can get life insurance coverage that protects you for a number of life-changing circumstances, from income protection to death cover. If you have more than one valuable asset in your life, it may make sense to have more than one policy. You can filter below by policies and features to find coverage that suits you.
Looking for other options? Check out these similar products.
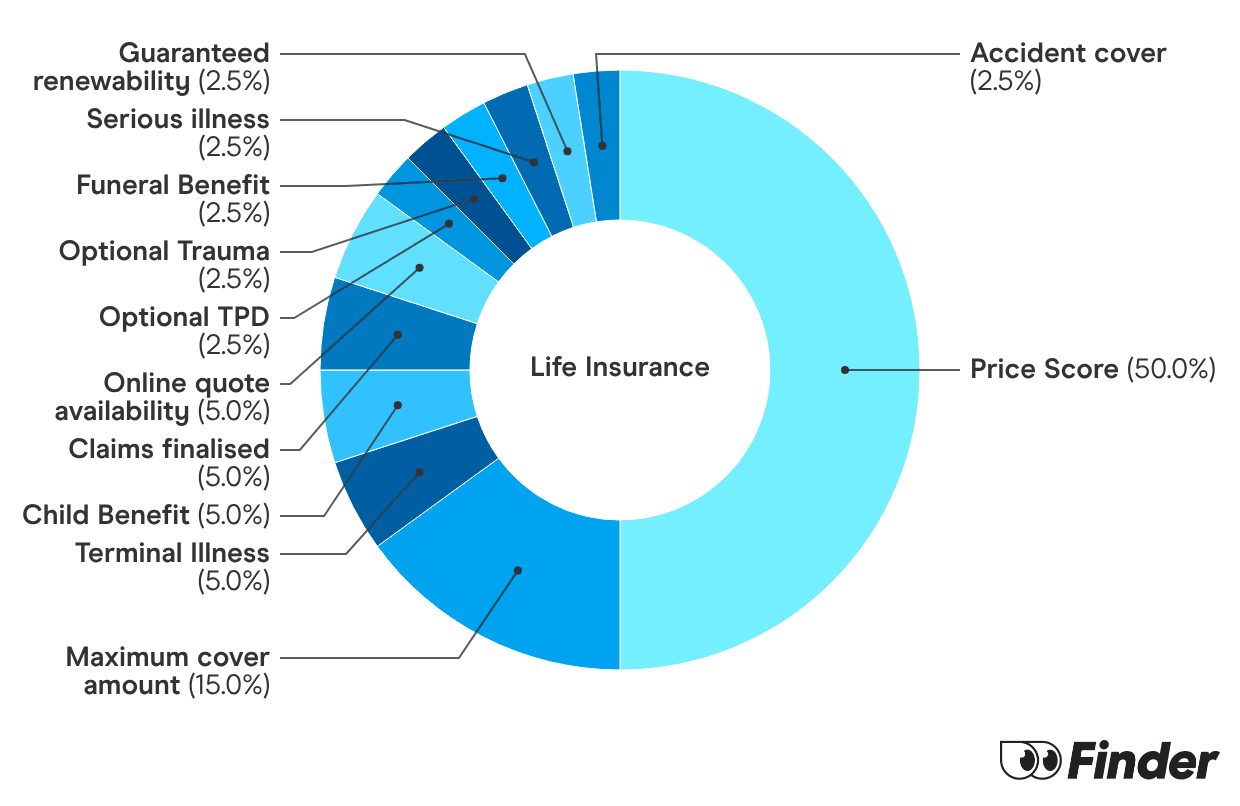
How we picked theseFinder Score - Life Insurance
Life Insurance is a little complicated and a lot overwhelming. That's why we made the Finder Score, to make it easier to compare Life Insurance products against each other. Our experts analysed over 30 products and gave each one a score out of 10.
But a higher score doesn't always mean a product is better for you. Your situation is unique, so your policy choice will be too. Don't think of Finder Score as the final word, but as a good place to start your life insurance comparison.
Insurance types to choose from
- Life insurance. Also known as death cover, life cover is paid out if you pass away or become terminally ill. It gives a lump-sum payment to your nominated beneficiaries.
- Total permanent disability (TPD). TPD cover pays out a lump sum if you become permanently disabled, protecting you financially if you can't work again.
- Trauma cover. If you suffer an injury or illness, trauma cover provides you with a lump sum to help cover short-term expenses like medical bills.
- Income protection. If you need to temporarily stop work due to illness or injury, income protection gives you a monthly payment of up to 75% of your income for a fixed period of time.
Why you might take out more than one life insurance policy
There are a number of reasons you might have multiple life insurance policies. Some of the main reasons are listed below.
- Personal cover. Insurance can protect you and your family from financial hardship in the event of your death or injury.
- Life insurance through superannuation. Most Australian superannuation funds will provide policyholders with some level of default life cover. However, these policies generally only provide a limited level of cover. For more comprehensive coverage, many people take out an additional standalone policy.
- Business cover. If you operate your own business, you might need a policy to protect the key workers in your business or to ensure business expenses are covered if you're unable to work due to illness or injury.
- Lifestyle changes. Whether it's the birth of a new baby or upgrading your house, it can sometimes be more beneficial to take out an additional policy with benefits tailored to your new needs, rather than increase your sum insured.
How many insurance policies can I have?
There's no limit, but you don't want to be over-insured, so it's important you know exactly what each policy does. For example, if you have a group policy in your super fund and another policy with additional types of cover, like trauma cover, that is acceptable. Both should pay out.
Some policies have built-in offset clauses though. For instance, with income protection policies, you can generally only insure up to 70% of your salary to prevent you from taking out two policies and trying to claim on more than 100% of your policy.
However, you can have two income protection policies that have different waiting and benefit periods. For example, you might have an income protection policy in your super fund that has a 30-day waiting period and another with a 2-year waiting period that pays out until you reach the age of 65.
Can you have different beneficiaries on multiple insurance policies?
Yes. With multiple life insurance policies, you can nominate different beneficiaries for each policy. Ordinarily, you can nominate up to five beneficiaries per policy, and it can be distributed as you wish.
The only time this isn't possible is if you have life insurance through superannuation. Unless you make a binding death nomination, the fund will decide on the beneficiary. A binding nomination on your superannuation life insurance policy would ensure that the benefits go to your intended recipients. This usually incurs a small annual fee to your super.
How do you get multiple insurance policies?
There are lots of ways you can get multiple insurance policies.
- Direct. Direct life insurance is when you receive financial advice from a financial adviser to obtain a policy. This type of cover is usually the most comprehensive.
- Retail. This is essentially insurance without the middleman. It's usually sold to you online and you'll pay with your credit card or with a personal loan.
- Superannuation. Most super funds offer life insurance to their members, so if you have a super account, you probably have life insurance.
- Starting a new job. If you start a new job, your employer might provide you with some kind of life insurance. This is often included in your super.
Things to be aware of when you have more than one life insurance policy
While having additional coverage and security is certainly not a bad thing, there are a few considerations that you should think about when it comes to taking out multiple life insurance plans. Some of the things to consider include the following:
- Managing multiple plans could be more difficult. Although having multiple life insurance plans in place does offer greater security and peace of mind, it can also cause more confusion and become more difficult to manage. The more life insurance plans you have, the more time you will have to put into managing and reviewing them, so you should bear this in mind when considering multiple plans.
- The cost implications of multiple plans. If you take out multiple life insurance plans, you will have to meet premium payments for each plan that you have in place, which means that having multiple plans could prove costly.
- Time implications. When you take out multiple life insurance plans, you will have to dedicate more time not only to finding suitable plans and providers but also to reviewing and checking your life insurance plans and coverage.
Speak to an insurance specialist to help you find personalised cover
Frequently asked questions
-
Yes you generally can have multiple life insurance policies with the same provider. Many insurers allow you to take out multiple types of cover with them such as death cover trauma cover or income protection. However having two identical death cover policies with the same provider is usually not permitted or practical as they would often simply combine the cover amounts. It is best to discuss your specific needs with your chosen insurer.
-
While there is no strict legal limit on the number of policies you can hold or the total sum insured across all life insurance policies, insurers will assess your total cover during the underwriting process. They aim to ensure the total amount of cover is reasonable and justifiable based on your income financial commitments and potential future needs. This prevents over-insurance where the total payout significantly exceeds the financial loss your beneficiaries might experience. Income protection policies for example typically have a cap of up to 75% of your income across all policies.
-
Consider consolidating if you want to simplify admin, reduce fees or align your investment strategy (if policies are linked to superannuation). However keeping multiple policies can be beneficial if each policy serves a distinct purpose, for example one for mortgage protection and another for family income replacement, or if one policy offers unique features or a better premium rate that you would lose upon consolidation. Reviewing each policy's terms conditions and premium structure is crucial.
-
You must always be truthful and disclose all existing insurance policies during the application process for a new policy. Failing to disclose an existing policy could be considered non-disclosure which may impact future claims. If an insurer discovers a material non-disclosure they may reduce your payout, deny a claim or even cancel your policy. Always provide complete and accurate information to avoid complications.
-
The tax implications of life insurance payouts in Australia can vary. Generally a lump sum death benefit paid to a financially dependent beneficiary is tax free. However if paid to a non-dependent beneficiary, or for other types of cover such as income protection or TPD, different tax rules may apply. Having multiple policies does not change the fundamental tax rules for each type of benefit. It is advisable to seek independent financial advice to understand your specific tax obligations when claiming on multiple life insurance policies.
-
While not strictly necessary a financial adviser can be extremely helpful, especially if your financial situation is complex or you have multiple policies across different insurers and types of cover. An adviser can help you assess your total cover needs, identify any gaps or overlaps, compare policies, streamline management, review beneficiaries and ensure your policies remain appropriate for your circumstances. They can provide tailored advice and help you avoid being over or under-insured.
-
Yes many insurers offer comprehensive policies that allow you to bundle different types of cover together under one policy. For example you can often combine death cover with total permanent disability TPD cover, trauma cover and even income protection. This can sometimes simplify management and may offer premium discounts compared to taking out separate policies for each type of cover. Always check the product disclosure statement for what is included and any bundling options.
-
The rate at which your premiums increase is generally determined by factors related to each individual policy such as your age, health status, the type of cover, the sum insured and whether it is a stepped or level premium structure. Having multiple policies in itself does not directly cause individual policy premiums to increase more rapidly. However the overall cost of premiums for all your policies combined will naturally be higher than if you had just one policy. It is important to regularly review each policy's premium structure and how it impacts your total expenditure.
-
Finder writers are subject matter experts and use primary sources, in-depth research and interviews with other experts to ensure you're getting accurate, up-to-date information. Articles are fact checked in line with our editorial guidelines.
Gary Ross Hunter has over 6 years of expertise writing about insurance, including life, health, home, and car insurance. Having reviewed hundreds of product disclosure statements and published over 800 articles, he loves simplifying complex insurance topics for everyday readers. Gary has contributed to major outlets like Yahoo Finance, The Sydney Morning Herald, and news.com.au, and holds a Bachelor of Arts (Honours) in English Literature from the University of Glasgow, along with a Tier 2 General Advice certification, ensuring his work adheres to ASIC’s RG146 standards. See full bio
- Health, home, life, car, pet and travel insurance
- Managing the cost of living
James Martin was the insurance editor at Finder. He has written on a range of insurance and finance topics for over 7 years. James often shares his insurance expertise as a media spokesperson and has appeared on Prime 7 News, Insurance News, 7NEWS and The Guardian. An experienced journalist, James' work has featured in publications including The Irish Times, Companies100 and In Business. He holds a Tier 1 General Insurance (General Advice) certification and a Tier 1 Generic Knowledge certification, both of which meet the requirements of ASIC Regulatory Guide 146 (RG146). See full bio
- Car, home, life, health, travel and pet insurance
- Managing the cost of living
- Money-saving tips
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
More guides on Finder
-
How to switch life insurance policies November 2026
Find out why people switch life insurance policies and how to find the right cover.
-
What happens if I can’t make a life insurance payment?
If you can't afford to pay your life insurance premiums there are still options available to keep your cover alive.
-
Cheap joint life insurance in Australia November 2026
A joint policy might be suitable for couples who both have similar life insurance needs.
-
Life insurance premium increases
Finder explains the cause of life insurance premium increases in Australia.
-
Cheap life insurance: monthly cost guide 2026
Find out what determines the price of life insurance and what you can expect to pay each week to be covered.
Hi, I have life insurance with my Super and one with another company, but when I asked, I should only be paid by one insurance company if I die.
Hi Vino,
Thanks for reaching out to us.
For a life insurance product such as life cover, there are currently no restrictions in place against owning multiple policies with different providers. However, this may not be the case with some life insurance plans. It is essential to speak to an insurance consultant if you require some advice in owning multiple life insurance policies, as they have the expertise and knowledge of the life insurance market.
Best regards,
Rench
How the claim of multiple life insurance policy settled by each company? The sum assured for each company is different..how the total claim is settled ?
Hi Himmat,
Thanks for the question. If you have multiple life insurance policy with different brands you can claim benefits from each. Your total should be the sum of the individual benefits.
I hope this helps,
Maurice
Hi Himmat,
Thanks for getting in touch. finder.com.au is a comparison service and we are not permitted to provide our users with personalised financial advice. The claims process differs between insurers, so you should contact each brand for information about their claims process.
All the best,
Richard