Key takeaways
- You can apply for life insurance in 2 ways - directly to a provider, or through a broker.
- Applying directly is faster, and mostly done online. You'll need to make a medical declaration, but not take a medical exam.
- Going through a broker gives you access to more fully featured policies, but requires a medical exam and can take months.
Life insurance application: Direct vs Broker
The 2 different application types for life insurance are mostly dictated by the type of life insurance you need. You'll either apply directly with the fund, or via a broker. Honestly, they're kind of 2 totally different products, so it's important to understand them.

Directly from the insurer
If you apply directly, the life insurance application process is typically done online by you, without an adviser. The questionnaire itself is usually straightforward and requires a few details about your personal circumstances – for instance, your medical history, employment and age. You'll also need to decide how much life insurance you need and agree to certain exclusions and premium loadings.

With an broker
If you apply with an adviser, the life insurance application tends to be a lengthier and more thorough process, though the adviser will do most of the work. They can work out how much and what type of cover you'll need based on your personal circumstances, clarify anything you're unsure about and talk you through what you are and are not covered for.
What kind of information will I have to provide?
Whether you use a broker or go direct, you'll be asked to disclose the following information:
- Height and weight
- Date of birth
- Gender
- Lifestyle habits (smoking habits, if you drink or take recreational drugs)
- Your own medical history (medications you are taking, any pre-existing conditions)
- Your family's medical history
- Information about your occupation and hobbies
If you go through a broker, the insurer will take the time to confirm these details through a robust assessment, which could include a formal medical exam. If you go direct, your declarations will be enough, but they could come back to bite you if you misrepresent anything.
What are the typical stages involved in a life insurance application?
Submit a policy application
Start the application process by completing the paperwork with your chosen life insurance provider. You need to answer all the questions truthfully (as best you can) and you will need to sign a declaration that the information you have provided is accurate. By deliberately providing incorrect or misleading information, you risk voiding your insurance policy and leaving your family with nothing when they claim.
Medical assessment
Some insurance companies will require you to have an actual physical examination before you're approved; others will just need you to answer questions about your medical history on your application form. If you're having difficulty remembering something about your medical history, contact your doctor for medical records.
Your overall risk is assessed
The life insurance provider will work with an underwriting team to assess your eligibility based on your application. They'll consider your medical history, lifestyle activities, sports you engage in and occupation to work out out the premium you should pay. All of the information in your insurance application will be kept confidential.
What happens after I've been assessed?
Once your application and details have been assessed:
- The life insurance company will notify you in writing of their findings. Usually the company will accept your application and send you a policy schedule with details of the cover and policy you have applied for, as well as the premiums, which have been finalised for you. Your provider will keep your details on file until the time you or your family make a claim.
- If a life insurance provider cannot accept your application they will instead offer you amended terms of insurance so that you can still obtain some form of cover. For example, if you have a serious pre-existing medical condition, or you regularly take part in high-risk activities, then your insurer will do one of two things with your application:
- Apply a loading: This means that you'll have to pay a little extra but you'll still be covered.
- Place exclusions on your policy: For example, if you have a history of blood disease, you won’t be able to claim for any instances related to this condition, or if you regularly participate in high-risk sports such as sky diving, then you won’t be able to claim for any illnesses or injuries resulting from sky diving.
-
Lifestyle changes:
- Quitting smoking (keep in mind that most insurance companies will ask you if you have smoked within the last 12 months)
- Losing weight
- Reducing alcohol intake
- Improving your driving record
Shopping around:
- Switch to a different insurance company. Compare your options below.
- Find a company that specialises in covering people in your situation. You may wish to speak to an insurance specialist to help you with this.
- Pay annually, rather than in monthly instalments – this is often cheaper.
How much cover do I need?
There are a few different ways to determine how much cover you need to take out, including using our online calculator. Another common method is to take your annual salary and multiply it by 10 (so if you make $50,000 a year, take out cover for $500,000).
You might also want to consider the immediate expenses that will need to be covered after your death – such as your funeral, mortgage repayments that still need to be made, other loans or debts that you still need to pay off, school fees and education costs for your children and a retirement fund for your partner. If you total these costs together, you will have a rough idea of how much cover you need.
Compare direct life insurance
The following table features brands that sell direct life insurance. These brands will generally let you apply online, and then offer you cover without having to go through a long, formal process.
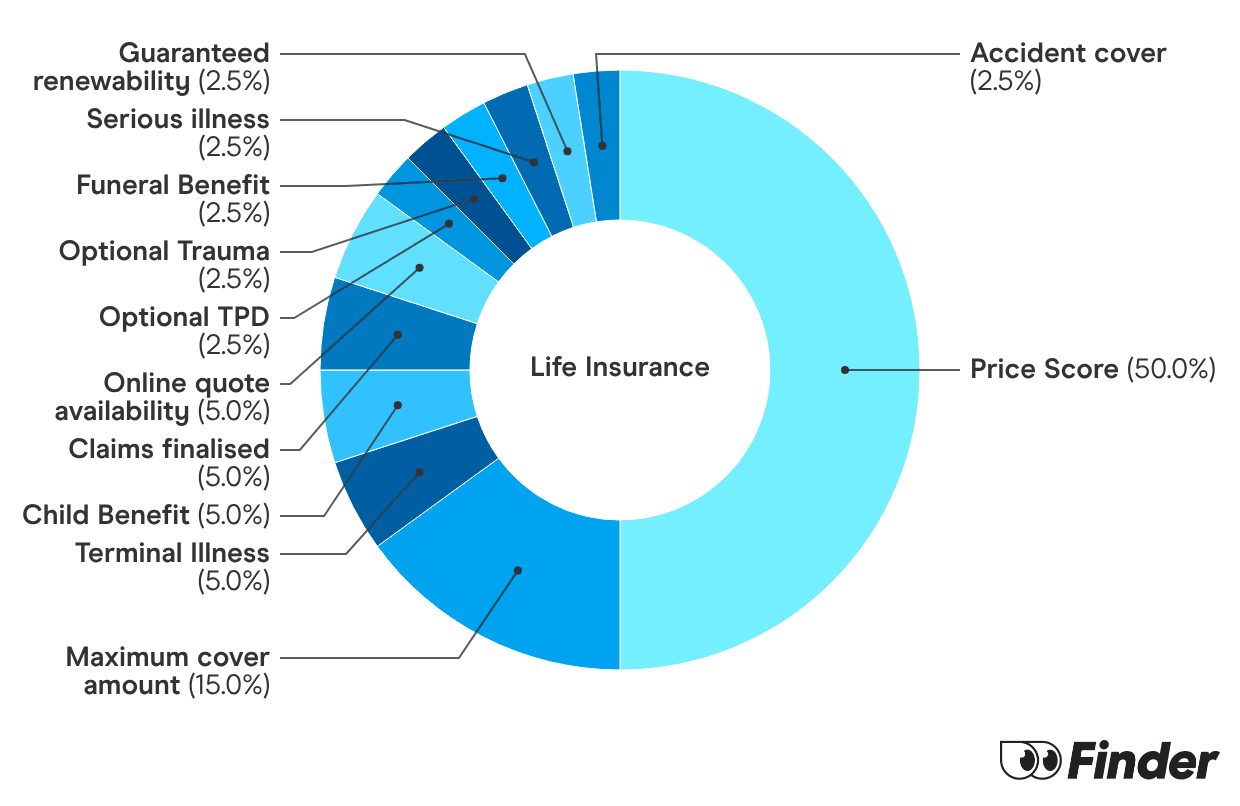
Finder Score - Life Insurance
Life Insurance is a little complicated and a lot overwhelming. That's why we made the Finder Score, to make it easier to compare Life Insurance products against each other. Our experts analysed over 30 products and gave each one a score out of 10.
But a higher score doesn't always mean a product is better for you. Your situation is unique, so your policy choice will be too. Don't think of Finder Score as the final word, but as a good place to start your life insurance comparison.
Speak to a life insurance broker
Have more specific needs, or want to make sure you get the best possible cover that will definitely pay out when you need it to? Then it might be worth speaking to a broker. The process will be longer and more work on your part, but you could have a more robust policy at the end of the day.
Frequently asked questions
-
You will generally need to provide personal identification, proof of address, financial details and a comprehensive medical history. This might include details of current medications, previous surgeries or any ongoing treatments. Having these details ready can help streamline your application process.
-
Providing incorrect or misleading information intentionally could lead to serious consequences. Your insurer may deny any future claims, void your policy or impose stricter terms. It is crucial to be completely truthful to ensure your policy remains valid when your family needs it most.
-
Most Australian life insurance policies have minimum and maximum age limits for applying which vary between insurers. Generally you need to be an Australian citizen, a permanent resident or hold a valid long-term visa to be eligible for cover. It is best to check with individual providers for their specific criteria.
-
In Australia most life insurance policies come with a cooling-off period. This typically gives you 14 to 30 days from when you receive your policy documents to review the cover and decide if it meets your needs. If you cancel within this period you are entitled to a full refund of any premiums paid.
-
Generally you do not have an ongoing duty to disclose changes in health or lifestyle after your policy has been issued and formally accepted by both parties. However some specific policy types or circumstances might have different conditions so always refer to your Product Disclosure Statement for clarity.
-
Some insurers offer temporary or interim cover while your full application is being processed. This usually provides limited accidental death cover for a short period typically up to 90 days. It gives you some protection in case something happens before your main policy is formally approved.
-
If your occupation is considered high risk, for example if you work in mining, construction or emergency services, it may affect your life insurance application. Insurers might apply a loading to your premiums, place specific exclusions on your policy or in some cases decline cover altogether. You may need to seek out specialist insurers.
Gary Ross Hunter has over 6 years of expertise writing about insurance, including life, health, home, and car insurance. Having reviewed hundreds of product disclosure statements and published over 800 articles, he loves simplifying complex insurance topics for everyday readers. Gary has contributed to major outlets like Yahoo Finance, The Sydney Morning Herald, and news.com.au, and holds a Bachelor of Arts (Honours) in English Literature from the University of Glasgow, along with a Tier 2 General Advice certification, ensuring his work adheres to ASIC’s RG146 standards. See full bio
- Health, home, life, car, pet and travel insurance
- Managing the cost of living
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
Read more on Life Insurance
-
Why are women charged more than men for income protection?
Financial literacy advocate Pascale Helyar-Moray on what women do to avoid losing out to higher costs.
-
Denied life insurance? What’s next?
Was your life insurance application denied? This article looks at the top reasons why your application might have been denied and what you can do to get the right cover.
-
Life insurance underwriting
Find out how the underwriting process actually works if considering taking out cover.
-
Life insurance for smokers
Ever wondered how much more life insurance for smokers costs in Australia? Learn about how smoking and vaping can impact your policy.
-
Should I tell my life insurance company that I smoke?
Find out how smoking will impact what you pay for life insurance, and what you can do to have your premium reviewed.
-
What is life insurance?
Not sure what life insurance is? We take you through the basics of life insurance with our easy to understand guide.
-
Life insurance beneficiary rules Australia
Read our guide to updating life insurance beneficiaries and making sure your money goes to the right people.
-
No Medical Life Insurance
Depending on the applicant and the type of life insurance policy, there may be no medical tests required.
-
Variable age-stepped premiums vs variable premiums
finder's guide to choosing between variable age-stepped and variable insurance premiums.