How can Finder help you today?
Find the right home loan in 4 clicks


Most lenders won't consider a mortgage application from someone who has experienced bankruptcy, even if you've been discharged from the bankruptcy.
But there are specialist bad credit lenders and brokers who can help, such as:
Qualified mortgage brokers can help you find appropriate bad credit mortgages. They specialise in helping borrowers in unique circumstances and also help you craft the best possible mortgage application.
You can get an apply for a mortgage from the first day your bankruptcy ends. But keep in mind that your bankruptcy remains on your credit report:
Unfortunately, your credit file doesn't list the reasons behind your bankruptcy, meaning you could find it very difficult to get any sort of home loan even once you're discharged.
Because these listings stay on your credit file for five years, this can put your dreams of owning a home on hold.
That's why finding a specialist lender is a really good idea.
It always helps to have a strong mortgage application. Here are some tips to strengthen your application even as a discharged bankrupt:
Here are some useful guides to improving your credit report.:
Check your credit score for free right now
A home loan from a specialist bad credit lender serves the same basic purpose as any other mortgage: it lets you borrow money to buy a property.
But there are some differences too:
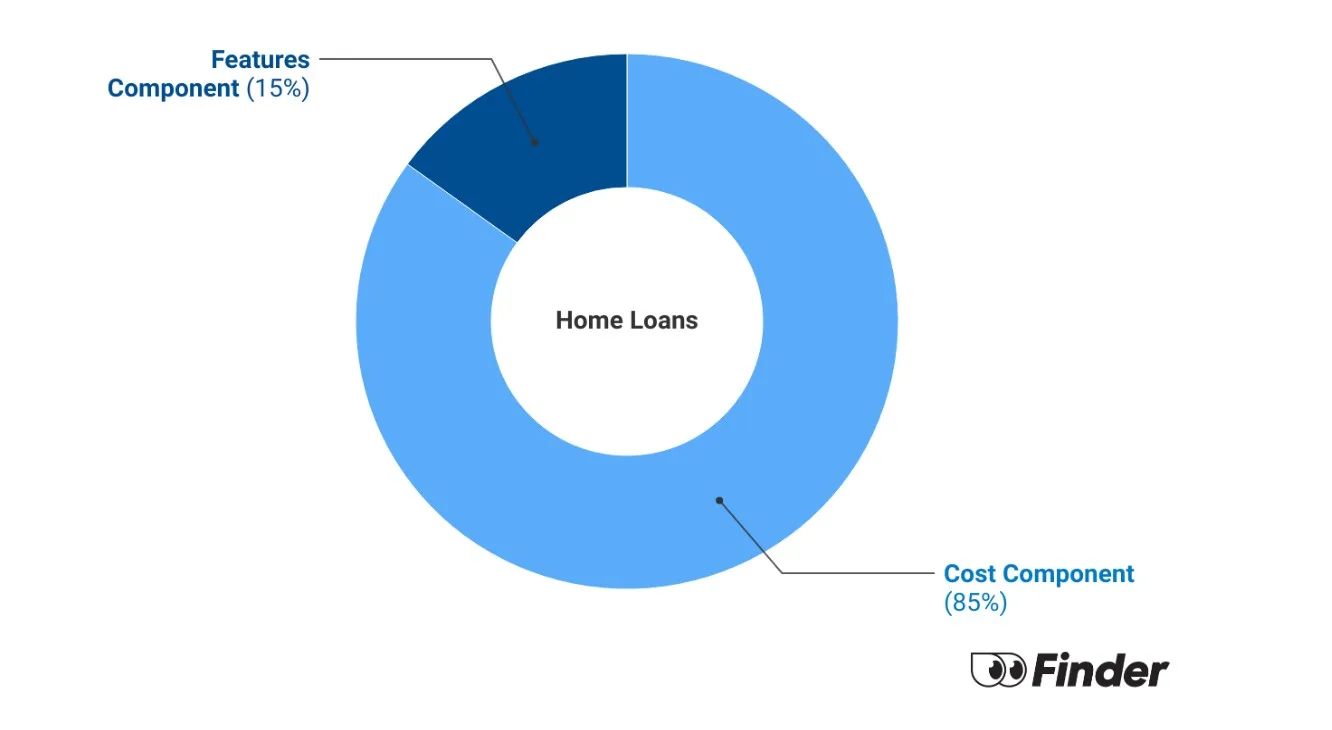
The Finder Score crunches 7,000 home loans across 120+ lenders. It takes into account the product's interest rate, fees and features, as well as the type of loan eg investor, variable, fixed rate - this gives you a simple score out of 10.
To provide a Score, we compare like-for-like loans. So if you're comparing the best home loans for cashback, you can see how each home loan stacks up against other home loans with the same borrower type, rate type and repayment type. We also take into consideration the amount of cashback offered when calculating the Score so you can tell if it's really worth it.
Here’s a breakdown of exactly what foreclosure means.
A guide to distressed property sales in Australia, including risks to be aware of and tips for buying distressed properties.
Mortgage stress refers to when a homeowner is paying over 30% of their income towards repayments on their home loan.
If you’re having trouble securing a home loan through traditional means, there are some government programs that might help you achieve your property goals.
Now that you've paid off your mortgage, find out how to finalise your home loan and where to invest your money next.
If you want to buy a block of vacant land to build a home, you may need a land loan.
If you're receiving Centrelink payments you may be able to use them as part of your income when applying for a home loan.
Pensioners can have a tough time getting a home loan because each lender treats pension payments differently. Here are some tips you can use to find out whether or not you could get a home loan.
If you haven't sold your house yet, but want to buy your next one before the sale is completed a bridging loan may be able to help. Read on to discover how bridging finance can help.
Low doc home loans allow you to get a mortgage if you're self-employed or don't have regular payslips. check your eligibility and compare competitive offers now.

If I’m co-borrowing with someone who isn’t an ex-bankrupt, does this make a difference to your lending options?
Hi Nick,
Thanks for your question.
It does widen your lending options a bit, as the lender will consider the combined credit histories of both applicants.
Having said that, it might not widen your options a whole lot, especially if the bankruptcy occurred less than seven years ago.
If you’d like, you may want to consider a mortgage broker who can help find a home loan for your situation.
All the best,
Shirley
Hi Nick,
Thanks for the question.
When co-borrowing with someone, both of your credit histories will be taken into account when your lender is deciding whether to approve your application or not. This means that even if one borrower has a clean credit history if the other has negative listings, you may have trouble getting approved for a loan from a regular bank. In these cases, it may be helpful to seek the services of a mortgage broker or a bad credit home loan to help you find a loan.
I hope this helps,
Marc