Key takeaways
- There are many life stages where someone would want to consider life insurance, like the birth of a child or purchasing a home.
- Knowing what kind of cover you need can help you determine if or when you'll need cover.
- The amount of cover you'll need will depend on a few factors, like your age, your lifestyle and if you have any dependents.
When to think about taking out life insurance
For some, it's a no-brainer, for others, it's a head-scratcher.
Determining if or when you need life insurance is not as easy a question as it sounds. It means having to consider a time when you're no longer here or can no longer work. According to NobleOak, 60% of Australians now hold some form of life insurance or income protection insurance.
Whether you're 21 and single or 50 and married with children, different life stages call for different outcomes. Here are some of the most common life stages where people begin thinking about life insurance:
- You landed a new job. A new role with a new salary can prompt many Australians to consider income protection insurance. This allows you and any dependents to maintain your lifestyle if you were no longer able to work due to sickness or injury.
- You're self-employed. If you work for yourself, income protection can be vital, as self-employed workers don't receive workers' compensation.
- You're newly married. If you've recently gotten married, you may want to purchase life insurance to protect your spouse if something were to happen. This ensures they'd be able to maintain their current lifestyle and keep up with major bills and expenses.
- You've had a baby. Becoming a parent is a major milestone for many. But it also means you now have someone depending on you. Life insurance ensures your child can continue to live comfortably if you pass away or become seriously injured or sick.
- You've bought a house. Between mortgage repayments and keeping up with repairs, purchasing a house is a costly investment. Life insurance means your loved ones will be able to financially keep up with these financial demands.
- You're young and healthy. Younger Australians may want to get ahead and take out a policy when they're young to secure lower premiums. It can also help you avoid exclusions later on as you age and your health condition changes.
Based on where I'm at in life, what type of cover do I need?
Everybody is different and cover requirements will change based on the events you encounter at different life stages. But still, it's worth a look at a more detailed overview of key times many decide to take out cover based on their life stage.
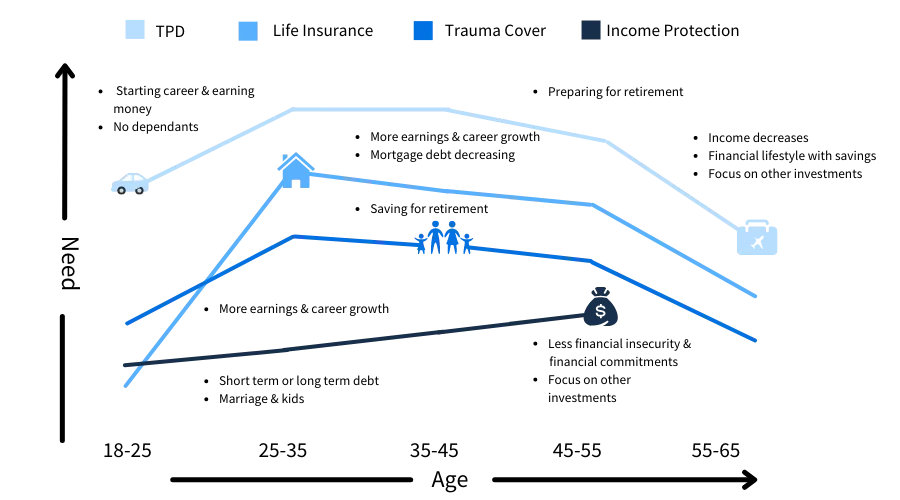
Different types of life insurance
Here are the main types of life and income protection cover you can get:
Life cover.
Term life insurance provides a lump sum benefit to your beneficiaries in the event of death or after the diagnosis of a terminal illness. You can get this insurance as a standalone policy, or bundled with more cover options.
TPD insurance.
Total permanent disability (TPD) insurance provides a lump sum benefit if the policyholder suffers a disability as defined in their policy.
Trauma insurance.
Provides a lump sum benefit if the insured suffers a medical trauma that is specified in their policy. Most policies will cover up to 50 different conditions including strokes, cancer and heart attacks.
Funeral insurance.
Funeral insurance provides a lump sum benefit to cover funeral costs and other outstanding expenses. The maximum amount of cover that can be taken out is usually about $15,000.
Income protection insurance.
Income protection offers an ongoing benefit of up to 70% of the policyholder's regular income if they are forced to take time off work due to illness or injury. This benefit is usually paid monthly.
How much life insurance might I need?
The amount of life insurance you need depends on your personal circumstances, such as your age, and the type of cover you want. Start by coming up with an annual sum you'd need to cover your financial commitments. Some experts say the amount of cover you'd want is at least 10 times your annual salary. But it's really up to you to decide how much your family would be comfortable with based on your situation.
You could also check to see if you already hold some life cover, such as via employment benefits. See how much that would pay out to your dependents and then calculate how much extra they might need.
Don't I get life insurance through my superannuation?
Yes, life insurance is automatically added to your super account if you're over 25 and have $6,000 or more in your account. The premiums for this insurance are deducted from your super balance unless you opt out and cancel your policy. Death cover, TDP cover and income protection cover are available through your superfund.
While many Australians choose to rely on this insurance, it might not give you the flexibility you need. The major benefit of purchasing a life insurance policy directly from an insurer is that you'll have greater choice in taking out the exact type of cover you need.
It's also worth noting that paying for life insurance through your super reduces your retirement balance, which can be an issue if you have no other investments that provide passive income.
What to consider before purchasing life insurance
Before you start shopping around on life insurance, there are a few things to keep in mind. By law, life insurers are required to provide prospective customers with a product disclosure statement (PDS). This gives you an opportunity to learn everything you are covered and not covered for.
Other things to investigate during your search include:
- The waiting periods that apply before you can make a claim
- What the process is for making a claim
- What to do if you need to make a complaint about a claim or a decision
Compare life insurance quotes from more direct brands
Looking for other options? Check out these similar products.
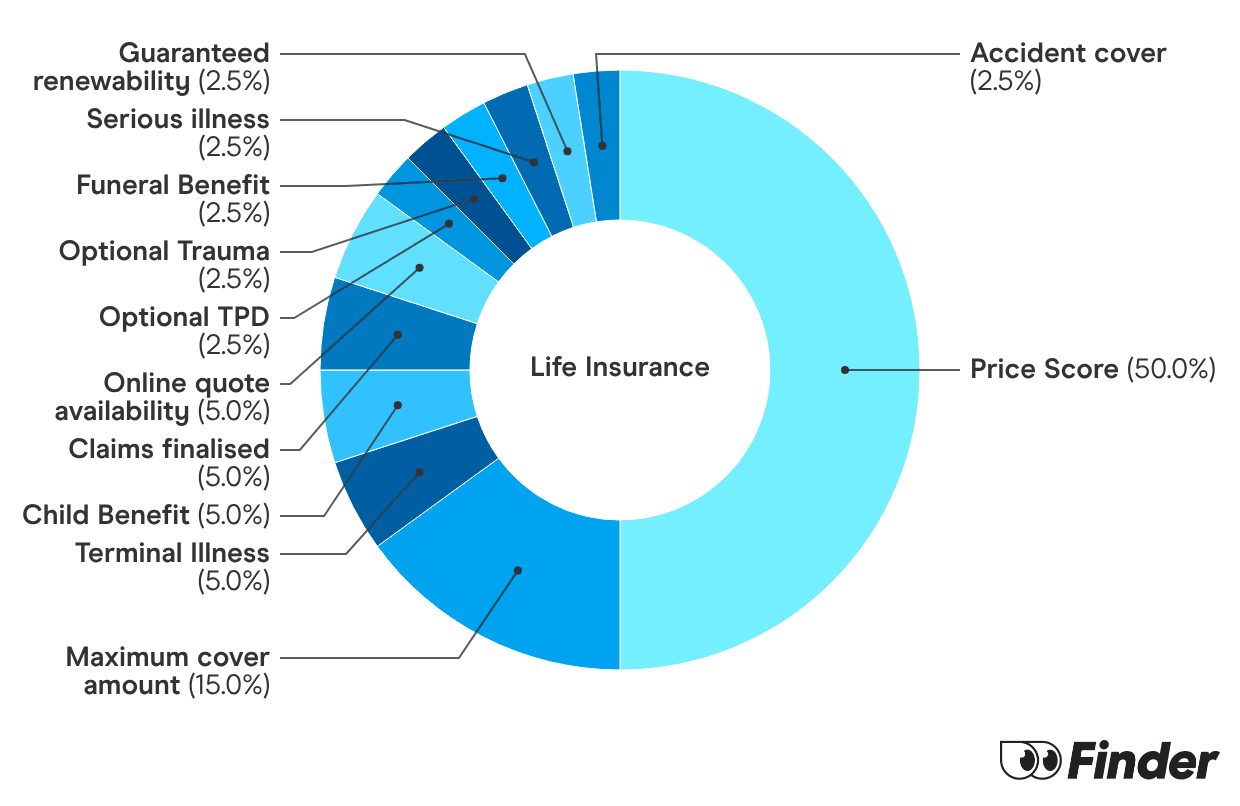
How we picked theseFinder Score - Life Insurance
Life Insurance is a little complicated and a lot overwhelming. That's why we made the Finder Score, to make it easier to compare Life Insurance products against each other. Our experts analysed over 30 products and gave each one a score out of 10.
But a higher score doesn't always mean a product is better for you. Your situation is unique, so your policy choice will be too. Don't think of Finder Score as the final word, but as a good place to start your life insurance comparison.
Frequently asked questions
-
The need for life insurance often reduces once people enter their retirement years and their financial obligations change. You may wish to decrease the amount of cover you have in future years, but still have some in place to:
- Provide a legacy to your surviving children in the event of your death
- Cover your funeral expenses
- Tie up any final expenses such as legal fees or taxes
-
Your age, gender and lifestyle (for example, whether or not you smoke) are some of the key factors an insurer takes into account when setting your insurance premium.
The cost of your policy isn't everything when you're comparing life insurance though. You may choose to add more features to your cover and pay a bit more for your premium.
It's important to find a policy that'll meet your specific needs and circumstances. If you prefer, speak to an insurance specialist to help you find personalised cover.
-
It is natural for the need for life insurance to reduce once people enter their retirement years and their financial obligations change. You may wish to decrease the amount of cover you have in future years but still have some in place to:
- Provide a legacy to your surviving children in the event of your death
- Cover funeral expenses
- Tie up any final expenses such as legal fees or taxes
It is worth taking into consideration existing assets that may be used in the event of your death such as:
- Superannuation
- Savings
- Property
- Other assets such as car, contents
-
For young people, there's typically less of a need to get life insurance as there are fewer ongoing financial obligations compared to those who are older or with families of their own.
However, funeral insurance is an option to consider. Then there's TPD, Trauma or Income Protection, all of which can offer support if you suffer a serious injury or illness.
-
Most Australians have some sort of cover in their super fund and/or through workers' compensation insurance, but make sure you check as this won't be the case for everyone.
Good to know: These default cover types usually have more restrictive benefits and less generous terms in comparison to standard life insurance policies.
Sources
James Martin was the insurance editor at Finder. He has written on a range of insurance and finance topics for over 7 years. James often shares his insurance expertise as a media spokesperson and has appeared on Prime 7 News, Insurance News, 7NEWS and The Guardian. An experienced journalist, James' work has featured in publications including The Irish Times, Companies100 and In Business. He holds a Tier 1 General Insurance (General Advice) certification and a Tier 1 Generic Knowledge certification, both of which meet the requirements of ASIC Regulatory Guide 146 (RG146). See full bio
- Car, home, life, health, travel and pet insurance
- Managing the cost of living
- Money-saving tips
Ceyda Erem is Finder’s senior writer for insurance and has almost 10 years of experience writing about personal finance. Formerly a copywriter for several business and finance clients, Ceyda has written hundreds of articles, guides, blogs and more to ensure Australians stay in the loop about how to best manage their money. She has a Bachelor of Arts, Majoring in Writing from Macquarie University. See full bio
- Insurance
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
More guides on Finder
-
Best life insurance in Australia October 2026
Read our comprehensive guide to finding the best life insurance policy for your situation.
-
Term Life Insurance in Australia
Find out how term life insurance actually works and receive quotes for cover securely.
-
HCF Life Insurance review
With HCF life insurance products, you can benefit from flexibility and peace of mind given the range of policies to choose from.
-
The cost of raising children in Australia
Find out how life insurance can cover your children in case anything happens to you.
-
AAMI Life Insurance Review
Compare policies on offer from one of Australia's leading general insurance providers, AAMI.
-
Whole life insurance
Whole life insurance was a popular form of life insurance cover in Australia during the 1970s and 1980s.
-
Australian Seniors Life Insurance Review
Review the Australian Seniors Life and compare options available.
-
Death statistics Australia
By 2066, 1 in 5 Australians will be over the age of 65.
-
Acenda Insurance Review
Find out what life insurance policies are on offer from Acenda and receive a free quote for cover. Apply securely with the help of an insurance consultant.
-
Zurich Life Insurance Review
Find out what cover is on offer from Zurich Life Insurance and receive a secure quote for cover. Zurich offers a Life, Income, TPD, Trauma, and Child Cover with additional options to tailor cover further.