Key takeaways
- Income protection can help pay your bills if you cannot work due to a sudden illness or injury.
- Income protection is super valuable if you do not have emergency savings.
- Even with savings, income protection may be important if you rely on a single income, have debts or are self-employed.
What does income protection offer me?
Income protection is an insurance policy you can take out that will pay you part of your income if you're unable to work because of getting sick or injured. Generally, income protection can pay out:
- Up to 90% of your income for the first 6 months after you stop working
- Up to 70% of your income after the first 6 months, or 75% with some insurers are over, up to your elected benefit period
Every fund offers different benefits and definitions of full and partial disability, which will affect what you can claim. Be sure to read the Product Disclosure Statement (PDS) carefully.
Finder survey: How many Australians have income protection insurance?
| Response | |
|---|---|
| I don't have any of the above insurance | 60.54% |
| Life insurance | 32.52% |
| Income protection insurance | 18.38% |
| TPD insurance | 14.32% |
When income protection is worth it
Put simply, if you would be in financial stress if you stopped earning your income today, you could probably benefit from income protection. This will be more likely if you have dependencies, debts, or if you rely on a single income. Here are a few examples:
- You have rent or mortgage repayments you couldn't cover without your salary
- You have a spouse, children or other dependants that rely on your salary
- You don't have enough savings to cover more than a few weeks of your regular expenses
- You're a sole trader or casual worker, without access to leave or paid time off
- You want the security of not having to rush going back to work if you're sick or injured
When income protection might not be worth it
There are few times when you might not need income protection.
No expenses of dependencies: If you have low or no expenses, dependencies or debts, you might not need income protection insurance.
Close to retirement: If you've only few more years in the workforce and have enough savings, your response to sickness or injury might just be to retire early.
Low salary: Income protection is most useful to people earning a lot. If you're on a low salary, you might not benefit from income protection. You could look at Total & Permanent Disability insurance instead, whichpays out if you become permanently unable to work, regardless of earnings.
These aren't the only groups who might not need income protection, and you may still benefit if you fall into one of these categories. You should speak to a licensed financial planner before making any a decision.
"If you incur expenses for medical reports required to support your income protection insurance claim, these costs can be tax-deductible. This includes any fees paid to obtain documentation proving your inability to work due to illness or injury. Make sure to keep all receipts and records of these expenses to claim them when filing your tax return."
How much savings do you need to not need income protection?
Unfortunately, Finder research finds most Australians have far less than 3 month's earnings in their savings. According to Finder's Consumer Sentiment Tracker data from July 2023, around 60% of Aussies have less than 3 months of savings. The full data is in the chart below.
If you lost your job how long could you live off savings?
The length of time that Australians say they could live off their savings alone, if they were to lose their job tomorrow, according to Finder's Consumer Sentiment Tracker, July 2023.
| Savings time | Percentage of Aussies |
|---|---|
| Less than a week (15%) | 15% |
| Around 1 week (8%) | 8% |
| Around 2 weeks (9%) | 9% |
| Around 3 weeks (6%) | 6% |
| Around 1 month (13%) | 13% |
| Around 2 months (9%) | 9% |
| Around 3 months (13%) | 13% |
| 4 to 6 months (8%) | 8% |
| 6 months or more (20%) | 20% |
Compare policies from Australian income protection brands
Looking for other options? Check out these similar products.
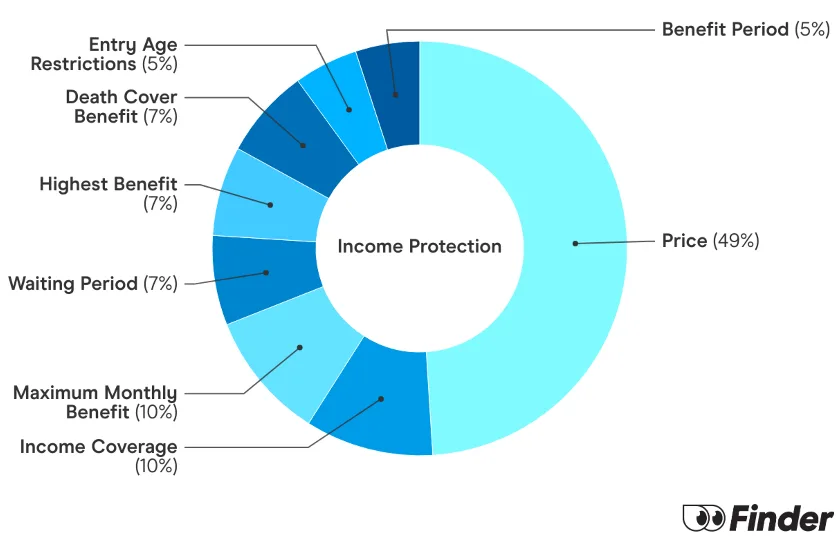
How we picked theseFinder Score - Income Protection
Income Protection is a little complicated and a lot overwhelming. That's why we made the Finder Score, to make it easier to compare Life Insurance products against each other. Our experts analysed over 21 products and gave each one a score rank out of 10, to make it easier to compare Income Protection products against each other.
But a higher score doesn't always mean a product is better for you. Your situation is unique, so your policy choice will be too. Don't think of Finder Score as the final word, but as a good place to start your life insurance comparison.
"My income protection policy is an insurance I hope I never have to claim on – I consider it to be a financial back-up in case something terrible happens. Is it essential? Probably not, but hopefully it will provide my family with some financial breathing space if and when we ever need it."
Frequently asked questions
-
Yes, many Australians hold income protection cover through their super fund. It is often referred to as 'group insurance' and can be a cost effective way to get cover. However policies held through super may have different terms, conditions and benefit limits compared to standalone policies. Always check the Product Disclosure Statement to understand your cover.
-
Income protection pays a regular income if you are temporarily unable to work due to illness or injury. Total and Permanent Disability TPD insurance on the other hand pays a one off lump sum if you become permanently unable to work due in part to illness or injury. These policies serve different purposes and can complement each other.
-
Generally, income protection policies allow you to cover up to 70% of your gross monthly income. Some policies may offer up to 90% for a short initial period often the first six months after you stop working. The aim is to replace a significant portion of your income while providing an incentive to return to work.
-
Yes, income protection is particularly valuable for self-employed individuals, sole traders and freelancers. Unlike full time employees you typically do not have access to paid sick leave or annual leave. Income protection provides a financial safety net ensuring you can continue to pay your essential living expenses if you cannot work due to illness or injury.
-
It is possible to get income protection with a pre-existing medical condition but your application will be assessed individually. Insurers may offer cover with exclusions for the specific condition, apply a loading to your premiums or in some cases decline cover. It is important to disclose all relevant medical history when applying.
-
To make an income protection claim you typically need to contact your insurer as soon as possible after becoming ill or injured. You will need to provide medical evidence supporting your inability to work and details of your employment and income. Your insurer will guide you through the specific documentation required for their claims process.
Sources
A seasoned journalist with over 10 years of experience in news, politics and finance reporting, Tim has previously held roles at the ABC, SBS and Fairfax Media. Tim’s expert insights have been quoted in The Australian, The Daily Telegraph, The Courier Mail and more. He regularly appears on TV and radio, and has been interviewed on 7 News, Sunrise, SBS News, ABC Local, 3AW and 5AA. Tim is passionate about simplifying complex insurance topics for Australian consumers. He holds a Bachelor of Arts (Politics) from Macquarie University and a Tier 1 General Insurance (General Advice) certification, which meets the requirements of ASIC Regulatory Guide 146 (RG146). If you’re interested in a media interview with Tim, please reach out to our PR team at aupr@finder.com. See full bio
- Personal finance
- Financial comparison
- Health insurance
- General insurance
- Life insurance
James Martin was the insurance editor at Finder. He has written on a range of insurance and finance topics for over 7 years. James often shares his insurance expertise as a media spokesperson and has appeared on Prime 7 News, Insurance News, 7NEWS and The Guardian. An experienced journalist, James' work has featured in publications including The Irish Times, Companies100 and In Business. He holds a Tier 1 General Insurance (General Advice) certification and a Tier 1 Generic Knowledge certification, both of which meet the requirements of ASIC Regulatory Guide 146 (RG146). See full bio
- Car, home, life, health, travel and pet insurance
- Managing the cost of living
- Money-saving tips
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
More guides on Finder
-
Cost of living comparison
How much could you save if you lived in a different city in Australia? Let's find out.
-
AAMI Income Protection Review
Find out what is and isn't covered by AAMI Income Protection and how to apply.
-
Income protection for couplesÂ
Income protection for couples ensures your partner isn't hurt financially if you are temporarily unable to work due to illness or injury.
-
Income protection for over 60 in Australia
Find out why income protection is still useful if you're over 60, and compare cover.
-
Salary Continuance Insurance vs Income Protection
Salary continuance and income protection both serve to replace income in the event of injuries and illness. However, there are some key differences to know about.
-
Suncorp Income Protection Insurance Review
Receive income cover for illness or injury with Suncorp Income Protection.
-
Life insurance vs income protection insurance
Life insurance and income protection serve two different purposes but can both offer valuable cover alone and when combined.
-
Income protection insurance calculator
Find out how much your income protection insurance policy will pay out in the event of a claim. Receive quotes for income protection and apply securely.
-
Best income protection insurance Australia 2026
Looking for the best income protection insurance but not exactly sure where to start? Compare the Finder Awards 2025 insurance winners.