Key takeaways
- WorkCover covers work-related incidents only, and is compulsory for some jobs. Income protection covers illness or injury anytime, anywhere.
- Income protection offers longer benefit periods and premiums are often tax-deductible, unlike employer-paid WorkCover.
- Self-employed individuals need income protection for cover as WorkCover generally excludes them.
WorkCover and income protection both provide you with an income should an illness or injury force you to stop working. However, there's a key difference between the two:
- WorkCover. Designed to cover work accidents and illnesses.
- Income protection. Covers incidents inside and outside work that stop you from working.
What's the difference between WorkCover and income protection?
Income protection is not the same as workers compensation. Here are the main differences:
| Income protection | Workers compensation | |
|---|---|---|
| What cover does it provide? |
|
|
| Where am I covered? |
|
|
| How long is a benefit paid for? |
|
|
| How much does it cost? |
|
|
| Are self-employed workers covered? |
|
|
Should I still consider income protection?
There are a number of reasons you might consider having income protection. Income protection is a far more comprehensive type of insurance. It pays you 75% of your income and you don't need to prove where your injury or illness occurred like workers compensation; you just need to prove that you're unable to work. Take a look at the income protection calculator and comparison table below to find a policy that works for you.
Looking for other options? Check out these similar products.
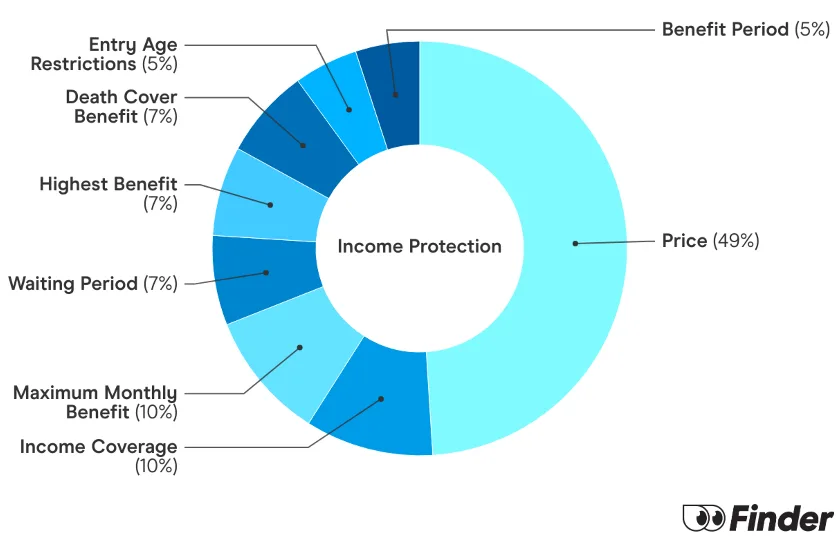
How we picked theseFinder Score - Income Protection
Income Protection is a little complicated and a lot overwhelming. That's why we made the Finder Score, to make it easier to compare Life Insurance products against each other. Our experts analysed over 21 products and gave each one a score rank out of 10, to make it easier to compare Income Protection products against each other.
But a higher score doesn't always mean a product is better for you. Your situation is unique, so your policy choice will be too. Don't think of Finder Score as the final word, but as a good place to start your life insurance comparison.
Speak to an insurance specialist to help you find personalised cover
Pros and cons of WorkCover and income protection
| WorkCover | Income protection | |
|---|---|---|
| Pros |
|
|
| Cons |
|
|
What are the types of WorkCover payments you can receive?
One outstanding issue concerning workers compensation is that there is no uniformity in its benefit periods and amounts. Each state has its own workers compensation laws.
There are basically four types of benefits you can have under workers compensation: income replacement, permanent disability, medical benefits and death benefits.
- Income replacement. Income replacement through workers compensation may vary from state to state. Lump sum benefits are determined based on the nature of the injury sustained.
- Permanent disability. Under the workers compensation policy, permanent disability or impairment is defined as the illness remains unchanged despite continuous medical treatment. Once deemed permanently disabled, you will be paid a lump sum benefit in addition to your weekly benefits.
- Medical benefits. These benefits cover medical costs and other health-related expenses for injuries sustained at work. The amount will again vary from state to state depending on the severity of the accident or injury. However, if the injury or accident happened outside the work premises, you are not eligible to claim.
- Death benefits. Just like other insurance policies, your beneficiaries can receive a lump sum benefit in the event of your death to help them cover funeral costs and other living expenses.
Under the policy, you can be paid one or more of these benefits. The benefit period is between 13 weeks and 9 years, but is subject to the maximum limits of the lump sum.
When am I eligible to claim WorkCover or income protection?
There are far more restrictions when it comes to claiming with workers compensation:
- WorkCover. You are only eligible to claim if you are injured inside your workplace. This means you need to prove that your injury occurred directly as a result of work, which can be difficult. You also can't make a claim if your injury was caused due to negligence.
- Income protection. If you are injured or ill, you are eligible to claim income protection. Unlike WorkCover, this includes injuries or illnesses occurring outside of work, at any time of the day and anywhere in the world. Like WorkCover though, it won't cover you for voluntary redundancy, though some cover you if you lose your job.
When does cover end?
WorkCover and income protection have different lengths of coverage:
- Income protection. Your cover length will depend on your benefit period. This is the length of time that your monthly income protection payment will be paid to you upon a successful claim. In Australia, insurers typically offer the benefit period option of 2 or 5 years or until you reach the age of 65.
- WorkCover. The benefit period can vary massively with WorkCover. Some are capped at 130 weeks. If you do need to be off longer than this time, you will likely have to undergo a Work Capacity Assessment.
Can you claim WorkCover and income protection at the same time?
Yes, but it's likely that your insurance policy will offset your workers compensation payments. This is so that you don't end up earning more than 100% of your pre-disability salary.
If your benefit payment is reduced as a result of workers compensation payments, some insurers will refund you some of the premiums that you have previously paid.
In the unlikely event that you are injured at work, you should look at how much workers compensation will actually pay you and how long it will pay you for. Even if you are eligible for WorkCover, income protection usually comes with longer benefit periods and inclusions like specified injury benefits and flexible disability definitions.
FAQs
-
This is the amount of time you must wait after an illness or injury before your income protection payments begin. Common waiting periods include 14 days, 30 days, 60 days or 90 days. The longer your waiting period the lower your premiums usually are. You can use your sick leave or savings to cover this initial period.
-
Yes, you can often hold income protection insurance within your super fund. This means your premiums are paid directly from your super balance. While it can be a convenient way to manage payments it is important to understand the specific terms and conditions of policies offered via super as they may differ from policies you purchase directly.
-
Generally, income protection does not cover voluntary redundancy, criminal acts or injuries and illnesses that occurred before you took out the policy unless declared and accepted by the insurer. It also typically will not cover you if you are able to work but choose not to or if your income loss is due to a general economic downturn. Always refer to the Product Disclosure Statement for full exclusions.
-
To make a WorkCover claim you typically need to report your injury or illness to your employer as soon as possible. Your employer should provide you with a claim form. You will also need to see a doctor to obtain a WorkCover medical certificate which details your injury or illness and your capacity for work. Submit the completed claim form and medical certificate to your employer or their insurer.
-
WorkCover laws vary by state but generally they cover most employees including casual and part time workers. However contractors and sole traders are usually not covered as they are considered self employed. In some states specific types of contractors such as those deemed 'deemed workers' may be eligible. It is best to check your state's specific workers compensation legislation.
-
Many modern income protection policies do cover mental health conditions provided they meet the policy's definition of disability and you are under the care of a medical professional. However some older policies or basic policies might have exclusions or limitations regarding mental health. It is crucial to check the Product Disclosure Statement of any policy you consider to understand its specific coverage for mental health.
-
Finder writers are subject matter experts and use primary sources, in-depth research and interviews with other experts to ensure you're getting accurate, up-to-date information. Articles are fact checked in line with our editorial guidelines.
Gary Ross Hunter has over 6 years of expertise writing about insurance, including life, health, home, and car insurance. Having reviewed hundreds of product disclosure statements and published over 800 articles, he loves simplifying complex insurance topics for everyday readers. Gary has contributed to major outlets like Yahoo Finance, The Sydney Morning Herald, and news.com.au, and holds a Bachelor of Arts (Honours) in English Literature from the University of Glasgow, along with a Tier 2 General Advice certification, ensuring his work adheres to ASIC’s RG146 standards. See full bio
- Health, home, life, car, pet and travel insurance
- Managing the cost of living
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
More guides on Finder
-
Real Income Protection Insurance review
Real Income Protection Insurance has similar cover to many popular providers. However, optional extras are limited.
-
Cost of living comparison
How much could you save if you lived in a different city in Australia? Let's find out.
-
Aspect income protection insurance review
Cover up to 85% of your salary with one of Aspect's flexible income protection policies.
-
TAL Income Protection Insurance review
Learn the built-in benefits of TAL income protection to understand how it could work for you. Compare features and get a quote today.
-
Sick leave Australia: What you’re entitled to and when
Find out why income protection is an important tool to combine with your entitled sick leave.
-
Income protection with pre-existing conditions – yes, you can get it.
Find out how you can benefit from income protection even if you have a pre-existing condition, and which providers will cover you.
-
Suncorp Income Protection Insurance Review
Receive income cover for illness or injury with Suncorp Income Protection.
-
Redundancy and unemployment insurance
Most providers no longer offer unemployment insurance in Australia if you're made redundant.
-
Rest Super income protection
Rest Super has grown to become one of Australia's largest super funds with a range of protection options for members including life cover, TPD cover and long term income protection.
-
Best income protection insurance Australia 2026
Looking for the best income protection insurance but not exactly sure where to start? Compare the Finder Awards 2025 insurance winners.