Home Loans for Pensioners
While it is harder, you can get a home loan while on a pension. It depends on how much you want to borrow, your spending, assets and if you have other income sources.
Getting a loan as a pensioner always comes down to the lender's eligibility criteria and your individual circumstances. This includes your savings and other sources of income, whether you have outstanding debts or not and the amount you are hoping to borrow.
If your only source of income is the pension, then this might limit your options. The pension amount is lower than the income level most lenders require you to earn in order to repay a loan.
However, there are several ways a pensioner might be able to apply for mortgage finance.
If you have forms of income from other sources or you're only borrowing a small amount, you may be able to apply for a home loan like any other borrower. You might even be able to get a competitive interest rate, so be sure to compare your home loan options.
There are lenders who specialise in providing finance solutions to borrowers in difficult or unique circumstances. These types of lenders provide loans known as specialist or non-conforming loans. There are even lenders who focus entirely on older borrowers.
Non-conforming lenders may be able to help where the big banks can't. But they often charge higher interest rates and fees.
Keep in mind that many lenders that specialise in "senior's finance" don't actually lend to pensioners who don't already own property. Instead they offer reverse mortgages and other forms of equity access to older Australians who already own property.
Perhaps the best option for pensioners looking for a home loan is to get in touch with a mortgage broker. This is because mortgage brokers specialise in helping borrowers in unique circumstances and they have access to a wide panel of lenders.
A broker can help you look for loans and lenders that match your requirements. Their services are typically free to you because the lender you choose will pay them a commission.
As a pensioner you'll need to provide a few extra documents in addition to the standard documents in a mortgage application. Every lender has their own requirements but you'll generally need to provide the following:
Generally, lenders consider a disability pension to be a valid form of income, meaning they treat a home loan application for someone on a disability pension just like any other application.
Most lenders will review your application on a case-by-case basis. Your eligibility for a home loan will depend on the amount of income you receive and how much of this can be used to service a loan.
Other factors including your age, assets and debts will be assessed by a lender on an individual basis.
Many lenders may accept a Veterans' Pension as a source of income for a home loan. This applies if you are receiving:
Additionally, lenders may accept the Department of Veterans' Affairs Incapacity Pension as a source of income. In order to demonstrate your pension as a source of income for a home loan application, you'll need either a current bank statement showing your pension payment, or a current Department of Veterans' Affairs statement.
On Centrelink? You could still get a home loan
If you're a pensioner who already owns their own home you have some other finance options. Both reverse mortgages and line of credit loans allow you to borrow money against the equity in your home.
In the tables below you can compare various finance options, from normal home loans to reverse mortgages and lines of credit. Please be aware that not all of the options presented in the table will be available for pensioners. If you're a pensioner and are looking for expert guidance, contact a mortgage broker for personal advice.
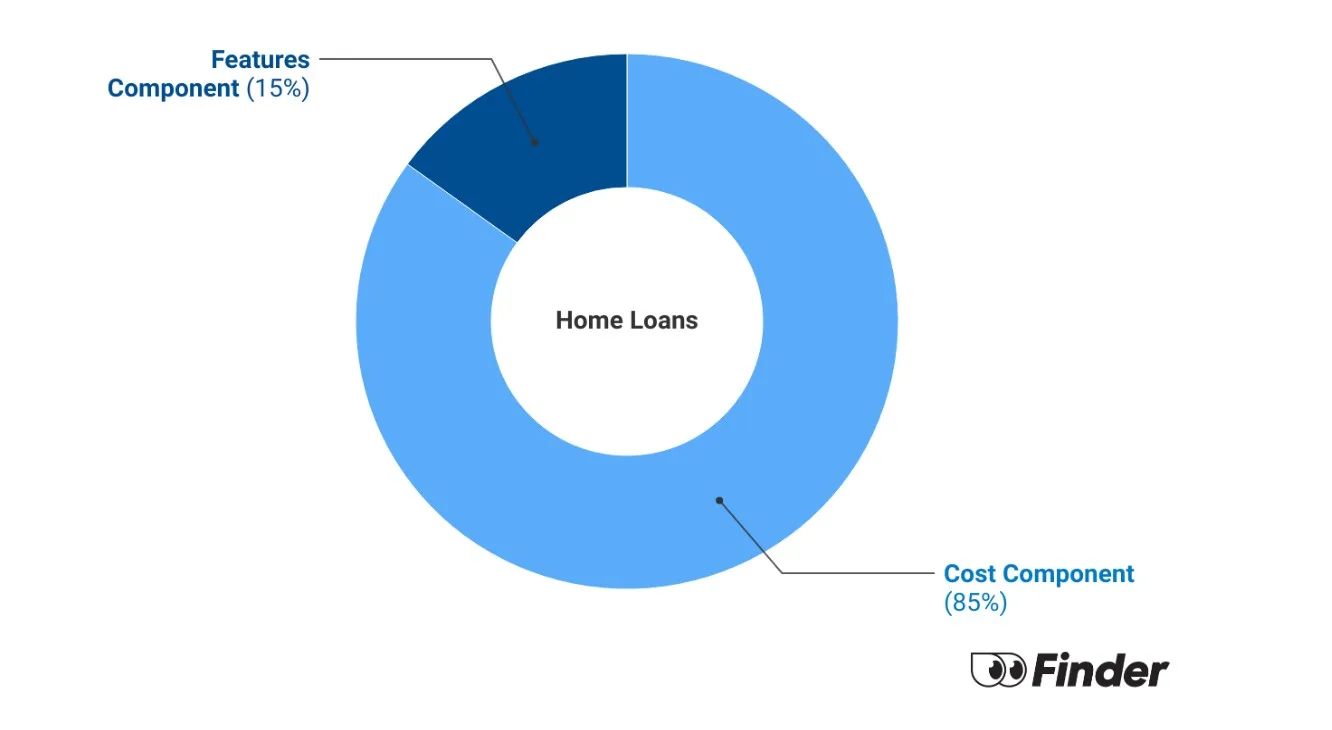
The Finder Score crunches 7,000 home loans across 120+ lenders. It takes into account the product's interest rate, fees and features, as well as the type of loan eg investor, variable, fixed rate - this gives you a simple score out of 10.
To provide a Score, we compare like-for-like loans. So if you're comparing the best home loans for cashback, you can see how each home loan stacks up against other home loans with the same borrower type, rate type and repayment type. We also take into consideration the amount of cashback offered when calculating the Score so you can tell if it's really worth it.
Whether you're eyeing a reno or consolidating debt, here's what you need to know about home equity loans (without the financial fluff).
Work out how much you need to earn to buy a house in any Australian suburb.
How to accurately estimate the cost of building your own house.
Your guide to home loan LVRs and how you can determine your loan to value ratio.
Historic data and expert opinion suggests that even in the event of a recession, Australian property prices might actually rise.
Depending on your individual circumstances and financial situation, negative gearing could be a sensible investment strategy for you.
Mortgage House provides numerous home loan options, including home loans for first home buyers, refinancing, investment and construction.
Find out whether you can get a home loan application approved by a lender if you have bad credit.
Find a great deal on a variable interest rate home loan from lenders large and small. Start comparing and saving today.
Learn how to compare rates to find the best home loan and start saving money on your mortgage today.

I am retired on a defined benefit fortnightly pension. I own my own home & car. They can be used for security. I need a loan of $20000. Can you advise of loan type i should apply for and list those that offer this
Hi Julie,
If you’re offering your home as security, you may be eligible for a home loan, which will be a much lower interest rate than a personal loan. Your best bet is to contact a finance broker or call your bank and see what options you might have available.
Best of luck!
I am currently on a disability pension. I am interested in trying to obtain a home loan of $120 000.00 to purchase my father’s house. The house is worth at least $200 000.00 -$240 000.00 but he is only wanting $140 000.00 as apart of a inheritance I would eventually receive when he passes. I have $20 000.00 as a deposit and I have 900+ credit rating. I can also show that I have paid rent to my father for over 4 + years of $400.00 per fortnight. Would I be eligable or if not how much would a approx need in a second 8ncome to be eligable
Hi Lauren,
It’s hard for me to say specifically what you’d be eligible for, as every lender has different criteria. Not all of them accept a disability pension as a form of income.
I suggest contacting some lenders before applying fully, or talking to a mortgage broker.
I am a 69y.o on disability support pension. My wife is a 66y.o on carer allowance and payment, making our joint income $1676.10 per fortnight. In addition I receive a small annuity from the UK each month, of around $50 and a UK military pension per month of about $400. Both of these fluctuate with the exchange rate. We would like to downsize. We currently have a mortgage with Homestart, which stands at $255045.72. Unfortunately I believe we were slightly mislead as to the flexibility of this mortgage when we took it on almost 6 years ago, and it is now impeding our ability to downsize, or in fact do almost anything we need to do. Throughout the entire mortgage period we have never been missed, or been late with, any payment. prior to that we rented for over 8 years, and, again never missed a payment, on, what was then, a very high rental rate.
My wife and I contacted several banks and financial institutions and were told either that our ages were a barrier, or that they didn’t accept applicants whose sole income was from centrelink. On a personal note,, with no supporting evidence feels this disgusts me. It is discriminatory and presumptive. We both have high credit ratings for a reason, we know how to handle our finances, and to assume that we are potential defaulters, based solely on our source of income, smacks of defamatory reasoning.
All besides the point, since our aim is to find someone who will base their decisions on facts, and not simple data averaging or preconceived ideas.
We are seeking either a mortgage, whereby we aim to sell our existing property, whose posted value, as of today,is between $430k – $489k and $550k. We would then seek to buy another, slightly smaller, and less expensive property in the same general area. From the sale we would repay the existing mortgage, hold $40k for costs and stamp duty, hopefully have $50k towards any necessary home upgrades, and a reliable car, and place the remainder as the deposit on the new dwelling. I calculate that this would be around $80k at the lower end price, or slightly over 20% of the typical property price that we are looking for.
Our second option would be what I believe is called a reverse mortgage, which I admit I don’t understand very well. In this case I would hope that we can gain access to $50k. This would allow us to replace our old fencing, upgrade our solar panels and purchase a reliable vehicle.
Hopefully this is enough information to help you with some advice.
Hi Alan,
I’m sorry to hear about the experience you’ve been having. Unfortunately, as a comparison site, we’re not really in a position to offer any kind of advice.
You’d probably benefit from talking to a mortgage broker who can work through your specific set of circumstances with you and offer some potential solutions.
Regards,
Rebecca
Me and my wife and son we all on a Dissabilty Pension can same help us with home loans we looking at $500,000 for home and land packages
Hi Giovanni,
Given that your borrowing situation is a little complicated, you might want to contact a mortgage broker to get some personalized advice and a clear idea of what your options are. They can help you look for loans and lenders that match your requirements.
All the best,
Richard
My son is on a disability pension and he works, I’m on a cares pension and I work too. Is my son able to get a home loan as he’s never owned a house before.
Hi Jill,
Yes. There are lenders that may consider your son’s disability pension to be a valid form of income.
Most lenders will review your application on a case-by-case basis. His eligibility for a home loan will also depend on the amount of income he receives and how much of this can be used to service a loan. Other factors including his age, assets, and debts will be assessed.
A mortgage broker might be able to help you too.
Kind regards,
Richard