Looking for other options? Check out these similar products.
How we picked theseThe best balance transfer offers in October 2026
The longest balance transfer offer on the market this month is the Latitude Gem Visa, a Finder exclusive with a market-leading 0% for 27 months (plus a 3% balance transfer fee). It's closely followed by ANZ's Low Rate Credit Card (0% for 26 months plus a 3% balance transfer fee) and NAB's Low Rate card, which also comes with a 0% balance transfer rate for 26 months and a 3% balance transfer fee. Beyond that, only a few cards offer 0% 25 or 24 months.
Updated October 2026 by Finder's senior money editor, Richard Whitten.
Want more great credit cards? Check out all the Finder Credit Card Award Winners.
What is a balance transfer credit card?
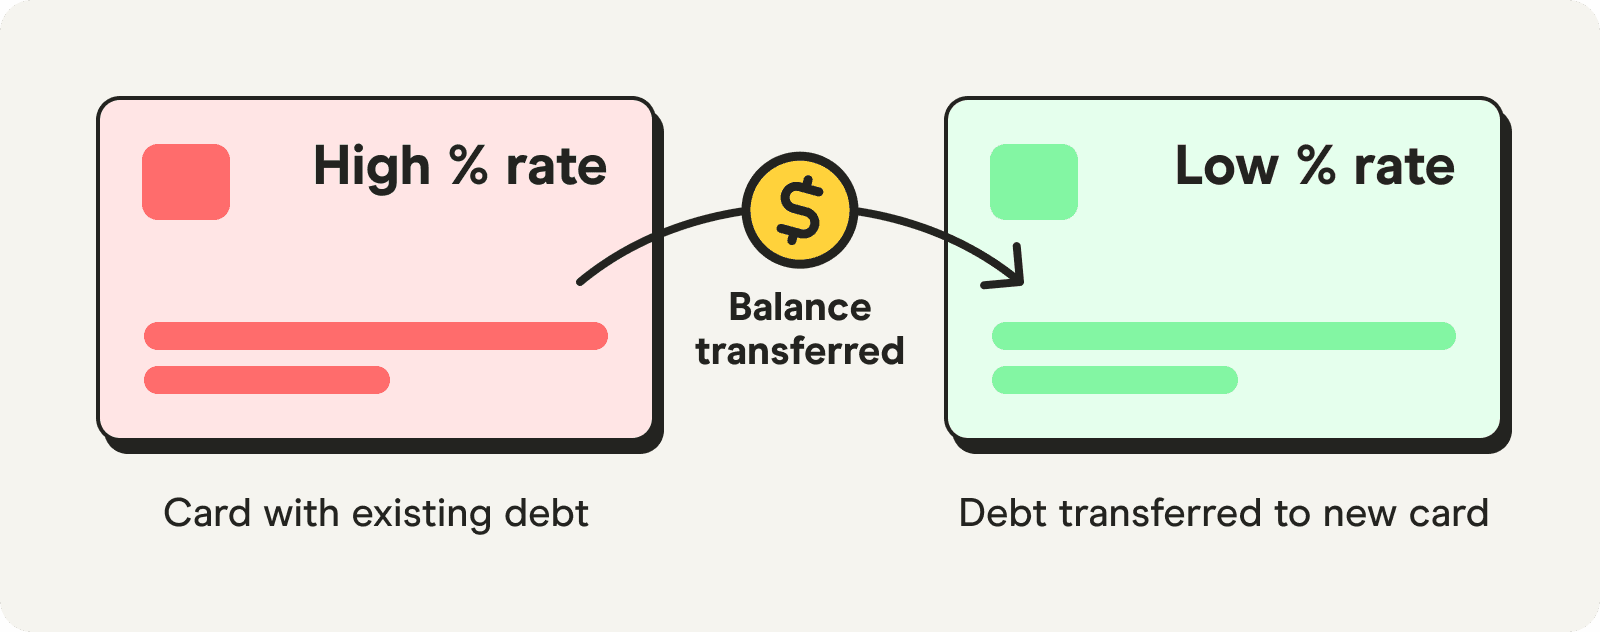
A balance transfer is a credit card offer for people with unpaid credit card debts.
You can move the debt onto a new credit card via a balance transfer. The best balance transfer offers let you repay your balance with a special 0% rate. Most cards give you 12 months but some go up to 24 months or more.
This lets you pay off your debt without having to worry about super high interest charges. It's a debt-busting lifeline for people with big credit card debts.
The key thing is to make sure you pay it off and avoid spending too much on the new card.
Sounds great! What's the catch?
There's no catch. But you need to be aware of a few possible costs:
- Your new card provider may charge a one-off balance transfer fee of 1–3% of your balance.
- At the end of the balance transfer period the 0% interest rate reverts to a much higher rate (often above 20%). Pay it off before this happens.
- You will get charged interest on any new spending you do on the card. This is called the purchase rate.
Must read: The key to making a balance transfer work
2. Figure out a realistic amount you repay each month (and stick to it).
3. Close the old credit card or cards (the ones you used to rack up the debt). That way you won't get into any future trouble.
4. Avoid over-spending on the new card. If possible, just pay off the balance and use a debit card for your spending until the debt is paid.
How to compare balance transfer credit cards
- Look for a long offer. The longer the offer term, the more time you'll have to pay off your debt for a low or 0% rate. So compare credit cards carefully.
- Watch out for the transfer fee. Most cards charge a balance transfer fee. This one-off fee is 1% to 3% of the amount you transfer.
- Find a 0% balance transfer rate. The best balance transfer credit cards in Australia offer 0% interest for the promotional period.
- Take note of the revert rate. If you haven't paid off the balance transfer by the end of the offer period, the higher revert interest rate will be charged on your leftover debt.
- Check the eligibility. You can usually transfer a balance from Australian-issued cards or accounts, as long as they are from a different issuer. There are now no credit card providers in Australia that accept personal loan debt on a balance transfer.
- Know your limits. On some cards you can only transfer up to a percentage of your approved credit limit (usually 70% - 100%). You can see Finder's guide to balance transfer limits for more information.
Want to see how much you could save? Put your balance and interest rate into the balance transfer table's calculator, or use Finder's credit card repayment calculator to help set your repayment goals.
Pros and cons of balance transfer credit cards
Pros
- Save on interest costs. You can transfer your existing balance to a new card and get a low or 0% interest rate for a while. This will almost always be lower than the interest rate you're currently paying.
- Pay off debt faster. By not paying interest you should be able to get rid of your balance a lot faster.
- Simplify your payments. If you have several debts, you can use a balance transfer card to combine them so you only have to keep track of one credit card bill. This also saves you money on card fees.
- Perks and extras. If you want to use the card after you have paid off your balance, perks like credit card travel insurance or rewards could help you get more value out of the card.
Cons
- Balance transfer fee. This one-time fee can range from 1% to 3% of your balance transfer amount, when it applies. That would mean a fee of $100 to $300 on a $10,000 debt.
- Revert rate. If you don't pay off your whole balance transfer during the introductory period, this is the interest rate you'll pay on the remaining balance.
- Balance transfer limits. Depending on the card and how much you want to transfer, you may not be able to move it all onto the new card. You could still be saving money.
- Credit score impact. Every time you apply for a new credit card, an enquiry is recorded on your credit report. If you already have a weak credit score, this could lower it further, temporarily.
Is a balance transfer credit card right for me?
A balance transfer credit card is really useful if you are struggling with unpaid credit card debt - and interest - from one or multiple cards.
Still not sure if a balance transfer card is right for you? Ask yourself these questions first.
- Is there a way I can pay off my balance without getting a new card?
- Can I afford the fees that come with the new card?
- Will I be able to pay my balance off before the 0% period ends?
- Am I eligible for this credit card? Is my application likely to be rejected?
Check your credit score before you apply for a card.
"I got into some credit card trouble in my early twenties. I was stuck with over $5,000 of debt on a Commonwealth Bank credit card that I should never have taken out. That might not seem like a lot to some people, but I was struggling financially at the time, and the interest was crippling. I took out an ANZ balance transfer card and was able to get zero interest for 18 months, which gave me a lot more space to pay the thing off."
What's the best way to pay off a balance transfer credit card?
- Make a plan. Look at your budget and see how much you spend and save each month. Figure out how much you can use to pay off the balance. If there's not much money, try to find ways to cut back, like cutting out subscriptions or unnecessary expenses. Use the savings to pay down your balance.
- Set up auto-pay. Your bank should offer you a way to automatically set up a monthly card payment. This means you'll never miss a card payment, as long as there's money in your transaction account.
- Do the maths. Take your unpaid balance and divide it by the number of months on your 0% balance transfer offer. Let's say you have a $4,000 balance to repay and a 26-month balance transfer offer. You need to repay $154 a month to pay it off on time.
- Avoid getting into further debt. Recognise the money mistakes that got you into trouble in the first place. Try not to spend wildly on the new credit card (if possible, don't use it for new spending it all and just pay off the balance).
Set yourself up for success by setting up direct debit payments from your bank account each month. Watch as your balance goes down, and make sure it's paid off before the balance transfer period ends.
How long will it take Aussies to pay off their credit card debt?
| Length of time | Percentage |
|---|---|
| 3-4 years | 2% |
| 5 or more years | 3% |
| 1-2 years | 6% |
| 7-12 months | 9% |
| 1-6 months | 16% |
Struggling with debt? Help is available
It's easy to get into trouble with a credit card. Sometimes it's easy to sort this out with some careful budgeting and a balance transfer.
But if you've got multiple, serious debts, bad credit history, or other issues that seem to make it impossible to get back on track financially, it's much harder.
- Hardship support is available. If you're struggling, talk to your bank, card company, utility or other service provider. These companies have hardship support schemes in place. You might be able to get extra time to pay a bill, or a pause on loan repayment.
- Free financial counselling. You can also call the National Debt Helpline on 1800 007 007 and get free financial counselling and support.
Frequently asked questions
-
Right now, the longest balance transfer offer is 0% for 27 months. With the cards listed below, you can transfer your balance and get charged no interest while you pay it off for over 2 years.
- Latitude Gem Visa - Exclusive Offer - 27 months (with 3% BT fee)
- ANZ Low Rate Credit Card - 26 months (with 3% BT fee)
- NAB Low Rate Credit Card - 26 months (with 3% BT fee)
- Latitude GO Mastercard - 26 months (with 3% BT fee)
- Bankwest Breeze Platinum Mastercard - 24 months (with 3% BT fee)
- Virgin Australia Velocity Flyer Card - Balance Transfer Offer - 24 months (with 3% BT fee)
- Virgin Money Anytime Rewards Credit Card - Balance Transfer Offer - 24 months (with 3% BT fee)
-
There is no set maximum amount of times you can transfer a balance between credit cards. However, you should factor in any balance transfer fees, the enquiries on your credit report and your chance of being approved for new cards with different banks. Ideally, you should focus on paying it back in full and eliminating the need for multiple transfers.
-
The ANZ Low Rate is the winner of the 2026 Finder Balance Transfer Credit Card Award. This card had the longest 0% balance transfer offer on the market plus no annual fee in the first year. The clear winner.
These balance transfer cards were highly commended in 2026:
- The Westpac Low Rate
- The St.George Rainbow Vertigo
- The Heritage Bank Gold Low Rate (no longer available)
- The Community First Low Rate
- The Easy Street Low Rate Visa
-
The number of balances you can transfer depends on the provider and the offer but typically you'll be able to move debt from 1 to 3 eligible accounts. If you want to use a balance transfer credit card to consolidate debts, check the offer details or contact the provider to find out exactly how many balances you'll be able to transfer.
-
Unfortunately, no. Balance transfer offers are only for new customers, meaning you'll have to open a card with a different bank or card company. This also goes for cards within the same group. For example, St.George, Bank of Melbourne and BankSA are all part of Westpac group, so you couldn't transfer a balance between any of these institutions.
-
When used correctly, a balance transfer credit card can help you repay your debt and improve your credit score in the long-term. But applying for a new credit card leaves a hard enquiry on your credit report (and may decrease your score for a month or two).
Try to avoid applying for multiple cards. This will lower your credit score. Missing repayments on the balance transfer card will also hurt your credit score.
-
After the introductory period ends, the 0% interest rate ends too. If there's any debt left over, it will start to be charged interest at the revert rate.
This rate is high, often around 20%. It's higher than the purchase rate you get charged on new card spending.
If you haven't paid your balance off by the end of balance transfer period you could end up getting charged more interest than you were on your old card.
This is why it's so important to plan your repayments and pay off as much of your debt as possible during the introductory period
-
A balance transfer fee is a one-time charge that may apply when you move your debt to a new card. It's typically worth 1-3% of the balance transfer amount, but not all providers charge a balance transfer fee.
To give you an idea of the cost, transferring $5,000 onto a card with a 1.5% balance transfer fee would add $75 to the balance.
-
Unless the card offers an interest-free period for the purchases, you'll be charged interest on them. So, you'd need to make sure you could repay your purchases and the balance transfer debt. Otherwise, you'll waste your 0% balance transfer offer.
-
When transfering an existing balance to a new card, it's your responsibility to contact your provider and close the old account. If you don't, you could end up paying account costs for a card you're not using - or worse, rack up debts on both cards. Before you close the card, make sure the balance is completely transferred or paid in full and move any regular payments such as (direct debits) to another account.
-
The Commonwealth Bank stopped accepting balance transfer applications in December 2023. This means you can no longer move an unpaid balance from another card onto a new Commonwealth Bank credit card.
However, you can still transfer your Commonwealth Bank credit card balance to another bank.
Finder Scores: What they mean
- 9+ Excellent - These cards offer the longest 0% interest periods, lowest balance transfer fees, and competitive revert rates for maximum savings.
- 7+ Great - Tackle debt with generous interest-free periods, reasonable balance transfer fees, and potential for additional perks.
- 5+ Standard - Reduce interest costs with reasonable interest-free periods and balance transfer fees.
- Less than 5 – Basic - These are generally cards aimed as general audiences which include a balance transfer feature.
-
Let's face it, the average person doesn't spend all day comparing credit cards. But we do. That's why we developed the Finder Score.
It's a quick, easy way you can see how one credit card compares to others on the market.
Every month we:
- Analyse 80+ credit cards with balance transfer offers.
- Assess seven features of each card and give each component a rating.
- Combine the ratings via a weighted methodology to decide the Finder Score.
The Finder Score methodology is designed by our insights and editorial team. We review products objectively. Commercial partnerships do not affect the scores.
Remember that Finder Score is just one factor to consider. Look at other aspects like fees, features, benefits and risks to make sure a product is suitable for you. Double-check details that matter to you before applying or buying.
-
Feature Definition Assessment Weight Balance Transfer Period Length of the interest-free period on transferred balances (in months) Longer periods earn more points, up to the market maximum 40% Balance Transfer Fee Percentage charged on the transferred balance Lower fees score higher. 0% fee receives the maximum points 20% Balance Transfer Rate Interest rate on transferred balances during the introductory period Lower rates score higher. 0% rate receives the maximum points 15% First-Year Fee Annual fee charged in the first year of ownership Lower fees score higher. $0 fee receives the maximum points 12% Ongoing Annual Fee Annual fee charged from the second year onwards Lower fees score higher. $0 fee receives the maximum points 8% Revert Rate Interest rate applied to remaining balance after the introductory period Lower rates score higher 2.5% Purchase Rate Interest rate on new purchases Lower rates score higher 2.5%
-
Finder writers are subject matter experts and use primary sources, in-depth research and interviews with other experts to ensure you're getting accurate, up-to-date information. Articles are fact checked in line with our editorial guidelines.
Richard Whitten is Finder’s Senior Money Editor, with over eight years of experience in home loans, property, credit cards and personal finance. His insights appear in top media outlets like Yahoo Finance, Money Magazine, and the Herald Sun, and he frequently offers expert commentary on television and radio, helping Australians navigate mortgages and property ownership. Richard started his career in education and textbook publishing in South Korea. He holds multiple industry certifications, including a Certificate IV in Mortgage Broking (RG 206) and Tier 1 and Tier 2 certifications (RG 146), as well as a Bachelor of Education from the University of Sydney and a Graduate Certificate in Communications from Deakin University. See full bio
- Home loans
- Credit cards
- Personal finance
- Money-saving tips
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
Read more on Credit Cards
-
Best international credit cards November 2026
Find credit cards that make international spending cheaper with 0% international transaction fees.
-
Buying gift cards with a credit card
Paying for gift cards is usually treated as a cash advance on your credit card, so what does that mean for your Christmas shopping budget?
-
Credit cards for pensioners and retirees
Learn how to apply for a credit card when you're retired or on a pension and compare cards to find one that suits your needs.
-
Instant approval credit cards
Compare credit cards that give you an outcome within 60 seconds of when you submit your application online and find out how to increase your chances of getting this type of "instant" credit card approval.
-
Cashback credit cards — up to $500 back
Get a percentage of your spend back, gift cards or vouchers with a cashback credit card. Find out more and compare current offers in our guide.
-
Best Qantas credit cards
Compare the best Qantas frequent flyer credit cards based on bonus point offers, points per $1 spent, rates, fees and other features so you can find a card that works for you.
-
How your credit card limit is calculated
Learn what information the bank uses to determine your credit limit and the steps you need to take before you request a limit increase.
-
Best Velocity credit cards
Check out bonus point offers and travel perks such as lounge access and complimentary insurance with these Velocity Frequent Flyer credit cards.
-
Credit cards for people on Centrelink benefits
Find out what your credit card options are, whether you're employed casually or get Centrelink payments as your main source of income.
-
No international transaction fee credit cards
Find out how you can keep your overseas spending costs down by comparing credit cards with no foreign transaction fees and no currency conversion fees.
