Key takeaways
- Agreed value income protection is no longer available for new policies in Australia.
- APRA mandated that new policies base payouts on your income 12 months before a claim.
- Compare income protection focusing on benefit amount, waiting periods and cost to get a better policy for you.
Income protection insurance has long been a valuable safety net for Australians, providing financial support in the event of illness or injury. One type of income protection, agreed value, was particularly popular for its guaranteed benefit amount. However, due to industry changes and regulatory interventions, agreed value income protection is no longer available for new policies.
Understanding Agreed Value
With agreed value income protection, policyholders locked in a specific benefit amount when they first purchased the policy. This meant that regardless of any income fluctuations after the initial purchase, the benefit remained fixed. This was particularly attractive to those with variable incomes, such as self-employed individuals or those with commission-based roles.
Regulatory Intervention
In 2020, the Australian Prudential Regulation Authority (APRA) intervened in the life insurance market due to concerns about the sustainability of individual disability income insurance (IDII) policies. APRA identified several issues with agreed value policies, including:
- Moral Hazard: The potential for policyholders to have less motivation to return to work due to the guaranteed benefit.
- Unsustainable Costs: The risk of insurers incurring significant losses if policyholders' incomes declined after purchasing the policy.
- Deviation from the Principle of Indemnity: Agreed value policies could violate the principle of indemnity, where benefits should not exceed economic loss.
APRA's Mandated Changes
To address these concerns, APRA required insurance companies to:
- Cease Offering Agreed Value Policies: New policies must be issued on an indemnity basis.
- Base Cover on Income at Time of Claim: Benefit amounts should be linked to income within the 12 months prior to making a claim.
- Limit Income Replacement Ratios: Benefits should be capped at a certain percentage of earnings.
- Restrict Guaranteed Renewability: Policies should have a shorter guaranteed renewal period.
Impact on Policyholders
The transition from agreed value to indemnity value has significant implications for policyholders. Those with existing agreed value policies have been able to maintain their coverage, but new buyers are limited to indemnity value options.
Key Considerations
When comparing income protection policies, it's essential to evaluate the following factors:
- Benefit Amount: Determine the level of coverage you need to adequately support your lifestyle and financial obligations.
- Waiting Period: Consider the length of time you're willing to wait before benefits begin.
- Benefit Period: Evaluate how long you want the benefits to continue.
- Exclusions and Limitations: Understand any conditions that might affect your eligibility for benefits.
- Premium Costs: Compare premiums from different insurers to find the best value for your needs.
Comparing Income Protection Policies
To find the right income protection policy for you, use our comparison tool to compare quotes from leading insurers. You can also consult with a financial advisor for personalized guidance.
Compare direct brands for income protection
Looking for other options? Check out these similar products.
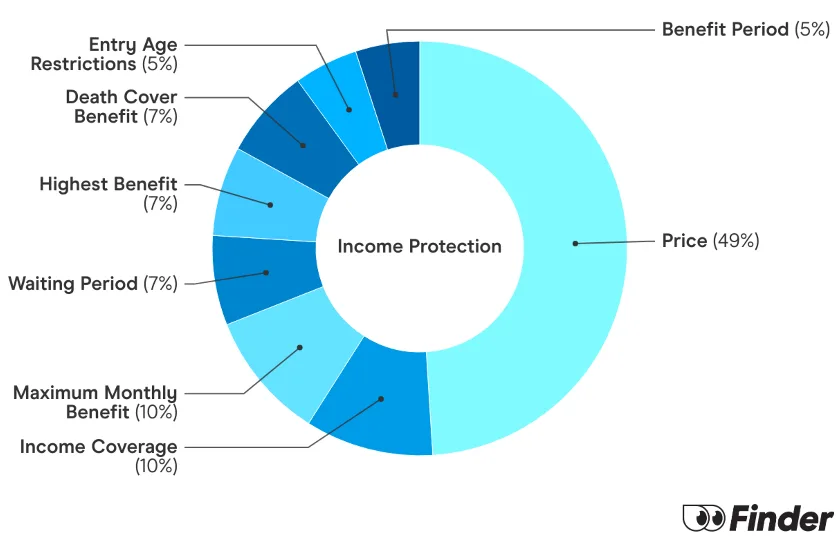
How we picked theseFinder Score - Income Protection
Income Protection is a little complicated and a lot overwhelming. That's why we made the Finder Score, to make it easier to compare Life Insurance products against each other. Our experts analysed over 21 products and gave each one a score rank out of 10, to make it easier to compare Income Protection products against each other.
But a higher score doesn't always mean a product is better for you. Your situation is unique, so your policy choice will be too. Don't think of Finder Score as the final word, but as a good place to start your life insurance comparison.
Speak to an insurance specialist to help you find personalised cover
Frequently Asked Questions
-
Indemnity value income protection is the standard type of income protection insurance now available in Australia. It bases your payout amount on your actual income in the 12 months prior to you making a claim. This means the benefit you receive reflects your income at the time of disability not a pre-determined amount from when you purchased the policy.
-
When you make a claim under an indemnity policy, the insurer will typically look at your earnings in the 12 months immediately before you became unable to work. This can include your salary or wages as well as other taxable income such as commissions or regular bonuses. You will need to provide evidence like payslips tax returns or financial statements to support your income claim.
-
If you held an agreed value income protection policy before the regulatory changes in 2020 you are generally able to maintain your existing coverage. However you cannot take out a new agreed value policy or switch to another agreed value product if you did not have one previously. Be aware that making changes to your existing policy might sometimes lead to it being reissued under indemnity terms so it is wise to check with your insurer or a financial advisor before making any changes.
-
To make an income protection claim under an indemnity policy you will typically need to provide documents that verify your income history, medical evidence of your illness or injury and details about your occupation. Income verification usually includes payslips tax returns, profit and loss statements or other financial records from the 12 months before your claim. The specific documents required may vary between insurers.
-
With an indemnity policy, if your income decreases significantly after you take out the policy your benefit payout will be based on your lower income at the time of claim. Conversely if your income increases you may be able to adjust your cover to reflect your higher earnings by contacting your insurer. It is important to regularly review your policy to ensure it aligns with your current financial situation.
-
Yes many Australians can obtain income protection insurance through their superannuation fund. This can offer potential tax benefits and convenience as premiums may be paid directly from your super balance. However, cover arranged through superannuation may have different terms, conditions or limitations compared to policies held outside super so it is important to compare these options carefully.
-
Yes there are several reasons an income protection claim might be denied. These can include not accurately disclosing your medical history or occupation when applying, making a claim for a condition that is an exclusion on your policy not meeting the waiting period requirements or if your disability does not meet the policy's definition of total or partial disablement. Always read your Product Disclosure Statement carefully.
-
Finder writers are subject matter experts and use primary sources, in-depth research and interviews with other experts to ensure you're getting accurate, up-to-date information. Articles are fact checked in line with our editorial guidelines.
A seasoned journalist with over 10 years of experience in news, politics and finance reporting, Tim has previously held roles at the ABC, SBS and Fairfax Media. Tim’s expert insights have been quoted in The Australian, The Daily Telegraph, The Courier Mail and more. He regularly appears on TV and radio, and has been interviewed on 7 News, Sunrise, SBS News, ABC Local, 3AW and 5AA. Tim is passionate about simplifying complex insurance topics for Australian consumers. He holds a Bachelor of Arts (Politics) from Macquarie University and a Tier 1 General Insurance (General Advice) certification, which meets the requirements of ASIC Regulatory Guide 146 (RG146). If you’re interested in a media interview with Tim, please reach out to our PR team at aupr@finder.com. See full bio
- Personal finance
- Financial comparison
- Health insurance
- General insurance
- Life insurance
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
More guides on Finder
-
Real Income Protection Insurance review
Real Income Protection Insurance has similar cover to many popular providers. However, optional extras are limited.
-
Cost of living comparison
How much could you save if you lived in a different city in Australia? Let's find out.
-
Aspect income protection insurance review
Cover up to 85% of your salary with one of Aspect's flexible income protection policies.
-
TAL Income Protection Insurance review
Learn the built-in benefits of TAL income protection to understand how it could work for you. Compare features and get a quote today.
-
Sick leave Australia: What you’re entitled to and when
Find out why income protection is an important tool to combine with your entitled sick leave.
-
Income protection with pre-existing conditions – yes, you can get it.
Find out how you can benefit from income protection even if you have a pre-existing condition, and which providers will cover you.
-
Suncorp Income Protection Insurance Review
Receive income cover for illness or injury with Suncorp Income Protection.
-
Redundancy and unemployment insurance
Most providers no longer offer unemployment insurance in Australia if you're made redundant.
-
Rest Super income protection
Rest Super has grown to become one of Australia's largest super funds with a range of protection options for members including life cover, TPD cover and long term income protection.
-
Best income protection insurance Australia 2026
Looking for the best income protection insurance but not exactly sure where to start? Compare the Finder Awards 2025 insurance winners.