You pay the same price as buying directly from the income protection insurer.
We're not owned by an insurer (unlike other comparison sites).
We don't ask for your phone or email.
We've done 100+ hours of policy research to help you understand what you're comparing.
Looking for other options? Check out these similar products.
How we picked theseKey takeaways
- Income protection typically covers up to 70% of pre-tax income with monthly benefits around $10,000.
- A longer waiting period for your policy often lowers premiums, but ensure you have sufficient savings.
- Direct or retail policies often offer more comprehensive features than basic superannuation cover.
The lowdown on Finder Score
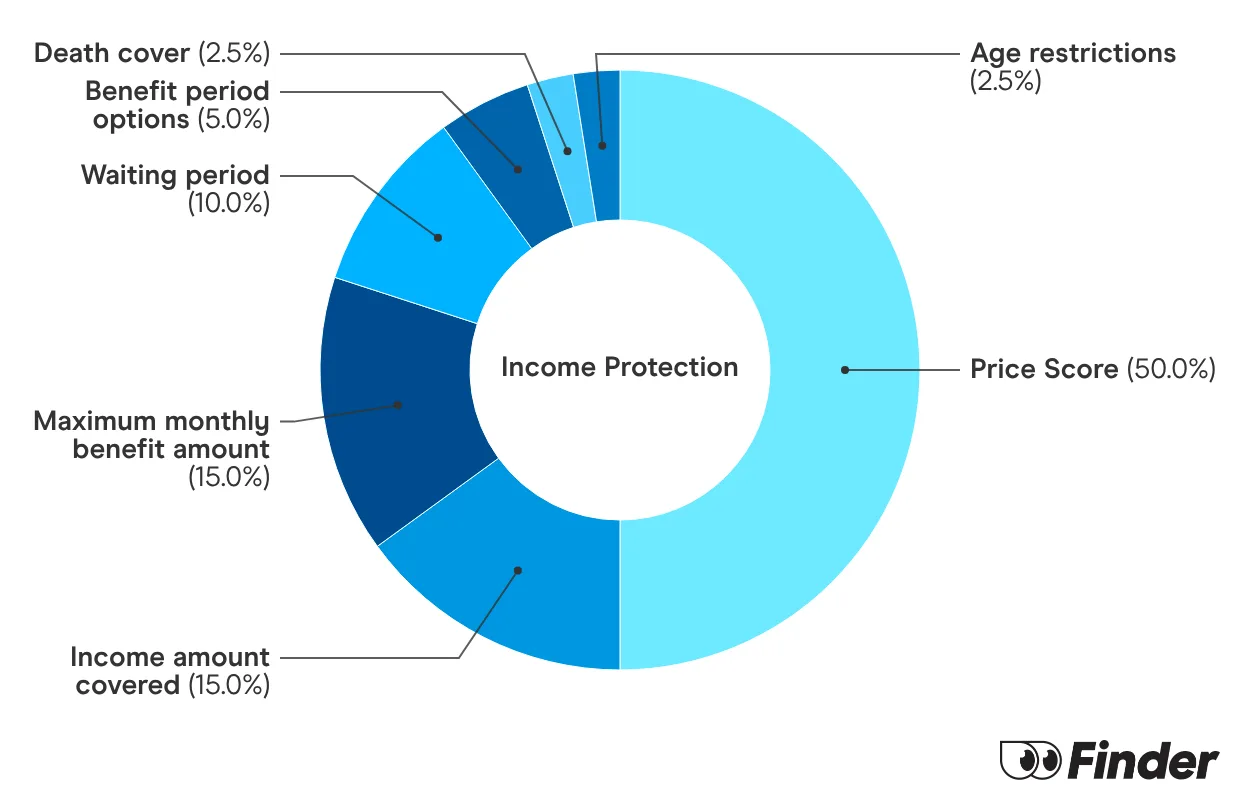
We assess 12 products and score each product a score out of 10, based on their pricing and key features.
The higher the Finder Score the better the product. We assess products for their pricing across multiple personas and eight features.
The Finder Score methodology is designed by our Insights team and reviewed by our editorial team. We review the products objectively. Commercial partnerships do not affect the scores.
Remember that Finder Score is just one factor to consider. Look at other aspects like fees, features, benefits and risks to make sure a product is suitable for you. Double-check details that matter to you before applying or buying.
-
Income protection pricing personas · dw:p4R6i Age Gender Occupation Smoker/Non Smoker 35 Female Carpenter Non Smoker 45 Female Accountant Non Smoker 35 Female Accountant Non Smoker 45 Female Carpenter Non Smoker 35 Female Carpenter Smoker 45 Female Accountant Smoker 35 Female Accountant Smoker 45 Female Carpenter Smoker 35 Male Carpenter Non Smoker 45 Male Accountant Non Smoker 35 Male Accountant Non Smoker 45 Male Carpenter Non Smoker 35 Male Carpenter Smoker 45 Male Accountant Smoker 35 Male Accountant Smoker 45 Male Carpenter Smoker -
Finder Score weightings - income protection · dw:agmbK Feature Assessment Weight Price Pricing is averaged across 16 personas 49% Income Coverage Products that offer higher percentage of income coverage get more points 10% Maximum Monthly Benefit Products are assigned scores based on the maximum monthly dollar value coverage 10% Waiting Period Products will lower minimum waiting times are awarded more points 7% Entry Age Restrictions Products are assigned points based on their age restrictions, with higher age limits getting more points 5% Highest Benefit Products are assigned points based on the duration of coverage offered 7% Death Cover Benefit Products offering this feature are assigned 10 points 7% Benefit Period Products are offered points based on the flexibility around benefit periods offered 5%
Speak to an insurance specialist to help you find personalised cover
What is income protection insurance?
Income protection insurance is a policy that pays a portion of your lost income if you are unable to work because of a disability, illness or injury. This provides a crucial financial safety net, helping you cover essential bills and ongoing expenses so you can focus on your recovery without financial stress.
Most insurers will pay up to 70% of your pre-tax income. They'll also set a maximum benefit, usually around $10,000 monthly. The payouts from income protection can help you meet regular expenses, such as your mortgage or rent and groceries. It can also maintain your family's lifestyle while you focus on your recovery.
How does income protection insurance work?
With income protection, you get an ongoing cash benefit after a successful claim. It lasts until one of the following occurs:
- You can return to work
- Your benefit period ends
- You reach an age when you can no longer renew your policy
The benefit period is the maximum amount of time you can receive payments. In most cases, this is for 1, 2 or 5 years. Some insurers offer a benefit period until the age of 65. These policies will cost more.
You can only claim income protection after you've passed the waiting period stated in your policy. It starts from the day you file your claim and it can be 14, 28, 60 or 90 days.
Tip: The longer your waiting period, the cheaper your policy will be. However, choose with care as you'll need to have enough money to support yourself for the duration of your waiting period.
-
- Expiry age. This is the age at which you will no longer be able to renew your policy. Most insurers set this as 65 years of age.
- Partial disability benefit cover. This add-on lets you claim a portion of your insurance benefit if you can return to work at a reduced capacity – for example, on a part-time basis. You can be paid this until you return to work fully (or your benefit period ends).
- Premium pause. Some policies let you stop paying your premiums – for up to 12 months – if you take extended leave. This could be for parental leave, compassionate leave or full-time study.
- Stepped or level premiums. You may be able to choose between stepped and level premiums. A stepped premium starts off cheaper but increases over time. A level premium starts out more expensive than stepped but won't go up over time.
Pros and cons of income protection
Weighing up the pros and cons of income protection is a helpful way of working out if it's right for you. Take a look below.
Pros
- Peace of mind. Money is one of the major causes of stress in life. Income protection can't guarantee all your money worries will go away, but it can take care of one of our biggest concerns: what happens if I can't work? It lets you focus on getting better, not how you'll pay your next bill.
- Short-term help that stops long-term problems. Income protection is for those scary times when you're temporarily unable to work. It's short-term financial help that ensures your money worries don't become a long-term problem. If you can rely on income protection, you don't need to worry about alternative ways of paying your bills, like selling your car, picking up a second job when you can return to work, or relying on high-interest loans.
- Easy to claim. You don't need to prove permanent disability to work; just that you're temporarily unable to perform your duties.
- Good for small business owners. If you run your own business, income protection insurance is very helpful security if an illness or injury strikes and stops you from working.
Cons
- Can be trickier if you have a pre-existing medical condition. Sometimes it can cost you more if you have a pre-existing medical condition and in some cases you won't be covered if you need to take time off due to that.
- More expensive for different occupations. You'll likely have to pay a little more if you work in a high-risk job where injuries are more likely to occur.
- Waiting periods. Income protection policies generally have a waiting period - usually around 30 - 90 days - before it begins to pay you, so you may have to fall back on sick pay until the waiting period is over.
Here's what some experts had to say
"While it's counterintuitive, you'll want to consider insurance when you're in tip-top shape. This is absolutely a worthwhile investment of your time and helps provide a safety net... lock it in early to get better terms if you can. If you wait and get your cover at a later date, you might find the specific condition you've since had is excluded from your policy."
"No one is ever really prepared for life's harsh surprises, but the right income protection insurance can help soften the blow during a tough time for your family: financially, emotionally and physically while you're on a claim."
"There's a lot more to finding the right cover than simply looking for the cheapest deal. Ultimately, you get what you pay for with income protection. In my view, policies held in super are rarely worth it in the long run. Going directly to an insurer or a broker is the pathway to a more comprehensive policy."
3 ways to buy income protection insurance

Direct
Do some research and buy directly with an insurer.

Retail
Seek advice from a broker who'll build you a policy.

Super
Get basic cover in your super fund.
How much does income protection cost?
We gathered quotes from a selection of products using the criteria below to give an indication of price.
Remember, price is just one part of the picture. Consider other factors such as fees, features, benefits, risks and overall suitability for your needs. Always review the details that matter most to you before making a final decision.
Smoker
Looking for other options? Check out these similar products.
How we picked theseNon-smoker
Looking for other options? Check out these similar products.
How we picked theseLearn more about income protection insurance
Our income protection insurance guides can help you compare and understand what cover option is right for you.
Some more helpful stuff

Income protection insurance: A beginner's guide
Learn the key points about how income protection works.

How does my job affect my income protection?
Tradies are well aware of the dangers of their work. Find out how insurers see things.

Is income protection insurance tax-deductible?
Here's why income protection is often (but not always) tax deductible.

Is income protection worth it?
A balanced look at how income protection can protect you.
The latest income protection deals and discounts
We put together a list of deals and sign-up offers below to help you save:
Looking for other options? Check out these similar products.
How we picked theseRead our income protection reviews
Want to find out more about a specific insurer? We've reviewed over 20 of them. Here's a bunch of the most popular ones:
If the brand you're looking for isn't here, check out our directory.
Why you can trust Finder's income protection insurance experts
You pay nothing. Finder is free to use. And you pay the same as going direct. No markups, no hidden fees.
You save time. We spend 100s of hours researching income protection insurance so you can sort the gold from the junk faster.
You can trust us. We say it like it is. We aren't owned by an insurer and our opinions are our own.
Frequently asked questions
-
Income protection insurance has specific exclusions. It generally will not cover you for illnesses or injuries that are self-inflicted or result from criminal activities. While some policies offer partial redundancy cover this is usually a separate option and standard income protection does not cover job loss due to redundancy or resignation. Claims arising from pre-existing conditions may also be excluded or have modified terms depending on your policy.
-
Income protection and Total and Permanent Disability (TPD) insurance serve different purposes. Income protection pays a regular benefit to replace your income if you are temporarily unable to work due to illness or injury. It's designed to help you cover living expenses during a recovery period. TPD insurance however pays a lump sum benefit if you become totally and permanently disabled and are unlikely to ever work again in any occupation or your usual occupation depending on the policy definition.
-
Insurers classify occupations into different risk categories to determine your premium. They look at the nature of your work your specific duties and the associated risks of injury or illness. For example, a desk-based office worker might be considered a lower risk than someone in a heavy manual trade or a high-risk profession. This classification directly influences the cost of your policy with higher risk occupations typically attracting higher premiums.
-
Yes, many income protection policies in Australia now cover mental health conditions provided they are diagnosed by a medical professional and prevent you from working. However coverage can vary between insurers so it is important to check the PDS for any specific exclusions waiting periods or conditions related to mental health claims. Some policies might also require a longer waiting period for mental health related claims.
-
The main difference lies in how your monthly benefit is calculated at the time of claim. With an agreed value policy the payout amount is fixed at the time you take out the policy based on the income you declared then. With an indemnity value policy the payout is based on your income in the 12 months leading up to your claim. Agreed value policies can offer more certainty especially for those with fluctuating incomes but are often more expensive. Indemnity value policies may be cheaper but the actual payout can vary if your income has changed.
-
Yes, you can usually adjust various aspects of your income protection policy. This might include changing your benefit amount your waiting period or your benefit period. You may also be able to add or remove optional extras. Any changes however may affect your premiums and might require a new health assessment or underwriting by the insurer. It is a good idea to review your policy regularly to ensure it still meets your needs.
-
If you change jobs your income protection policy typically remains in force. However, you should notify your insurer as your new occupation might affect your occupation class and thus your premiums or cover terms. If you become unemployed your income protection policy usually continues but you may not be able to claim if you are not working at the time of illness or injury. Policies are designed to replace lost income from employment not provide unemployment benefits.
Sources
Gary Ross Hunter has over 6 years of expertise writing about insurance, including life, health, home, and car insurance. Having reviewed hundreds of product disclosure statements and published over 800 articles, he loves simplifying complex insurance topics for everyday readers. Gary has contributed to major outlets like Yahoo Finance, The Sydney Morning Herald, and news.com.au, and holds a Bachelor of Arts (Honours) in English Literature from the University of Glasgow, along with a Tier 2 General Advice certification, ensuring his work adheres to ASIC’s RG146 standards. See full bio
- Health, home, life, car, pet and travel insurance
- Managing the cost of living
- The lowdown on Finder Score
- Why compare income protection with Finder?
- Speak to an insurance specialist to help you find personalised cover
- What is income protection insurance?
- How does income protection insurance work?
- Pros and cons of income protection
- 3 ways to buy income protection insurance
- How much does income protection cost?
- Learn more about income protection insurance
- The latest income protection deals and discounts
- Read our income protection reviews
- Why you can trust Finder's income protection insurance experts
- Frequently asked questions
- Sources
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
Read more on Income Protection Insurance
-
Cost of living comparison
How much could you save if you lived in a different city in Australia? Let's find out.
-
Is income protection worth it?
Income protection can be a valuable form of cover for Australians when its features are fully understood.
-
AAMI Income Protection Review
Find out what is and isn't covered by AAMI Income Protection and how to apply.
-
Income protection for couplesÂ
Income protection for couples ensures your partner isn't hurt financially if you are temporarily unable to work due to illness or injury.
-
Income protection for over 60 in Australia
Find out why income protection is still useful if you're over 60, and compare cover.
-
Salary Continuance Insurance vs Income Protection
Salary continuance and income protection both serve to replace income in the event of injuries and illness. However, there are some key differences to know about.
-
Suncorp Income Protection Insurance Review
Receive income cover for illness or injury with Suncorp Income Protection.
-
Life insurance vs income protection insurance
Life insurance and income protection serve two different purposes but can both offer valuable cover alone and when combined.
-
Income protection and WorkCover: What’s the difference?
What are the key differences between income protection and WorkCover? If you already have WorkCover why would you still consider income protection?
-
Income protection insurance calculator
Find out how much your income protection insurance policy will pay out in the event of a claim. Receive quotes for income protection and apply securely.