These products offer great value, with a good score across both features and price.
7+
Great
These are competitive products, though they didn't quite get top scores.
5+
Standard
These products might offer less value or command a higher premium than others in the market.
0+
Basic
These products might only offer a basic set of features or aren't very competitive on price.
{"userFilters":[{"componentType":"MULTI-SELECT CHECKBOX","options":{"comparator":"contains","includeAllSelection":false,"defaultMatcher":"ANY","values":["8.95-10","6.95-8.94999","4.95-6.94999","0-4.94999"],"fields":[{"label":"[[FINDER_SCORE_BADGE|9+]] Excellent: 9+","value":"8.95-10","comparator":"range"},{"label":"[[FINDER_SCORE_BADGE|7+]] Great: 7+","value":"6.95-8.94999","comparator":"range"},{"label":"[[FINDER_SCORE_BADGE|5+]] Standard: 5+","value":"4.95-6.94999","comparator":"range"},{"label":"[[FINDER_SCORE_BADGE|0+]] Basic: 0+","value":"0-4.94999","comparator":"range"}]},"dataSelector":{"recordType":"PRODUCT","fieldCode":"FINDER_SCORE.FINDER_SCORE"},"dataType":"NUMBER","label":"Finder Score","queryParameter":"finderScore"},{"dataSelector":{"recordType":"UI_FILTER_COMPONENT","fieldCode":"SPECIAL_OFFERS"},"dataType":"BOOLEAN","label":"Special offers","componentType":"SpecialOffersFilter","config":{"VALUES":"1","fields":[{"value":"exclusive_only","label":"Finder Rewards & exclusives"},{"value":"all_offers_no_rewards","label":"All offers"}]},"options":{"comparator":"eq"},"queryParameter":"special-offers"},{"config":{},"dataSelector":{"recordType":"product","fieldCode":"GENERAL.PROVIDER_ID"},"dataType":"UUID","label":"Providers","order":100},{"config":{"MULTISELECT":true,"VALUES":"6 months,1 year,2 years,5 years,To the age of 65,To the age of 70,2 year benefit to age 70"},"dataSelector":{"recordType":"product","fieldCode":"FILTERS.BENEFIT_PERIOD_OPTIONS"},"dataType":"TEXT","label":"Benefit Period Options","order":null},{"config":{},"dataSelector":{"recordType":"product","fieldCode":"FILTERS.MAXIMUM_MONTHLY_BENEFIT"},"dataType":"MONEY","label":"Maximum Monthly Benefit","order":null},{"config":{},"dataSelector":{"recordType":"product","fieldCode":"FILTERS.MAXIMUM_PERCENT_OF_INCOME_COVERED"},"dataType":"PERCENTAGE","label":"Maximum % of Income Covered","order":null},{"config":{"VALUES":"Yes, No, Optional"},"dataSelector":{"recordType":"product","fieldCode":"FILTERS.REDUNDANCY_COVER"},"dataType":"TEXT","label":"Redundancy Cover","order":null},{"config":{"MULTISELECT":true,"VALUES":"14 Days,28 Days,30 Days,56 Days,60 Days,90 Days,6 Months,1 Year,2 Years"},"dataSelector":{"recordType":"product","fieldCode":"FILTERS.WAITING_PERIOD_OPTIONS"},"dataType":"TEXT","label":"Waiting Period Options","order":null},{"config":{"VALUES":"0"},"dataSelector":{"recordType":"UI_FILTER_COMPONENT","fieldCode":"FULL_MARKET"},"dataType":"FULL_MARKET","label":"More products","queryParameter":"full-market"}],"niche":{"currencySymbol":"$","decimalPoint":".","decimalPlaces":"2","thousandsSeparator":",","filterBoundsMap":{"product.GENERAL.PROVIDER_ID":null,"product.FILTERS.BENEFIT_PERIOD_OPTIONS":null,"product.FILTERS.MAXIMUM_MONTHLY_BENEFIT":{"minimum":"10000","maximum":"60000"},"product.FILTERS.MAXIMUM_PERCENT_OF_INCOME_COVERED":{"minimum":"70","maximum":"85"},"product.FILTERS.REDUNDANCY_COVER":null,"product.FILTERS.WAITING_PERIOD_OPTIONS":null}},"prefilled":false,"experimental":false}
6 of 22 results
Compare other products
Looking for other options? Check out these similar products.
How we picked these
Finder Score - Income Protection
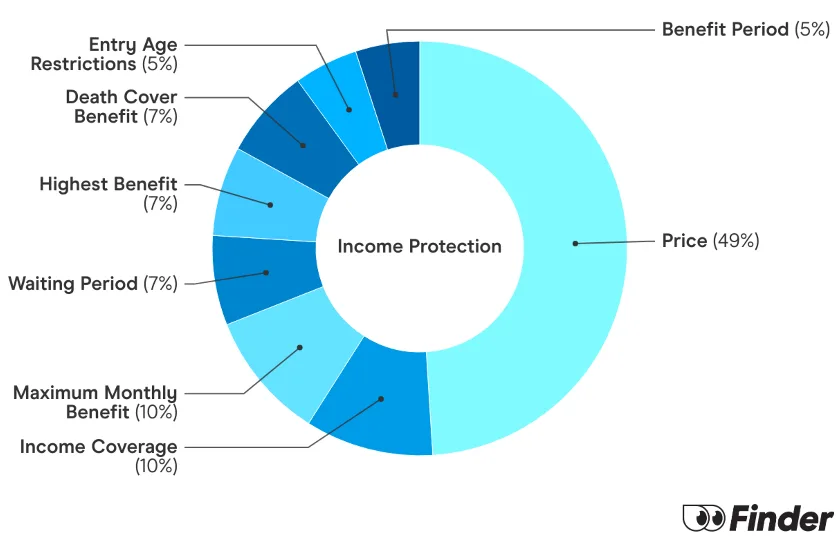
Income Protection is a little complicated and a lot overwhelming. That's why we made the Finder Score, to make it easier to compare Life Insurance products against each other. Our experts analysed over 21 products and gave each one a score rank out of 10, to make it easier to compare Income Protection products against each other.
But a higher score doesn't always mean a product is better for you. Your situation is unique, so your policy choice will be too. Don't think of Finder Score as the final word, but as a good place to start your life insurance comparison.
Dentists face specific risks including infections, radiation and musculoskeletal problems requiring tailored cover.
Many policies offer specialised cover for needle-stick injuries, blood-borne diseases and mental health conditions.
Protect your income, as medical professionals are 20% more likely to stop work from mental illness.
Being a dentist means that you are constantly exposed to health risks due to the nature of your work such as being infected with a contagious disease carried through one of your patient's blood, saliva, or other bodily fluid.
Dentists are also likely to earn an above-average income, which can be worth protecting if you're the breadwinner of the household.
What risks are dental practitioners exposed to?
Dentistry is a medical profession that is considered by the healthcare practitioners as being potentially hazardous due to a number of significant health risks. Dentists are not only at risk for a blood borne viral infection, but they are also exposed to certain conditions on a daily basis, which include:
Risk
Details
Infections
Dentists are at high risk of infection of a life-threatening blood borne disease, such as HIV or viral Hepatitis, which are often transmitted through sharp instruments (such as needles), spatter and aerosol.
However, bacterial infections are also considered to be a major concern, particularly in dealing with the likes of tuberculosis and syphilis.
Percutaneous exposure incidents
Percutaneous involves any medical surgeries that require the practitioner to access the inner organs or other tissues using a sharp instrument (such as needle) to puncture the skin, rather than an “open” method where the organs or tissues are exposed with the use of a scalpel.
Dentists regularly have to perform exposure prone procedures on daily basis and work predominantly on the mouth, increasing the risks of being exposed to infectious diseases.
Radiation
There are two types of radiation that affect dental workers on a day-to-day basis - ionizing and non-ionizing radiation. Ionizing radiation occurs through using X-ray machines at the dentist’s practice room.
On the other hand, non-ionizing radiation may occur through lasers practice in dental procedures, use of composites and other resins, which becoming a concern due to the potential hazard to the eyes and other tissues.
Dental materials (chemicals)
Dentists often require the use of anaesthetics on patients and exposures of nitrous oxide gases on a regular basis for an extended period of time can be hazardous to health.
In addition, exposure to toxic chemicals, such mercury (through amalgam fillings), pose a significant threat to dental workers as inhalation of mercury vapour in high doses can lead to biological and neurological problems.
Noise
Certain sounds of dental equipments may lead to noise-induced hearing loss and the first complication that often encourages dentists to seek a hearing evaluation is the presence of tinnitus - a condition in which the ear is persistently “ringing,” and not caused by the outside sounds.
These sound inducing hearing loss may be caused by high-speed and low-speed turbine handpieces, high-velocity suction, ultrasonic instruments and cleaners, vibrators and other mixing devices, and model trimmers.
Musculoskeletal disorders
Musculoskeletal injuries affect dentists significantly more compared to other healthcare workers. A dentist’s posture is constrained when they are performing a procedure, in which they may be standing up or sitting down, close to the patient who is in a sitting or lying down position.
This repetitive posture is often the main cause of stress injury on a musculoskeletal system.
Psychological problems
Work-related psychological disorders are prevalent in the dental field, with stress, tension, depression, emotional exhaustion and depersonalisation as the common contributing factors.
Dermatitis
Using gloves and other protective equipments are imperative for dental professionals, particularly in the effort of reducing the transmission of blood borne pathogens. However, it has been reported that dentists often have allergic reactions to gloves containing latex, which may result in skin irritation.
Other dental materials, such as detergents, lubricating oils, solvents, and X-ray processing chemicals could also lead to skin allergies.
What are the key benefits of income protection for dentists?
Income protection does not only provide you with a replacement income of up to 70% of your regular wage, and up to 75% with some insurers, in the event of a serious illness or injury, but also covers you against the associated risks of your occupation as a dental practitioner. There are some features and benefits that are designed specifically to meet the needs of dentists. These include;
Cover for HIV, blood-borne diseases, and needle stick injuries:
As a dentist, you may be required to perform oral surgical procedures. These procedures are often prone to exposures, in which a direct contact between the skin (usually the finger or thumb of the dentist) and sharp surgical instruments or body parts within the oral region is potentially established.
In the event that you contract HIV, Hepatitis B or C even, you may requested by your professional governing board (such as the Dental Board of Australia) to cease performing any exposure prone procedures. Depending on the severity of the infection, you may have to stop working completely, even if you still have the ability to work.
With needle-stick cover, you will eligible for a lump sum benefit in the event that are unable to work or suffer from a reduction in income as a result of contracting HIV, Hepatitis B or C.
Cover for Mental Illness:
It has been noted in studies that due to the high level of stress, those who are in the medical profession are 20% more likely to stop working due to mental illness. Dental practitioners in particular may be prone to different sources of professional stress, such as professional burnout, anxiety disorders and depression.
With an income protection policy in place, you will have access to a form of financial relief, especially if you are required to take time off work due to a debilitating mental illness.
What features should dentist look for when it comes to income protection?
In addition to important features such as needlestick and mental illness cover, income protection insurance also provides other important features and options that you can tailor according to your needs. It is essential to read the Product Disclosure Statement (PDS) for more information, as policy features may vary between providers.
Some of the features and benefits that you may to consider include (but not limited to):
Rehabilitation Benefit: With this benefit, your rehabilitation and treatment costs with an approved medical practitioner will be covered.
Death Benefit: In the event of your death, a multiple of your monthly benefit will be payable to your nominated beneficiaries.
Terminal Illness Benefit: A lump sum benefit is payable if you have been diagnosed with a terminal illness with only less than 12 months to live.
Inflation Cover: This coverage allows your policy to increase in value with time. The increase is based on the Consumer Price Index (CPI) or a set percentage.
Worldwide Cover: You may want to be able to access your cover no matter where you are in the world, 24/7.
Yes income protection is highly recommended for self employed dentists and practice owners. As a self employed professional you do not have access to sick leave or workers compensation benefits that employees might. Income protection can provide a vital financial safety net ensuring your business and personal finances are protected if you cannot work due to illness or injury.
Income protection premiums for dentists are influenced by several factors. These include your age sex occupation and income level. Your chosen waiting period benefit period and any additional riders or features will also affect the cost. Given the specific risks associated with dentistry such as exposure to diseases or musculoskeletal issues your occupation loading may also play a role in premium calculation.
Generally yes income protection premiums are tax deductible in Australia. This means you can claim the cost of your premiums as a deduction on your income tax return. However the income protection benefit payments you receive are typically treated as taxable income. It is always best to consult a financial adviser or tax professional for personalised advice.
An agreed value policy calculates your monthly benefit based on your income at the time you apply for the policy. Agreed value cover has not been sold to new customers since 31 March 2020, when APRA required insurers to stop writing it, so it now mainly applies to people who already hold an older policy. This amount is "agreed" upon upfront and does not change even if your income fluctuates. An indemnity value policy calculates your benefit based on your income at the time you make a claim usually over the 12 months prior. Agreed value often provides more certainty at claim time while indemnity value may be cheaper.
If you change your dental career or retire your income protection policy may need to be reviewed or adjusted. If you change to a less risky occupation your premiums might decrease. If you stop working entirely you may no longer be eligible for income protection as it protects your ability to earn an income. Contact your insurer or financial adviser to discuss how any career changes or retirement plans impact your specific policy.
When making an income protection claim you typically need to provide medical evidence from your treating doctor detailing your illness or injury and its impact on your ability to work. You will also need proof of your income prior to your disability such as payslips or tax returns and possibly a completed claim form from your insurer. For self employed dentists financial statements may be required.
Finder writers are subject matter experts and use primary sources, in-depth research and interviews with other experts to ensure you're getting accurate, up-to-date information. Articles are fact checked in line with our editorial guidelines.
James Martin was the insurance editor at Finder. He has written on a range of insurance and finance topics for over 7 years. James often shares his insurance expertise as a media spokesperson and has appeared on Prime 7 News, Insurance News, 7NEWS and The Guardian. An experienced journalist, James' work has featured in publications including The Irish Times, Companies100 and In Business. He holds a Tier 1 General Insurance (General Advice) certification and a Tier 1 Generic Knowledge certification, both of which meet the requirements of ASIC Regulatory Guide 146 (RG146).
See full bio
James's expertise
James
has written
167
Finder guides across topics including:
Cristal Dyer is a travel writer at Finder. She has been writing about travel for over five years and has visited over 40 countries around the world. Cristal currently travels full-time, writing about her favourite cities and food finds, and she is always on the lookout for amazing flight deals to share.
See full bio
Here's what contractors need to know about finding income protection insurance policies that fit their specific employment situations.
Important information about this website
Finder is a comparison service. We do not compare every product or every provider in the market.
We make money through commercial arrangements with some of the providers on this site. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement.
Our editorial content, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements.
The default order of products in our tables can be influenced by commercial arrangements. You can re-sort or filter using the controls above each table.
Some content on this site may be generated or supported by AI tools. You should verify details directly with the provider.
Finder is one of Australia's leading comparison websites. We are committed to our readers and stand by our editorial principles.
Our comparison service does not include every product or every provider in the market. Some product issuers offer their products under multiple brands or through associated companies. Where we can, we identify the underlying issuer so you can compare like with like, but you should always check with the provider directly to confirm which brand you are dealing with.
Finder is a comparison website and an intermediary. We are not a product issuer and we do not provide personal financial or credit advice. When you click a link to a product, or apply for a product through our site, you deal directly with the product issuer. We may receive a referral fee, commission or other payment from the issuer if you click through, apply or take out a product. We describe these arrangements in more detail under 'How we make money' below.
Product features, fees, terms and eligibility criteria are set by the product issuer and may change. We rely on information supplied by issuers when we present product details on our site. Before you apply for or take out any product, you should confirm the details directly with the issuer.
We earn revenue from Finder in four principal ways:
Referral fees and commissions. When you click a product link, complete an enquiry form or apply for a product through our site, we may receive a referral fee, commission or other payment from the product issuer. We may also receive payment based on the volume of leads or conversions we send to an issuer.
Sponsored placements. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement between Finder and the issuer. These labels always indicate a paid placement. We do not use them for editorial choices.
Display advertising. Banner advertising, newsletter advertising and similar display ads on our site are paid by advertisers.
Content sponsorship. Some articles, videos and social media posts are sponsored by an issuer and are clearly labelled as such.
Our editorial opinions, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements. A 'Top Pick' is an editorial choice made by our writers and editors based on the criteria described on each comparison page. A 'Top Pick' is not a personal recommendation and does not mean the product is appropriate for your circumstances.
If you would like to know whether we have a commercial arrangement with a specific product issuer, please contact us.
When products are grouped in a table or list, the default order can be influenced by commercial arrangements we have with product issuers. In some categories, sponsored or featured products appear in the top positions of the table by default, and are always labelled as such.
Other factors that influence default order include price, fees and features, and (where relevant) our editorial view of the product.
You can re-sort every comparison table using the controls above the table. You can filter by product features that matter to you. The order you see after re-sorting or filtering is not influenced by commercial arrangements.
Some content on this site is generated or supported by artificial intelligence tools, including our AI-powered assistant FinderBot. AI-generated content may contain errors. Please verify important information directly with the product issuer before making a financial decision. For more information about FinderBot, see the FinderBot Terms of Use and FinderBot Privacy Collection Notice.
Please read our website terms of use and privacy policy for more information about our services and our approach to privacy.
We update our data regularly, but information can change between updates. Confirm details with the provider you're interested in before making a decision.
Our goal is to create the best possible product, and your thoughts, ideas and suggestions play a major role in helping us identify opportunities to improve.