Key takeaways
- Income protection replaces up to 70% of your income, and up to 75% with some insurers, if injury or illness stops you working, covering you anywhere.
- A 35-year-old male carpenter sample monthly premium is often $323-$916.
- Premiums are typically tax deductible and policies cover contractors or self-employed individuals.
How does income protection work for tradies?
If you're a tradie, you're well aware of the dangers of your work. Income protection insurance for tradies is designed to replace up to 70% of your income, and up to 75% with some insurers, if you're unable to work because you get injured or become ill. Unlike workers' compensation, it covers you if you get injured inside or outside of work, whether you are a full-time employee, contractor or classed as self-employed.
Once you've had your claim accepted, income protection pays you a monthly benefit either until you're fit and able to return to work, your benefit period ends (you can choose when this is), or you turn a certain age (usually around 65 to 70 years old), depending on the policy you opt for.
Summary of professions covered by income protection
The list below outlines some of the main trade professions that income protection can cover.
- Carpenter
- Electrician
- Heavy equipment operator
- Labourer
- Landscaper
- Painter
- Plumber
- Mechanic
- Machinist
- Locksmith
- Ironworker
How much can tradies expect to pay for income protection?
This depends on your profession, as well as factors such as your age, gender and smoking status. Generally, you can expect to pay more than white collar jobs, because there's more risk involved.
To give you an idea of how much a tradie can expect to pay, we've put together a table on the different costs for both male and female carpenters.
Looking for other options? Check out these similar products.
How we picked theseLooking for other options? Check out these similar products.
How we picked theseKeep in mind that this will differ depending on the riskiness of your job. High risk manual workers are likely to pay more.
Why might tradies need income protection?
Income protection is important for anyone that relies on their income to pay the bills, which is just about all of us. It's arguably doubly important for tradies. Here's why:
- Your job requires you to be physically healthy. If an office worker breaks their leg playing footy on a Saturday, they probably won't need to take much, if any, time off work. Tradies can't get off that easily. Any injury is likely to prevent you from working, and if you go back too early, you risk making your injury worse. Income protection lets you take the time off that you need.
- It protects you everywhere. Unlike workers' compensation, income protection covers you inside and outside of work. You may do most of your heavy lifting at work, but accidents can happen anywhere. Income protection can look after you wherever you are, even overseas, for injuries and illnesses.
- It's sometimes compulsory. Many building sites require you to have income protection insurance as well as workers compensation.
- Workers' compensation may not be enough. Workers' compensation often only pays you for a limited number of years and in lots of cases won't be enough to cover all your bills. Income protection, on the other hand, can pay you up to 70% (and in some cases more) of your current salary, so you know exactly how much you're getting.
- You work in a risky profession. It may feel safe because you're familiar with it, but trade jobs are among the most dangerous in Australia. It's smart to protect your income and the people who rely on it.
Compare income protection insurance
Looking for other options? Check out these similar products.
How we picked theseFinder Score - Income Protection
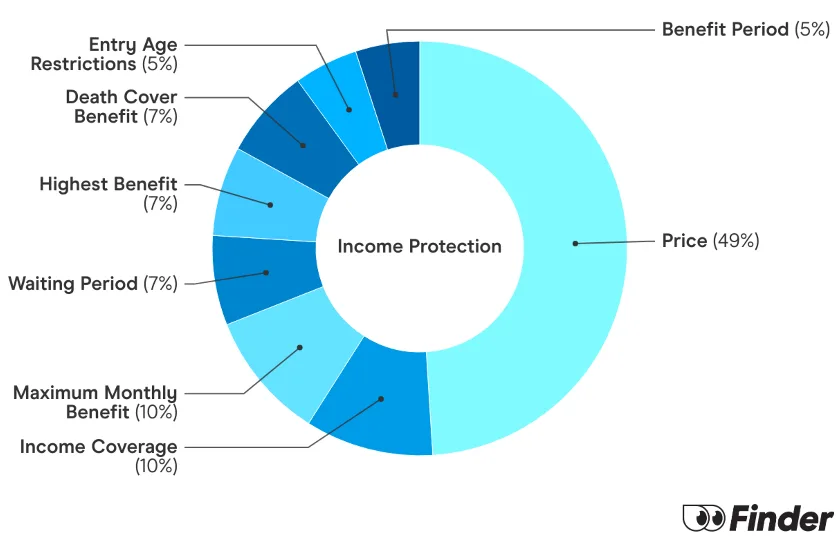
Income Protection is a little complicated and a lot overwhelming. That's why we made the Finder Score, to make it easier to compare Life Insurance products against each other. Our experts analysed over 21 products and gave each one a score rank out of 10, to make it easier to compare Income Protection products against each other.
But a higher score doesn't always mean a product is better for you. Your situation is unique, so your policy choice will be too. Don't think of Finder Score as the final word, but as a good place to start your life insurance comparison.
What other options are there for tradies?
Income protection is definitely one of the most important insurance types worth having, but there are a few others worth knowing about.
- Personal accident. Personal accident is like income protection except it doesn't cover you for illnesses, just accidents. It's a cheaper alternative to income protection because it doesn't cover you for as much.
- Public liability insurance. This protects you if you cause personal injury to someone or damage their property. For example, if you were fixing a plumbing issue and in the process accidentally injured someone, this could cover you for legal costs and more.
- Product liability insurance. A little like public liability, but this one protects you if a product or job you worked on causes injury to someone or damages their property. For example, if there's an issue with the materials you used on a job that causes damage, this can cover you.
- Other types of life insurance. Death cover can pay your family a large lump sum if you die, while TPD can cover you if you become permanently disabled and have to quit work for good.
Bottom line
You can risk putting it off, but if you're a tradie, there's a lot more chance of you needing income protection. For a few bucks a week, income protection can provide peace of mind and financial security.
Frequently asked questions
-
Income protection generally covers any injury or illness that prevents you from performing your usual work duties. For tradies, this can include common issues like musculoskeletal injuries, fractures, severe strains, repetitive strain injuries, back problems and specific illnesses that impact your physical capacity to work. It also covers mental health conditions that prevent you from working.
-
The waiting period is the amount of time you must be off work due to injury or illness before your income protection payments begin. Common waiting periods include 14 days 30 days 60 days or 90 days. The benefit period is the maximum length of time you can receive payments once your claim is approved. This can range from a few months to several years or even up to age 65 or 70. Choosing a longer waiting period or shorter benefit period can generally lead to lower premiums.
-
Yes you can often hold income protection insurance through your superannuation fund. This can sometimes be a more cost effective option as premiums are paid from your super balance. However super-held policies may have more limited cover or stricter conditions compared to policies held outside of super such as shorter benefit periods or an inability to choose agreed value cover. It is important to compare options carefully.
-
Income protection replaces a portion of your income if you are temporarily unable to work due to injury or illness. Payments are usually made monthly for a specific benefit period. Total Permanent Disability TPD insurance on the other hand pays a lump sum benefit if you become permanently disabled and are unlikely to ever work again in your usual occupation or any occupation for which you are suited by education training or experience. They cover different scenarios and often complement each other.
-
If you change jobs or move into a different trade profession you should inform your insurer. Your occupation is a key factor in determining your premium and level of risk. Changing to a higher risk role may increase your premiums while moving to a lower risk role could reduce them. It is important to update your policy details to ensure your cover remains appropriate and valid.
-
Yes like most insurance policies income protection for tradies often has exclusions. Common exclusions can include injuries or illnesses caused by intentional self harm criminal acts war or acts of terrorism. Pre-existing medical conditions may also be excluded or subject to specific terms if not declared and accepted by the insurer at the time of application. Always read your Product Disclosure Statement PDS for full details.
-
Finder writers are subject matter experts and use primary sources, in-depth research and interviews with other experts to ensure you're getting accurate, up-to-date information. Articles are fact checked in line with our editorial guidelines.
- TAL income protection insurance PDS (accessed April 2024)
- AAMI income protection insurance PDS (accessed April 2024)
- Nobleoak Disability Income Insurance PDS (accessed April 2024)
- Medibank income protection insurance PDS (accessed April 2024)
- ahm Income Protection insurance PDS (accessed April 2024)
- Insuranceline Income Protection insurance PDS (accessed April 2024)
Gary Ross Hunter has over 6 years of expertise writing about insurance, including life, health, home, and car insurance. Having reviewed hundreds of product disclosure statements and published over 800 articles, he loves simplifying complex insurance topics for everyday readers. Gary has contributed to major outlets like Yahoo Finance, The Sydney Morning Herald, and news.com.au, and holds a Bachelor of Arts (Honours) in English Literature from the University of Glasgow, along with a Tier 2 General Advice certification, ensuring his work adheres to ASIC’s RG146 standards. See full bio
- Health, home, life, car, pet and travel insurance
- Managing the cost of living
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
More guides on Finder
-
Income Protection for Doctors & Medical Professionals
Find out how income protection for doctors can help you if you are a medical professional and become ill or injured.
-
Income Protection for Contractors
Here's what contractors need to know about finding income protection insurance policies that fit their specific employment situations.
-
Income protection for dentists
Income Protection has specific features designed for dentists including needlestick cover.