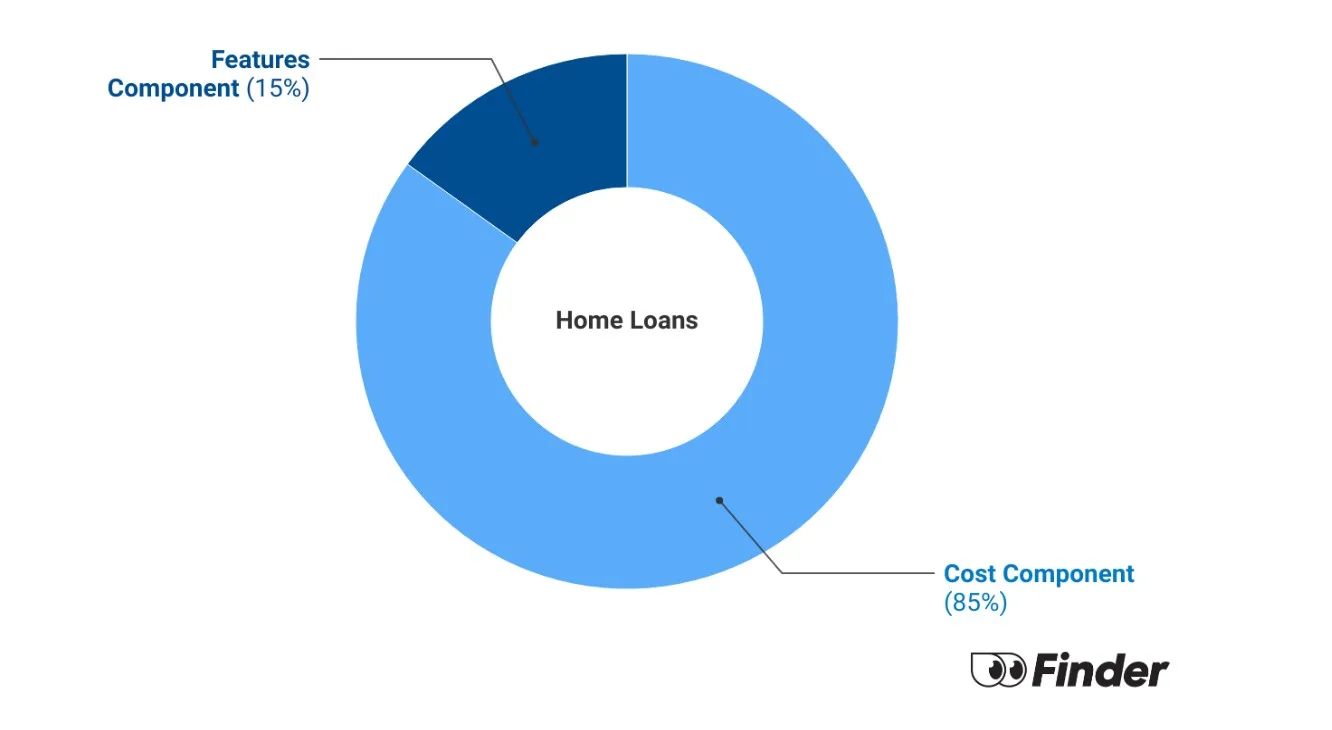
These home loans offer low costs, coupled with a host of features, giving the best overall value.
7+
Great
These loans may have slightly higher interest rates or fewer features but overall, a competitive offering.
5+
Standard
Usually these home loans would offer above average rates. They may still include some competitive features.
0+
Basic
Higher costs and/or fewer features.
Key takeaways
The lowest interest rate on the market in September is a variable rate of 5.69%.
You could save $6,912 a year by switching from the average variable rate to 6.9%.
The cheapest rate might not be the best loan: look out for fees and features, and remember you might end up with a higher rate if you want to borrow above 80% of the property value.
How to compare the cheapest home loan rates
You’d think it was as simple as looking at the lowest number in the table, right? Well, it can be. But there are some things to watch out for that could make your cheap home loan…not so cheap.
1. Ok yes, look at the rate
The starting point is to always look at the rate. The lower rate, the lower your repayments.
2. But then look at the fees
Some loans lure you in with a cheap attractive rate, but then you find it piles on a huge fee to apply and another fee to pay each month as well. Your cheap rate now costs you more per month than the slightly higher interest rate with no fees.
3. Then have a little glance at the comparison rate
Comparison rates are normally based on loans of $150,000 so they’re not always helpful. But if the comparison rate is much higher than the actual interest rate, you can bet there are other costs driving your repayments up.
4. Don't forget to look at the features
It’s all well and good getting a low interest rate but if you’re sacrificing access to features that could save you money in the long run, it’s not worth it. Take an offset account, for example. Using an offset account will mean you pay down the loan faster because it reduces the amount of interest you need to pay.
Is your rate the cheapest rate?
On this page we've called out 5.69% as the cheapest rate, and that's because it's the cheapest rate for the widest pool of borrowers. But there may be cheaper rates for different borrowers, like if you're a first home buyer, if you have a higher deposit or if you're fixing your home loan. This is why it's always important to compare home loan interest rates: the cheapest rate available to someone else may not be the cheapest rate available to you.
The lower the interest rate the lower the repayments
The number one factor in determining a cheaper home loan is a low interest rate.
Let's compare 2 otherwise identical home loans with slightly different interest rates.*
Interest rate
6.9%
5.69%
Loan amount
$730,719
$730,719
Loan term
30 years
30 years
Monthly repayment
$4,813
$4,237
Monthly saving
N/A
$576
Annual saving
N/A
$6,912
As you can see, with the lower interest rate, you save $576 a month – or $6,912*We're using the average owner-occupier home loan size from the ABS, the average variable rate loan in Finder's database of the full market and the lowest variable rate available for refinancers.
How much can you save with a cheaper home loan?
We calculated this by using our loan repayment calculator. Try it out for yourself and see how much you could save.
What are the lowest home loan rates on the market?
Every month, we analyse the rates in our database to create a list of the market's cheapest loans.
The lowest variable interest rate in Finder’s database right now is 5.69%
The lowest fixed interest rate in Finder’s database right now is 5.79%
The cheapest rates over time.
Finder's lowest home loan rates
A graph showing 4 lines, for fixed and variable interest rates for investor and owner-occupier loans.
Finder's lowest home loan rates
Month
Variable (owner occupier)
Fixed (owner occupier)
Variable (investment)
Fixed (investment)
May-2018
3.49%
3.69%
3.79%
3.89%
Jun-2018
3.52%
3.69%
3.79%
3.89%
Jul-2018
3.49%
3.69%
3.79%
3.89%
Aug-2018
3.54%
3.74%
3.93%
3.84%
Sep-2018
3.49%
3.74%
3.89%
3.84%
Oct-2018
3.54%
3.74%
3.79%
3.84%
Nov-2018
3.54%
3.74%
3.79%
3.84%
Dec-2018
3.49%
3.69%
3.74%
3.84%
Jan-2019
3.49%
3.74%
3.74%
3.89%
Feb-2019
3.49%
3.74%
3.74%
3.84%
Mar-2019
3.49%
3.74%
3.74%
3.84%
Apr-2019
3.48%
3.74%
3.91%
3.84%
May-2019
3.48%
3.59%
3.74%
3.69%
Jun-2019
3.24%
3.39%
3.69%
3.69%
Jul-2019
2.89%
3.19%
3.49%
3.39%
Aug-2019
2.89%
2.98%
3.29%
3.09%
Sep-2019
2.89%
2.74%
3.19%
3.00%
Oct-2019
2.69%
2.74%
2.99%
3.00%
Nov-2019
2.69%
2.68%
2.99%
2.84%
Dec-2019
2.69%
2.68%
2.99%
2.84%
Jan-2020
2.69%
2.68%
2.99%
2.84%
Feb-2020
2.69%
2.68%
2.99%
2.84%
Mar-2020
2.49%
2.68%
2.79%
2.84%
Apr-2020
2.44%
2.09%
2.79%
2.39%
May-2020
2.39%
2.09%
2.79%
2.29%
Jun-2020
2.39%
2.09%
2.79%
2.34%
Jul-2020
2.19%
1.99%
2.79%
2.34%
Aug-2020
1.99%
1.99%
2.74%
2.29%
Sep-2020
1.99%
1.98%
2.59%
2.29%
Oct-2020
1.99%
1.90%
2.59%
2.29%
Nov-2020
1.99%
1.98%
2.64%
2.29%
Dec-2020
1.99%
1.89%
2.33%
1.99%
Jan-2021
1.99%
1.88%
2.33%
1.99%
Feb-2021
1.99%
1.88%
2.33%
1.99%
Mar-2021
1.99%
1.69%
2.33%
1.99%
Apr-2021
1.95%
1.69%
2.24%
1.99%
May-2021
1.95%
1.69%
2.24%
1.99%
Jun-2021
1.90%
1.67%
2.24%
1.99%
Jul-2021
1.89%
1.67%
2.24%
1.89%
Aug-2021
1.89%
1.69%
2.32%
1.99%
Sep-2021
1.85%
1.69%
2.32%
1.99%
Oct-2021
1.85%
1.59%
2.24%
1.89%
Nov-2021
1.85%
1.59%
2.24%
1.89%
Dec-2021
1.77%
1.59%
2.24%
1.89%
Jan-2022
1.85%
1.79%
2.17%
2.14%
Feb-2022
1.77%
1.79%
2.14%
1.99%
Mar-2022
1.77%
1.84%
1.99%
1.99%
Apr-2022
1.79%
1.84%
1.99%
1.99%
May-2022
1.79%
1.84%
2.14%
2.39%
Jun-2022
2.04%
2.09%
2.39%
2.69%
Jul-2022
2.44%
2.59%
2.79%
3.59%
Aug-2022
3.05%
3.59%
3.24%
3.99%
Sep-2022
3.14%
3.99%
3.59%
4.29%
Oct-2022
3.54%
4.19%
3.84%
4.19%
Nov-2022
3.44%
4.49%
4.19%
4.59%
Dec-2022
4.29%
4.60%
4.57%
4.84%
Jan-2023
4.29%
4.64%
4.59%
4.79%
Feb-2023
4.39%
4.94%
4.64%
5.09%
Mar-2023
4.64%
4.99%
4.97%
5.19%
Apr-2023
4.64%
4.99%
5.14%
4.99%
May-2023
4.64%
4.99%
5.14%
4.99%
Jun-2023
5.34%
5.24%
5.29%
5.44%
Jul-2023
5.39%
5.23%
5.89%
5.56%
Aug-2023
5.39%
5.23%
5.79%
5.53%
Sep-2023
5.39%
5.48%
5.79%
5.54%
Oct-2023
5.39%
5.48%
5.74%
5.56%
Nov-2023
5.59%
5.48%
5.74%
5.56%
Dec-2023
5.74%
5.48%
5.69%
5.58%
Jan-2024
5.69%
5.48%
5.69%
5.58%
Feb-2024
5.69%
5.48%
5.69%
5.58%
Mar-2024
5.69%
5.48%
5.69%
5.58%
Apr-2024
5.69%
5.48%
5.94%
5.58%
May-2024
5.69%
5.48%
5.94%
5.58%
Jun-2024
5.69%
5.48%
5.94%
5.58%
Jul-2024
5.69%
5.48%
5.94%
5.58%
Aug-2024
5.69%
5.59%
5.94%
5.69%
Sep-2024
5.69%
5.59%
5.94%
5.69%
Oct-2024
5.69%
4.99%
5.94%
4.99%
Nov-2024
5.69%
4.99%
5.94%
4.99%
Dec-2024
5.69%
4.99%
5.94%
4.99%
Jan-2025
5.69%
4.99%
5.94%
4.99%
Feb-2025
5.38%
4.99%
5.54%
4.99%
Mar-2025
5.44%
4.99%
5.84%
5.29%
Apr-2025
5.64%
4.99%
5.79%
5.29%
May-2025
5.59%
4.99%
5.79%
4.99%
Jun-2025
5.34%
4.99%
5.59%
4.99%
Jul-2025
5.34%
4.99%
5.59%
4.99%
Aug-2025
5.34%
4.94%
5.59%
4.99%
Sep-2025
5.09%
4.64%
5.34%
4.89%
Oct-2025
4.99%
4.64%
5.34%
4.69%
Nov-2025
4.99%
4.64%
4.99%
4.69%
Dec-2025
4.99%
4.64%
5.34%
4.74%
Jan-2026
4.99%
4.79%
5.29%
4.99%
Feb-2026
4.99%
4.94%
5.29%
4.99%
Mar-2026
5.10%
5.20%
5.35%
5.20%
Apr-2026
5.19%
5.49%
5.35%
5.59%
May-2026
5.35%
5.70%
5.60%
5.70%
Jun-2026
5.69%
5.99%
5.85%
5.99%
Jul-2026
5.14%
5.99%
5.85%
5.99%
Aug-2026
5.69%
5.99%
5.85%
5.99%
Sep-2026
5.69%
5.79%
5.94%
5.89%
Every month, we find the lowest home loan rates in our database for 4 different loan types. To ensure these products are not overly restrictive in eligibility criteria, every loan we select must meet the following criteria:
Loans must be principal and interest loans with a maximum LVR of 80%, meaning you need a minimum 20% deposit.
Fixed rates have terms of between 1 and 5 years.
Mortgages are taken from Finder's database, with rates correct at the time of publication (updated every month).
What are the cheapest home loans at the big 4 in September 2026?
Interest rates can change depending on your circumstances, but as a guide, here are the cheapest home loans from the big 4.
"I wanted to make sure I have one of the cheapest home loans on the market. So I found an online lender with a consistently low interest rate (I should know, I check rates every month). But I also made the sure the loan had an offset account. For me, being able to build up savings in the offset account speeds up my loan and cuts down my overall interest charges dramatically. This makes the loan much cheaper in the long run."
At a very basic level, the cheapest home loan is the one with the lowest rate. But every borrower has different needs. So beyond a low rate, you need to get a loan that actually helps you achieve your property goals and financial needs.
Fixed rate loans are less likely to allow extra repayments and will probably charge a break fee if you do repay early.
A loan that matches your strategy
The cheapest home loans are likely owner-occupier loans, but if you're buying an investment property they won't help you. You might also want an interest-only loan for the tax benefits if you're an investor.
A loan with an offset account
The money you'll save by using an offset account may very well mean you end up paying less than if you went for a lower rate without an offset account. Check out our guide on offset accounts to see if it could help you.
Expert insight
"If I had to credit just one thing with helping me repay my home loan in just 7 years, I'd say it was an offset account. This is a debt-busting secret weapon. You should keep every cent to your name in one of these – we're talking your savings for everything, your emergency cash stash and even your salary. You'll likely save tens of thousands of dollars and shave years off your time in debt."
Nicole Pedersen-McKinnon
Finance journalist
3 extra tips to help you save money on your home loan
1. Choose your loan term carefully
Most borrowers choose 30-year loan terms.
If you picked a shorter loan term your monthly repayments would be higher, but you'd pay off your loan 5 years earlier, saving thousands in interest.
Let's look at 3 examples where the loan term changes:
Loan term
30 years
25 years
20 years
Interest rate
5.50%
5.50%
5.50%
Loan amount
$600,000
$600,000
$600,000
Monthly repayment
$3,407
$3,685
$4,128
Total cost*
$1,226,425
$1,105,358
$990,558
*Total cost here refers to the amount of interest you pay over the life of the loan, plus the principal.
2. Find a loan with lower fees
Some lenders charge multiple loan fees that can add up to hundreds of dollars. But other lenders charge basically no fees at all (you still have to pay government fees like a mortgage registration fee).
If 2 loans have identical interest rates and features, the one with fewer fees will be the cheapest home loan.
A cheap home loan is about more than the rate
With the average mortgage holder handing over 38% of their take-home pay in repayments, and 55% above the 30% mark, chasing a genuinely cheap home loan isn't just about bragging rights. Low fees and features that actually suit how you use the loan can matter just as much as the headline rate when it comes to freeing up breathing room each month.
You can unlock lower rates. Many lenders offer lower interest rates for borrowers with a deposit of 20% or more.
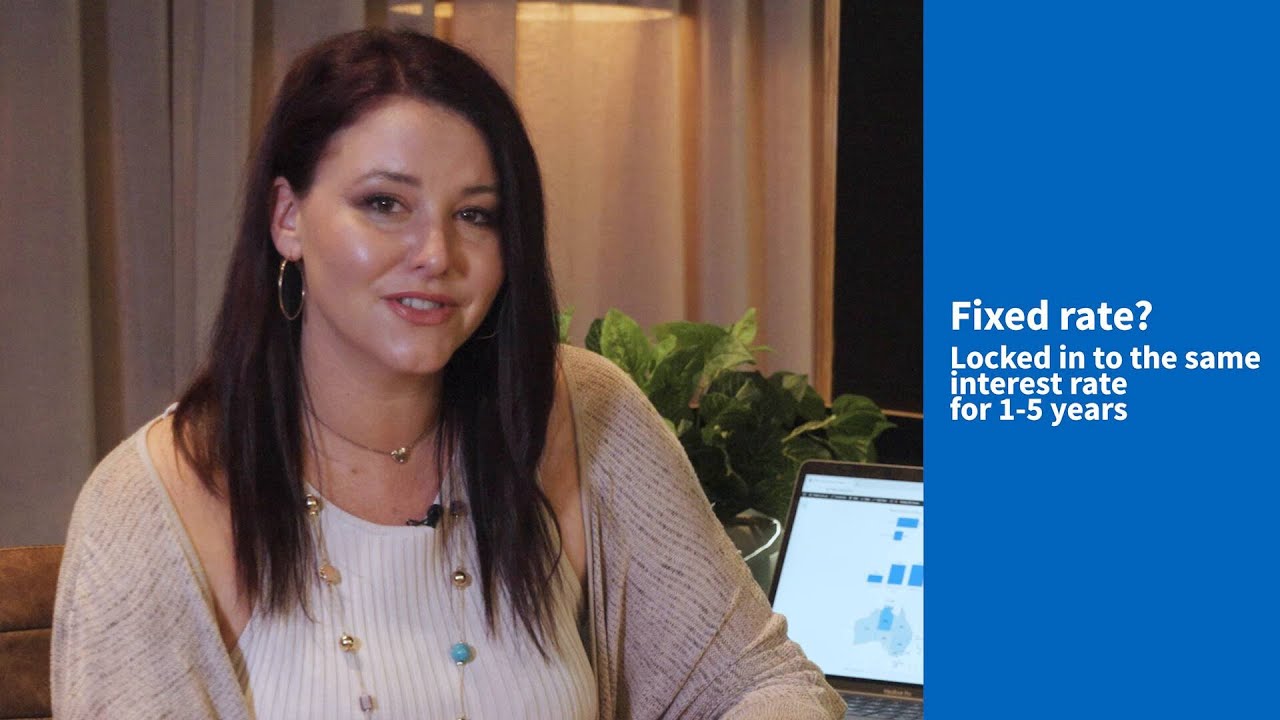
Watch: How to find a lower home loan rate
2:03
Why you can trust Finder's home loan experts
Let us do the talking - we spoke to heaps of experts, brokers, banks and real humans to put 20+ hours into this guide. Our editors regularly talk to buyers, refinancers, investors and every one in-between to keep this information useful.
Rates obsessed - We track big banks, small banks, credit unions and digital banks because even 1 decimal place could save you big bucks (without getting annoying calls!).
Ready when you need it - Lending rates verified from 180+ products day and night. Whether you've remembered you need to refinance at 3am or live at an auction - our rates are up-to-date.
Frequently asked questions about getting a cheap home loan
Some of the market's cheapest home loans come in the form of special discount rate offers. These loans offer a cheap rate to entice you in but revert to a higher rate after a year or two.
Let's be clear, there's nothing bad about these deals. A low rate is a low rate. You just need to pay attention to the interest rate once the discount period ends and refinance to a better loan if your new rate jumps up. But every borrower needs to watch their rate, as lenders do move rates up and down (or keep you on your current rate while offering cheaper home loans to new customers!).
Also look at discharge or exit fees. You don't want to get hit with a big fee when trying to exit the loan later (although a small fee isn't so bad if the rate is very competitive).
Over the last couple of years, variable rates have typically been a little higher than fixed rates. But things are changing. Right now, variable rate loans are becoming lower than fixed rate loans. This is because the RBA held the cash rate at 4.35% in August 2026, but further rate rises are still possible. With hikes still on the table, it's more tempting to lock in a fixed interest rate to avoid future rate rises, so lenders are pricing fixed rates higher than variable rates accordingly.
Online lenders, fintechs and small digital banks tend to have cheaper home loan rates than bigger banks. If you're not comparing rates from these lenders, you might miss some of the best deals on the market.
Mortgage brokers are great at helping you find a home loan and handling mortgage paperwork. But they often don't have small online lenders in their panel of lenders, so you might miss out on a very low rate.
It's a myth that the Big Four always have much higher rates, but they are often higher than the best deals out there. But it's a very competitive market. There's often not much difference between a hot online deal and a big bank's lowest variable rate.
Many of the cheapest loans among Finder's partners (and the wider market) are from smaller banks and local credit unions. But banks are changing their rates and policies constantly, and the Big 4 can be low as well. This is why you really have to compare as many lenders as you can.
Some lenders offer special loans tailored to first home buyers that are worth checking out. You can use our comprehensive guide to learn more about getting a loan as a first home buyer.
Mortgage brokers compare loans for you and are experts at helping borrowers find appropriate products. If you're confused or need help, a broker can be very useful.
But you should also know that many of the market's lowest rates (including many listed on this page) are offered by small lenders that don't appear in a mortgage broker's panel. If the lender isn't in the broker's panel, they cannot help you.
But brokers are helpful for other reasons, and if you have more concerns than just finding the absolute lowest rate, then speaking to a mortgage broker is a good idea. Just do your own research as well.
Saving up for your home loan deposit is a serious challenge for everyone. However, there are ways to trim your expenses, build your deposit and find home loans that don't need large deposits. To master the art of saving for a home loan deposit, you should look at our in-depth, 6-part guide to home loan deposits.
You should always be comfortable with the lender you're planning on going with. If you're not aware of a lender, try calling it to find out about the company and its service level before lodging an application. Speak to previous customers or read customer reviews online.
Keep in mind that little-known lenders might be funded by a larger bank, as is the case with NAB-backed UBank or Firstmac-backed loans.com.au.
What is Finder Score?
The Finder Score crunches 7,000 home loans across 120+ lenders. It takes into account the product's interest rate, fees and features, as well as the type of loan eg investor, variable, fixed rate - this gives you a simple score out of 10.
To provide a Score, we compare like-for-like loans. So if you're comparing the best home loans for cashback, you can see how each home loan stacks up against other home loans with the same borrower type, rate type and repayment type. We also take into consideration the amount of cashback offered when calculating the Score so you can tell if it's really worth it.
Richard Whitten is Finder’s Senior Money Editor, with over eight years of experience in home loans, property, credit cards and personal finance. His insights appear in top media outlets like Yahoo Finance, Money Magazine, and the Herald Sun, and he frequently offers expert commentary on television and radio, helping Australians navigate mortgages and property ownership. Richard started his career in education and textbook publishing in South Korea. He holds multiple industry certifications, including a Certificate IV in Mortgage Broking (RG 206) and Tier 1 and Tier 2 certifications (RG 146), as well as a Bachelor of Education from the University of Sydney and a Graduate Certificate in Communications from Deakin University.
See full bio
Richard's expertise
Richard
has written
749
Finder guides across topics including:
If you’re having trouble securing a home loan through traditional means, there are some government programs that might help you achieve your property goals.
Non-bank mortgage lenders might approve your home loan when the banks say no.
Important information about this website
Finder is a comparison service. We do not compare every product or every provider in the market.
We make money through commercial arrangements with some of the providers on this site. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement.
Our editorial content, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements.
The default order of products in our tables can be influenced by commercial arrangements. You can re-sort or filter using the controls above each table.
Some content on this site may be generated or supported by AI tools. You should verify details directly with the provider.
Finder is one of Australia's leading comparison websites. We are committed to our readers and stand by our editorial principles.
Our comparison service does not include every product or every provider in the market. Some product issuers offer their products under multiple brands or through associated companies. Where we can, we identify the underlying issuer so you can compare like with like, but you should always check with the provider directly to confirm which brand you are dealing with.
Finder is a comparison website and an intermediary. We are not a product issuer and we do not provide personal financial or credit advice. When you click a link to a product, or apply for a product through our site, you deal directly with the product issuer. We may receive a referral fee, commission or other payment from the issuer if you click through, apply or take out a product. We describe these arrangements in more detail under 'How we make money' below.
Product features, fees, terms and eligibility criteria are set by the product issuer and may change. We rely on information supplied by issuers when we present product details on our site. Before you apply for or take out any product, you should confirm the details directly with the issuer.
We earn revenue from Finder in four principal ways:
Referral fees and commissions. When you click a product link, complete an enquiry form or apply for a product through our site, we may receive a referral fee, commission or other payment from the product issuer. We may also receive payment based on the volume of leads or conversions we send to an issuer.
Sponsored placements. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement between Finder and the issuer. These labels always indicate a paid placement. We do not use them for editorial choices.
Display advertising. Banner advertising, newsletter advertising and similar display ads on our site are paid by advertisers.
Content sponsorship. Some articles, videos and social media posts are sponsored by an issuer and are clearly labelled as such.
Our editorial opinions, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements. A 'Top Pick' is an editorial choice made by our writers and editors based on the criteria described on each comparison page. A 'Top Pick' is not a personal recommendation and does not mean the product is appropriate for your circumstances.
If you would like to know whether we have a commercial arrangement with a specific product issuer, please contact us.
When products are grouped in a table or list, the default order can be influenced by commercial arrangements we have with product issuers. In some categories, sponsored or featured products appear in the top positions of the table by default, and are always labelled as such.
Other factors that influence default order include price, fees and features, and (where relevant) our editorial view of the product.
You can re-sort every comparison table using the controls above the table. You can filter by product features that matter to you. The order you see after re-sorting or filtering is not influenced by commercial arrangements.
Some content on this site is generated or supported by artificial intelligence tools, including our AI-powered assistant FinderBot. AI-generated content may contain errors. Please verify important information directly with the product issuer before making a financial decision. For more information about FinderBot, see the FinderBot Terms of Use and FinderBot Privacy Collection Notice.
Please read our website terms of use and privacy policy for more information about our services and our approach to privacy.
We update our data regularly, but information can change between updates. Confirm details with the provider you're interested in before making a decision.
 Let us do the talking - we spoke to heaps of experts, brokers, banks and real humans to put 20+ hours into this guide. Our editors regularly talk to buyers, refinancers, investors and every one in-between to keep this information useful.
 Rates obsessed - We track big banks, small banks, credit unions and digital banks because even 1 decimal place could save you big bucks (without getting annoying calls!).
 Ready when you need it - Lending rates verified from 180+ products day and night. Whether you've remembered you need to refinance at 3am or live at an auction - our rates are up-to-date.