- A new loan with a lower rate to pay off other debts.
- Can be used for personal loan debt, credit card debt or a mix of debt.
- Pay around 12% p.a. up to 7 years. Some fees may apply.
- Accepted debt amounts of $2,000.
Key takeaways
- Consolidating can simplify repayments and lower interest and fees, but a longer term may mean more total interest and higher monthly payments for some.
- There are 3 key ways you can consolidate your debts.
- You may still be able to consolidate your debt if you have bad credit – but it might cost more.
What is debt consolidation?
Debt consolidation is where you move multiple debts into one single debt.
It involves opening another credit account to pay off your existing debt. It means that instead of multiple repayments, you just have the one new account to repay. One account means one repayment date to remember, and ideally fewer fees and interest. If done right, it can also help you pay off the loan faster.
3 ways to consolidate your debt
- Transfer debt to a new card with 0% interest rate.
- Better for credit card debt, but if personal loan amount low enough it might be ok.
- Pay 0% for around 2 years. Some fees may apply.
- For debts of $500 to $8,000.
- Use the equity in your home as a line of credit to pay off debt.
- Uses your home equity to pay off credit cards, personal loans and other debts. It's secured against your home, so missed repayments put the property at risk.
- Pay about 5% for as long as you need. Fees may apply.
- For debts of $40,000.
When should I consider debt consolidation?
- You have multiple debts with different fees. These could include debts from credit cards, personal loans, car loans or student loans.
- You're struggling to make repayments for the different debts you owe.
- You're looking for a cheaper way to pay off your debts.
- You find that keeping track of all your debts is confusing and/or overwhelming.
Comparing your debt consolidation options
-
1
Debt consolidation loans
For personal loan debtThis is one of the most common ways people choose to consolidate or refinance their existing personal loan debt.
Take out a new personal loan, one with lower interest and fees than your current loan. By paying off the higher interest debt, you can bring down your total repayments and save money.
For credit card debt.
This may be a good option if you don't mind paying interest or you have more than a few thousand dollars' worth of debt and you're unlikely to move the full amount to a new credit card.
Apply for a lump sum to cover your credit card debt and use that money to pay off your card's balance. In exchange, you receive a regular payment structure and longer payment terms.
For personal loan and credit card debt.
You can apply to consolidate both personal loan and credit card debt at the same time with a new personal loan. It is likely you have a higher total amount of debt, so this option may work best. But don't forget to factor in any early repayment or exit fees, as this can add up across multiple accounts.
-
2
Balance transfer credit cards
For credit card debt.
This is the most common way to consolidate credit card debt. You basically have to apply for a new card and move what you already owe onto it. You can take advantage of low or 0% interest offers to pay off your debt.
For personal loan debt.
Not as common, but you can find a handful of credit card providers (Virgin Money, Qantas Money and Coles) which allow you to balance transfer personal loan debt.
You can still take advantage of promotional 0% p.a. Interest rates for set periods, but once that has finished the rate will revert back to the standard rate (usually above 20% p.a.).
It's also important to note that most credit cards only allow you to transfer about 80% of your approved credit limit. This means that even if you're approved for a $10,000 credit limit, you may only be able to transfer $8,000.
For personal loan and credit card debt.
You can apply to consolidate both personal loan and credit card debt at the same time on cards from the providers listed above. Make sure the balance transfer limit is high enough for this to work.
-
3
Refinancing through your mortgage
For personal loans, credit cards, and both.
If you have a mortgage, you have the option of taking out a home equity loan to consolidate and pay off your other debts. This option should only be used if you can be disciplined with your repayments and can build back your equity relatively quickly.
It will function as a line of credit, where you'll pay for what you borrow, not the entire credit limit given to you. This option can seem cheaper as home loans offer lower rates than personal loans or credit cards. But it is risky, difficult to manage and has no end-date. This can offset any savings earned with higher interest in the long run. Make sure you do the calculations to see if this option is economical. Interest, upfront fees and ongoing fees may be applicable.
What are the benefits of debt consolidation and what should I be aware of?
The benefits:
- Save money. By rolling all your debts into one account, you'll be paying one fee and one interest rate. This will likely reduce how much you're paying for fees and interest.
- Simplify your debts. You will have one monthly repayment to make, one lender to deal with, one set of fees to track and one rate of interest to remember.
- Pay off your debts. Instead of multiple credit accounts, you maintain a single account. You get to pay off your debts, avoid defaulting and, in the worst case, bankruptcy.
Be aware of:
- Confusing jargon. Watch out for certain "debt consolidation solutions" that are actually a Part 9 Debt Agreement. This is basically a form of bankruptcy and will have long term repercussions on your credit score.
- High rates and fees for bad credit borrowers. If you have a bad credit score, you're likely to be charged higher rates and fees.
- Paying more each month. Before you apply, calculate how much your new repayments will be to compare with what you're paying now. You may end up with higher repayments, like if you're consolidating credit card debt and have only been meeting the minimum repayments. Higher repayments may be ok if you can afford it and it means you pay off the debt faster.
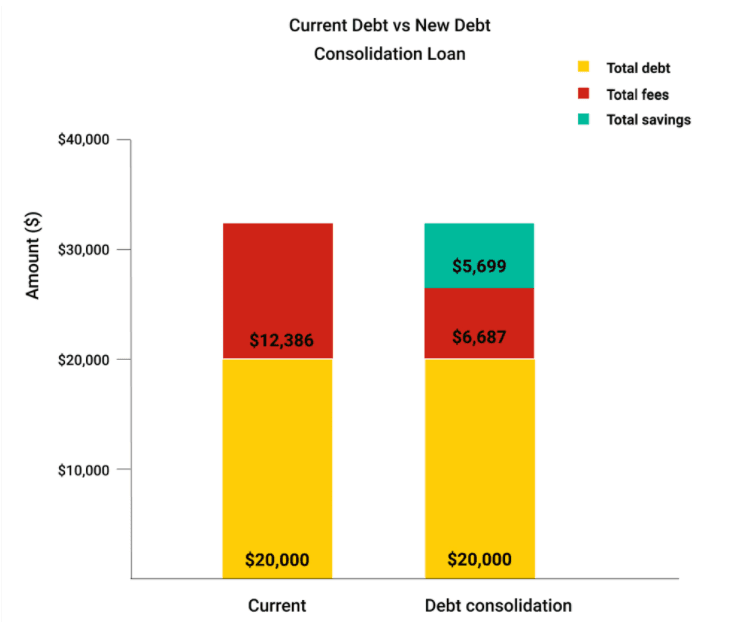
Must read: Say you have $20,000 worth of personal loan debt you wish to consolidate.
Let's say you've found a debt consolidation loan for the $20,000 debt you owe.
The new loan charges 11.99% in interest over 5 years, and doesn't charge a monthly fee. This means your monthly payments work out to $455. You would have paid $6,687 in interest.

By consolidating your debt and choosing a product with a lower rate and fees, you could save $5,699 in total. How much you can save will depend on your risk profile and eligibility, so be sure to compare your options and read the fine print.
5 things to consider before consolidating your debt
1. What you owe.
Make a list of all your debts and write down how much you owe. You can do this by signing into your online accounts or checking your current credit products on your credit report. You can check your credit report for free here.
2. How much you're paying in interest and fees.
The rationale of debt consolidation is to reduce what you're paying in interest and fees. Check what you're currently paying to ensure the new debt consolidation account is actually less.
3. Your eligibility.
Debt consolidation has its benefits, but there's no guarantee you'll be eligible. There is also no certainty that you'll be approved for the full amount needed to cover your debts. Check the minimum eligibility criteria, your credit report and the minimum and maximum borrowing limit of the option you're considering. If in doubt, ask the provider directly.
4. Whether an exit fee or penalty apply to any existing credit accounts.
Some personal loans may charge you a penalty to repay your loan early. This could offset any savings you make with a debt consolidation loan. If a fee applies to your loan, you need to ensure you're still able to save with the new loan.
5. Your credit history.
Your credit score tells the lender what kind of borrower you are and whether you're likely to make your repayments on time. They will consider your score to assess whether you're a risky borrower. Check your credit score and make sure the information in it is accurate. It will also give you an idea of your financial position and likelihood of receiving another loan.
How can I consolidate my debt if I have bad credit?
While having bad credit can limit your options, debt consolidation is still possible. It may involve entering into a Part 9 Debt Agreement, but not necessarily. You may also end up paying higher interest rates and fees.
- An unsecured personal loan with a specialist lender. Some lenders offer large, unsecured personal loans for people with bad credit. Interest rates are higher than with standard personal loans, but you may still be able to reduce what you're currently paying.
- A Part 9 Debt Agreement. This is a formal debt-relief arrangement under the Bankruptcy Act — an alternative to bankruptcy, not bankruptcy itself, but with similarly serious consequences. It's an option for people with large debts you can't repay. A registered administrator negotiates with your creditors, and your debts stop accruing interest. The agreement stays on your credit file for 5 years, affecting your credit score and future access to credit.
What happens if my application is rejected?
If your application is rejected, here's what you should do:
- Wait 3-6 months before applying for another loan. Applying for multiple loans in a short period of time can affect your credit score. Waiting before reapplying may lower your risk of rejection
- Before reapplying, look into why your application was rejected. If your credit score played a role, you can work on improving your score. Paying your bills on time and building your savings can help. Your credit report gets updated every month, so good financial habits can help improve your score.
- Keep an eye on your credit report (you can access it for free) and once you're in the clear, you can consider applying again.
- Consider paying off your small debts so that you won't have to apply for a large loan. It may be easier to get approved for smaller amounts.
Compare Debt Consolidation Personal Loans
Looking for other options? Check out these similar products.
How we picked theseFrequently asked questions about debt consolidation
-
Applying with your current bank has its advantages, but you should compare the available options to ensure you're getting the best deal. If you have a few negative listings on your credit file and have a strong past relationship with your current bank, you may stand a better chance with it. This is if your account has been kept in good standing. Speak to your lender first to determine if you're eligible.
-
It is possible take a payday loan to consolidate debt. But seeing that these loans are expensive, they may not help you save any money. You can use a payday loan for whatever purpose you see fit, but it defeats the purpose if it costs more than your current debts. Additionally, you may get into further debt and it could make your debt problem worse.
Payday loans are generally last resort loans. They are not a long-term financial solution and can often exacerbate your financial problems. What you can do is work towards improving your credit score. Pay all your bills on time, build your savings and try to pay off all your small debts. The good news is that your credit score gets updated monthly. Anything you can do to improve your score now will help you in the long term. Once your score has improved, you can check if you're eligible to apply for other debt consolidation options.
-
This can help pay off your debt sooner. If you can cut back on some spending and change your budget, you may be able to put more towards your loan. If there are no fees for making extra repayments, you could put that money into paying down your debt. If you choose to enter a debt agreement, there may be budget and spending restrictions depending on your agreement.
-
A debt consolidation loan is where you take out a loan to pay off all your other debts. It involves maintaining a single credit account. The rationale is to help you reduce how much you're paying in interest and fees. It can also help you manage your debt. You'll be paying for a single loan, with a single monthly repayment and interest rate.
A debt agreement is a formal alternative to bankruptcy, not bankruptcy itself. It's a legally binding agreement you enter into with your creditors to pay back an amount you can afford, usually over a period of up to 3 years. With it, you agree to pay a percentage of your total debt. You will have to make repayments to your debt administrator instead of individual creditors. It doesn't release you from your debts and you'll still have to pay some of it. Additionally, if you offered any assets as security, creditors can seize and sell these assets.
Unlike a debt consolidation loan, this can have long term repercussions on your credit score. It will appear in your record for 5 years or longer, affecting your chances of getting credit in the future. It will also appear on the National Personal Insolvency Index for some time.
-
Debt anxiety is a common concern. The good news is that there are free financial counsellors you can contact. They can tell you whether a debt consolidation loan is right for you, or give you advice on your financial situation. You can contact them on 1800 007 007. There are free credit and debt services available in every state and they can help you decide your best course of action.
-
Having bad debts doesn't mean you don't have rights. There are laws that control what debt collectors can and cannot do.
Debt collectors cannot excessively harass, threaten or bully you. They are only supposed to contact you during certain hours of the day (7:30am–9:00pm on weekdays and 9:00am–9:00pm on weekends). Keep a log of the dates and times you were contacted, along with other specifics. This will come in handy if you have to file a complaint with a consumer protection agency like the Australian Competition and Consumer Commission (ACCC).
Check your bill records if you receive a call. Ask for a detailed statement of what they say you owe. If the debt is a loan, ask for a copy of the paperwork. A collector must always identify themselves and state why they are contacting you. They should be prepared to provide you with account information and should offer a repayment or settlement plan.
Figure out what you must spend to get by. This includes food, rent, car, utilities, etc. It is good practice to set up an appointment with a non-profit debt counsellor before making any promises or commitments to a collector.
Always make sure you're dealing with a licensed credit provider or broker. Some operate illegally without licences. You can check ASIC's Professional Registers to see if they're registered.
-
Finder writers are subject matter experts and use primary sources, in-depth research and interviews with other experts to ensure you're getting accurate, up-to-date information. Articles are fact checked in line with our editorial guidelines.
Rebecca Pike is Finder’s money editor, with over 7 years of experience in mortgages and personal finance. A frequent TV and radio commentator, she frequently appears on Sunrise and 7News, Today and 9News, as well as Sky News, Channel 10 and across radio and print. Rebecca previously served as Editor of Mortgage Professional Australia. She has a Master’s degree in Journalism as well as ASIC-recognised certifications in Tier 1 Generic Knowledge and Tier 2 General Advice Deposit Products, which comply with ASIC guidelines. See full bio
- Home loans
- Personal Loans
- Car Loans
- Cost of living
- Budgeting
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
Read more on Personal Loans
-
Salt and Lime Debt Consolidation Loan
Looking to consolidate your debt? Salt and Lime offers fee-free loans, same-day funding, and the ability to earn discounts on your interest over the life of the loan. Apply today.
-
Insolvency vs bankruptcy
Want to understand the differences between personal insolvency and bankruptcy and what both of these terms mean for your financial future? Find out here.
-
What are the consequences of bankruptcy in Australia?
This guide will take you through the consequences of bankruptcy so you can decide if it's the right option for you.
-
Debt negotiation
What is debt negotiation and how can it help you? Find out here.
-
Fox Symes Debt Consolidation Solutions
If you're juggling multiple debts and struggling with your repayments each month, a debt consolidation loan from Fox Symes may be an option for consider. Find out what's involved with its debt consolidation personal loan in our guide and if its right for you.
Hi how do i get help to roll all my bills into one det iv applied with two other people who cold not help me out if you can please help thank you
Hi Henrietta,
Your debt consolidation loan options are listed on the page above, but you may not have been approved because you did not meet the lender’s eligibility criteria or that you asked for a loan amount that the lender determined you could not afford. Now you have two recent credit enquiries on your file it will affect your chances of being approved. You may want to consider waiting a few months to apply again, or call the lender directly to discuss your eligibility for the loan. Criteria is also listed on each finder review page.
Hope this helps,
Elizabeth
Hi Harrietta,
Thanks for your comment. Finder is not a lender so we can’t consolidate your debts, rather provide general information on the process.
Each company considers your debt consolidation needs differently and will rely on a range of factors when considering your application.
If you want, you can read our guide on personal loan rejection to find more information.
I am trying to apply for a house.they declined me and said is because of 3 account which I fine it very hard to pay it off but I made arrangement.I pay certain amount on each account but still they declaim my application. Please help me how to get approval I really want a house
Hi Tinyiko,
Thanks for your enquiry, and sorry to hear about your situation.
You might be interested to read our tips about how to get approved for a home loan with bad credit. You can also compare the range of specialist lenders that may be more likely to review your application given that you have some enquiries against your credit file.
Keep in mind that while debt consolidation can make it easier to manage your finances, you may also have to pay a higher interest rate over the life of the loan.
I recommend getting in touch with a licensed mortgage broker A broker can help you understand your financial position and they can leverage their panel of networks to find a lender that’s more inclined to review your application.
Before applying, please ensure that you meet all the eligibility criteria and read through the details of the needed requirements as well as the relevant Product Disclosure Statements/Terms and Conditions when comparing your options before making a decision on whether it is right for you.
All the best,
Belinda
Can i get a loan or credit card to pay off debt so i only have 1 loan or credit card repayment? I’m falling more and more behind in payments and just want the debt settled as quick as possible.
Thank you!
Hi CK,
Thanks for your question.
There are a few debt consolidation loans you can consider. To check the eligibility and the details of the loan, select the title of the loan in the table. You can also apply by clicking ‘Go to Site’ once you have found the loan you want to apply for. If you want to balance transfer your personal loan debt, you can compare your options from credit cards that allow balance transfers from a personal loan. Before applying, please ensure that you meet all the eligibility criteria and read through the details of the needed requirements as well as the relevant Product Disclosure Statements/Terms and Conditions when comparing your options before making a decision on whether it is right for you.
I hope this has helped.
Thanks,
Elizabeth
I would like to know the names of some lenders who help people with debt consolidation loans when they have bad credit. Thanks
Hi Kirsty,
Thanks for your question.
You may refer to our debt consolidation loans for borrowers with bad credit history. You can select the “Go to Site” button of your preferred lender to proceed with your application. You can also contact the lender directly if you have specific questions about the loan. Please ensure to read through the relevant product disclosure statement and terms and conditions of the loan.
I hope this will help.
Thanks,
Elizabeth
Hi there,
Its really confusing me, but could anyone give me an advise?
The thing is that my Mom has a credit balance of $20000 and so does my dad. Which adds up to $40,000.
We don’t have a house, we are renting. But we want to take a home loan to offset it and then buy a house. But we are really lost. We don’t know any solution.
Hi Akki,
Thanks for your question.
If your parents are currently in debt, you will find that your options are somewhat limited as lenders are not prepared to take on this extra debt.
If you find that none of these loans are suitable for your situation, there is always the option of speaking to a home loan broker. They will be able to help you further in narrowing down a suitable home loan option for you.
Cheers,
Shirley