There’s now 82% chance of an RBA rate hike in September, and this is why

Key takeaways
- The IMF has just warned that the RBA could lift interest rates on September 29 due to persistent underlying inflation.
- Financial markets are currently pricing an 82% chance of an increase of 25 basis points.
- For a $1 million mortgage, the impact is ~$150 a month*, but you may have options including refinancing, speaking to your bank and applying for hardship.
Unfortunately, I think we can stop calling a September interest rate hike a "maybe".
Until now, I've been sitting firmly in the "wait and see" camp. But the case for another rate hike has just got a lot stronger.
And it's not because of one thing, it's because of three.
Warning shot #1: The International Monetary Fund (IMF)
In the last 24 hours, the IMF has just warned that persistent underlying inflation could require further tightening in Australia. Translation: the Reserve Bank of Australia should be ready to raise rates again if needed, and they don't mean only once.
Warning shot #2: The financial markets
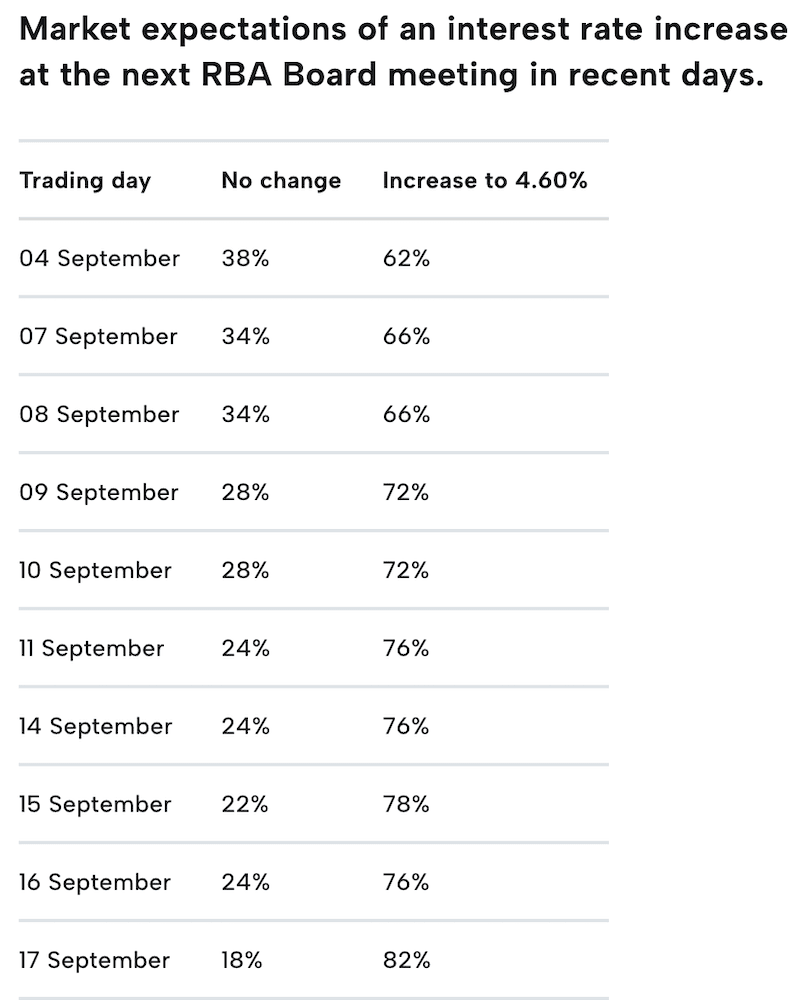
Financial markets are increasingly convinced a September rate increase is coming.
Looking at the ASX RBA Rate Tracker, markets are currently pricing an 82% chance of an increase. The expectation is a 0.25 percentage point increase at the September meeting, taking the cash rate from 4.35% to 4.60%.
That's a fairly big shift from the 62% chance of increase the market was expecting 2 weeks ago.
Warning shot #3: The RBA
Then came comments from RBA Governor Michele Bullock today that made me sit up.
She said several of the inflation risks the RBA had been watching have started to materialise. These include the impact of the Middle East conflict on energy prices (petrol in my area was 2.44c/l today) and the huge investment boom in AI and data centres.
Inflation is already running above the RBA's target, and Bullock is worried it's going to run even hotter.
"I recognise that higher interest rates are difficult for Australians with mortgages who are also facing cost-of-living pressures," she said.
"But reducing inflation is essential. High inflation hurts all Australians and is especially tough on people with lower incomes and those in vulnerable financial positions."
Is a September rate hike locked in?
No, because it's never a sure thing. There's over a week between now and the Reserve Bank's meetings on 28 and 29 September.
That means there's still time for more data to drop, or conditions to change, or for volatility in the geopolitical climate to see us chart a different course.
That said, the RBA has made it pretty clear that getting inflation back under control is its priority. Assistant Governor Sarah Hunter said earlier this month that inflation was the Board's "top priority".
What should you do about your mortgage?
If the RBA does lift the cash rate by 0.25 percentage points, your home loan repayments will nudge up.
For a $1 million mortgage, the impact is roughly $150 a month*.
You have a few options. You could:
- Call your bank. Check if you're ahead on repayments, or if you can get a cheaper interest rate, or go on a mortgage repayment holiday. You may qualify for hardship relief, too. If a phone call is too intimidating, put your request in writing via email.
- Take charge and refinance. You could refinance your home to a new lender, getting home loan cashback of up to $4,000 along the way. This is worth investigating if you want to unlock some equity to pay off other debts or invest in a renovation.
- Cut back on spending. This depends on your income and situation. For some, $150 a month is as simple as one less restaurant meal. For others, it's a decent chunk of the fortnightly supermarket budget. Those who have the luxury of cutting back on discretionary spending would be prudent to do so now to manage the higher mortgage repayments.
- Do nothing. As one Redditor put it; "There's nothing I can do about it, and I still need to live somewhere… I've decided to tune out from the news media doom and gloom. The bank will automatically adjust my rate and repayments and life goes on."
One last thing…
This may not be the last RBA hike we see this year.
The IMF hasn't said the RBA definitely needs to keep hiking. But it is saying it's a possibility, and that the RBA should be prepared to increase rates again if inflation remains stubbornly high.
All the Big 4 Banks expect one more rate rise before Christmas, and financial markets are pricing in the possibility of a 4.85% cash rate by early 2027.
My suggestion is to prepare as if getting two more rate rises is a sure thing. Rates hopefully won't stay this stubbornly high for long, but if they do, now is the time to prepare for future financial pressure.
* For a borrower with a $1,000,000, 30-year mortgage, a full 0.25 percentage point increase would add roughly $100 a month to repayments, assuming the loan is principal and interest.
Sources
Ask a question