Investment home loan rates

Pay less with a better investment loan. Rates, fees & overall score updated daily for 3,000+ loans.

4.6 based on 837 reviews
$
years
Finder Score Interest Rate p.a. Comparison Rate p.a. Fees Features Credit licence Monthly Payment
Finder score
Interest Rate
6.54%
Comparison Rate
6.45%
Fees
  • Application: $0
  • Ongoing: $0 p.a.
Principal & Interest20% min. equityInvestmentOnline exclusive
Monthly Payment
$3,494
per month
$1,000$1,000 Reward

Finder Rewards: Join Finder then refinance an eligible home loan to receive a $1,000 digital Visa gift card. Ends 30 Nov 2026. T&Cs apply.

Referral bonus: Finder's Refer-a-Friend boost pays up to $500 when a person you refer qualifies for an Unloan home loan. Ends 30 Nov 2026. T&Cs apply.

Fees & charges apply. Australian Credit Licence 234945

Go to siteView details
Compare product selection
Finder score
Interest Rate
6.49%
Comparison Rate
6.51%
Fees
  • Application: $0
  • Ongoing: $0 p.a.
Principal & Interest20% min. equityInvestmentPoints
Monthly Payment
$3,476
per month
Points: Earn 1,000 Virgin Money Reward points per borrower for each on-time monthly repayment. Rewards terms and conditions apply.

Fees & charges apply. Australian Credit Licence 244616

Go to siteView details
Compare product selection
Finder score
Interest Rate
6.64%
Comparison Rate
6.65%
Fees
  • Application: $0
  • Ongoing: $0 p.a.
Principal & Interest30% min. equityInvestmentOnline exclusive

Fees & charges apply. Australian Credit Licence 233714

Monthly Payment
$3,531
per month
Go to siteView details
Compare product selection
Macquarie Bank logo
Finder score
Macquarie Bank Offset Home Loan Package
Finder score
Interest Rate
6.69%
Comparison Rate
6.93%
Fees
  • Application: $0
  • Ongoing: $248 p.a.
Principal & Interest30% min. equityInvestmentOffset account

Fees & charges apply. Australian Credit Licence 237502

Monthly Payment
$3,549
per month
View details
Compare product selection
IMB logo
Finder score
IMB Fixed Rate Home Loan
Finder score
Interest Rate
6.59%
Comparison Rate
6.99%
Fees
  • Application: $449
  • Ongoing: $72 p.a.
Principal & Interest 3Y Fixed10% min. equityInvestmentLMI
Monthly Payment
$3,513
per month
Cashback: Get up to $4,000 cashback when buying or refinancing. Loan size criteria applies. T&Cs apply.

Fees & charges apply. Australian Credit Licence 237391

View details
Compare product selection
Up Home Loan logo
Finder score
Up Home Invest Variable Rate
Finder score
Interest Rate
6.60%
Comparison Rate
6.60%
Fees
  • Application: $0
  • Ongoing: $0 p.a.
Principal & Interest10% min. equityInvestmentOffset accountLMIOnline exclusive

Fees & charges apply. Australian Credit Licence 237879

Monthly Payment
$3,516
per month
Go to siteView details
Compare product selection
Newcastle Permanent logo
Finder score
Newcastle Permanent Real Deal Home Loan
Finder score
Interest Rate
6.69%
Comparison Rate
6.73%
Fees
  • Application: $350
  • Ongoing: $0 p.a.
Principal & Interest20% min. equityInvestment
Monthly Payment
$3,549
per month
Cashback: Eligible purchases and refinancers can get up to $3,000 cashback depending on loan value with LVR 80% or less. Application must be completed online. T&Cs apply.

Fees & charges apply. Australian Credit Licence 238273

Go to siteView details
Compare product selection
Macquarie Bank logo
Finder score
Macquarie Bank Basic Home Loan
Finder score
Interest Rate
6.74%
Comparison Rate
6.77%
Fees
  • Application: $0
  • Ongoing: $0 p.a.
Principal & Interest20% min. equityInvestment

Fees & charges apply. Australian Credit Licence 237502

Monthly Payment
$3,567
per month
View details
Compare product selection
loans.com.au logo
Finder score
loans.com.au Variable Bare Home Loan
Finder score
Interest Rate
6.74%
Comparison Rate
6.78%
Fees
  • Application: $0
  • Ongoing: $0 p.a.
Principal & Interest10% min. equityInvestmentLMI

Fees & charges apply. Australian Credit Licence 395219

Monthly Payment
$3,567
per month
View details
Compare product selection
Cairns Bank logo
Finder score
Cairns Bank Plus Fixed Home Loan
Finder score
Interest Rate
6.69%
Comparison Rate
7.14%
Fees
  • Application: $0
  • Ongoing: $395 p.a.
Principal & Interest 3Y Fixed40% min. equityInvestmentOffset account

Fees & charges apply. Australian Credit Licence 244324

Monthly Payment
$3,549
per month
View details
Compare product selection
Qantas Money logo
Finder score
Qantas Money Basic Variable Home Loan
Finder score
Interest Rate
6.79%
Comparison Rate
6.86%
Fees
  • Application: $495
  • Ongoing: $0 p.a.
Principal & Interest20% min. equityInvestmentOnline exclusive

Fees & charges apply. Australian Credit Licence 237879

Monthly Payment
$3,585
per month
View details
Compare product selection
Cairns Bank logo
Finder score
Cairns Bank Plus Fixed Home Loan
Finder score
Interest Rate
6.64%
Comparison Rate
7.17%
Fees
  • Application: $0
  • Ongoing: $395 p.a.
Principal & Interest 2Y Fixed20% min. equityInvestmentOffset account

Fees & charges apply. Australian Credit Licence 244324

Monthly Payment
$3,531
per month
View details
Compare product selection
Bank of China logo
Finder score
Bank of China Discount Plus Home Loan
Finder score
Interest Rate
6.83%
Comparison Rate
7.20%
Fees
  • Application: $0
  • Ongoing: $0 p.a.
Interest only20% min. equityInvestmentOffset account

Fees & charges apply. Australian Credit Licence 287322

Monthly Payment
$3,600
per month
View details
Compare product selection
Macquarie Bank logo
Finder score
Macquarie Bank Offset Home Loan Package
Finder score
Interest Rate
6.74%
Comparison Rate
6.98%
Fees
  • Application: $0
  • Ongoing: $248 p.a.
Principal & Interest20% min. equityInvestmentOffset account

Fees & charges apply. Australian Credit Licence 237502

Monthly Payment
$3,567
per month
View details
Compare product selection
Qantas Money logo
Finder score
Qantas Money Basic Variable Home Loan
Finder score
Interest Rate
6.94%
Comparison Rate
6.92%
Fees
  • Application: $495
  • Ongoing: $0 p.a.
Interest only20% min. equityInvestmentOnline exclusive

Fees & charges apply. Australian Credit Licence 237879

Monthly Payment
$3,641
per month
View details
Compare product selection
Macquarie Bank logo
Finder score
Macquarie Bank Basic Fixed Home Loan
Finder score
Interest Rate
6.79%
Comparison Rate
6.78%
Fees
  • Application: $0
  • Ongoing: $0 p.a.
Principal & Interest 3Y Fixed20% min. equityInvestment

Fees & charges apply. Australian Credit Licence 237502

Monthly Payment
$3,585
per month
View details
Compare product selection
loading
Showing 16 of 3,701 results

Key takeaways

  • Investment loans have higher interest rates than owner-occupier loans. The average investor loan rate in Finder's database is currently 7.45%.
  • Getting an investment loan is more difficult as lenders often require a 20% deposit and have limits on the amount of high debt-to-income loans they can issue.
  • High interest rates also make investment loans more expensive, reducing an investor's borrowing power.

The best investment loans for November 2026

The average property investor now takes out a loan of about $691,000 to fund their investment, according to ABS lending figures.

And while interest rates are still high across the board, several lenders are offering very competitive rates for investors.

Here are 5 of the best variable investment loans for November 2026, based on their Finder Scores:

  • Unloan Variable Home Loan (min 20% equity) (Investor, P&I) has a Finder Score of 9.6. It has a 6.54% interest rate for investors (comparison rate 6.45%).
  • Up Home Loan Variable Rate (min 10% equity) (Investor, P&I) has a Finder Score of 9.6. It has a 6.6% interest rate for investors (comparison rate 6.6%).
  • Virgin Money Lite Variable Home Loan $150,000+ (min 20% equity) (Investor, P&I) has a Finder Score of 9.1. It has a 6.49% interest rate for investors (comparison rate 6.51%).
  • Newcastle Permanent Real Deal Home Loan - Special Offer 1 (min 20% equity) (Investor, P&I) has a Finder Score of 9. It has a 6.69% interest rate for investors (comparison rate 6.73%).
  • Westpac Flexi First Option Investment Loan – Online Investor Variable Rate (min 30% equity) (Investor, P&I) has a Finder Score of 8.9. It has a 6.64% interest rate for investors (comparison rate 6.65%).

How we picked these loans

Every month we analyse the investment loans in Finder's database and pick the best loans based on their Finder Scores, selecting principal-and-interest investor loans with LVRs of 30% or lower. Learn more about how the Finder Score works.

Where are rates heading?

The Reserve Bank of Australia raised the cash rate five times in 2026, adding 125 basis points to most borrowers' home loans. This has pushed up borrowing costs for property investors. And there may be more rate rises to come.

Fixed rates can hint at where rates are heading

When ING lifted its fixed rates in September 2026, Finder's money and home loans expert Richard Whitten told 9News: "Banks are experts at forecasting and setting interest rates in line with the market. They lower fixed rates when they anticipate interest rates to fall further, and lift them when they expect rates to rise."

What are investment loans?

An investment loan is a loan you can use to purchase an investment property. That is, a property you intend to rent out. Investment loans have higher interest rates than owner-occupier loans because lenders view investors as riskier borrowers.

Investment loans: Basic facts

Rate

Fixed or variable rates

Investors can choose fixed or variable repayments. Variable rate loans are easier to pay off faster or refinance without an exit fee.

But a fixed rate loan lets you lock in an interest rate and forget about rates rising. There's also the option of splitting your loan into fixed and variable portions.

Thinking

Interest-only repayments

Most owner-occupier borrowers choose principal-and-interest repayments. You borrow money and pay it back, plus interest. Investors can do this too. But they have another option.

Interest-only investment loans start with very low repayments because you're just paying the interest charges. These loans cost you more in the long run. But they let investors maximise their tax-deductible debts in the short term.

House

Tax deductions

As an investor, most expenses related to owning and maintaining your investment property are tax-deductible.

This includes your loan fees and your loan interest charges. If your investment costs you more than it generates in rent, you can offset the cost by reducing your tax bill. From the 2027–28 income year, this negative gearing benefit is limited to new builds and properties held before 7:30pm AEST on 12 May 2026. Losses on established properties bought after that can't be offset against your salary or other income.

Investor loans versus owner-occupier loans

FeatureInvestor loansOwner occupier loans
PurposeYou have to use the loan to purchase an investment property, not your place of residence.You need to live in the property you're buying.
DepositIt's not impossible to get an investment loan with a 5% deposit, but you'll have an easier time if you've saved between 10 and 20%.You can get a home loan with as little as a 5% deposit (plus LMI).
Interest rateInterest rates are typically 20+ basis points higher than a comparable owner-occupier rate (based on analysis of Finder data)Owner-occupier loans have the lowest rates on the market compared to investment loans. But you should still compare your options.
Loan approvalLenders have stricter eligibility requirements for investors. A lender may require a higher income or restrict how much you can borrow.An owner-occupier loan is generally easier to get approved for. But your income, spending habits and the property you're buying still matter.
Tax deductionsAny loan fees, interest charges and other borrowing costs are tax-deductible (but not stamp duty).Your loan costs are not tax-deductible as a homeowner (sorry!).
FeaturesInvestor loans can come with all the same features other home loans have, like offset accounts and redraw facilities.Many owner-occupier loans come with offset accounts, and almost all variable rate loans let you make extra repayments and redraw them.

Can I get an investment loan?

There are fewer investors in the market at the moment, and it's harder to get an investment loan due to lending restrictions and higher rates. But it's absolutely possible to get an investment loan.

APRA's lending restrictions

Since February 2026, the Australian Prudential Regulation Authority (APRA) has limited the amount of "high debt-to-income" (DTI) home loans lenders can issue.

Now, only 20% of a bank's new mortgages can go to borrowers with a debt-to-income (DTI) ratio that is six or more times their gross annual income.

While this is not aimed at investment lending specifically, the cap is much more likely to affect borrowers who are highly leveraged and have multiple mortgages. In other words, property investors.

Once a lender reaches its limit, it may turn down your application or offer you a smaller loan.

The serviceability buffer

APRA also requires lenders to apply a 3% serviceability buffer on loan applications. This means that if you're applying for a loan with a rate of 6%, your lender must add a 3% buffer and test your ability to repay the loan with a 9% interest rate.

This is to ensure the borrower can still afford the loan if rates rise. Again, this is not targeted at investor loans specifically. But investment loans have higher interest rates, so this 3% buffer makes it even harder to qualify for an investment loan.

How to improve your chance of approval

You can maximise your chances of approval for any loan by:

  1. Reducing your spending in the months before you apply for a loan.
  2. Reducing your existing debts by paying them off or reducing the limit on your credit card.
  3. Checking your credit score and seeing if you have any errors or issues dragging down your profile.
  4. Increasing your deposit size and reducing your loan amount.

How do I compare investment loans?

  • Interest rate: A lower interest rate means lower loan repayments.
  • Fees: Take a look at fees that might come with the loan. Avoiding fees can make your loan cheaper.
  • Loan features: Mortgage features like an offset account can help you build up savings while reducing your interest charges. Offset accounts can be very helpful for investors planning to convert their home into an investment later.
  • LVR: Loan to value ratio (LVR) is the amount you can borrow relative to the value of your investment property. If you have a smaller deposit, compare which lenders allow high LVRs. But remember, the smaller your deposit, the more you have to borrow and the higher your costs will be.
  • Borrowing capacity: Every lender has different lending criteria. Compare lenders to get an estimate of your borrowing power before deciding on a particular loan or lender.

How your interest rate changes the cost

Here's a simple example of how the interest rate affects your loan repayments each month and the total interest you pay over 30 years.

Loan amountInterest rateMonthly repaymentInterest over 30 years
$600,0006.00%$3,598$695,030
$600,0006.25%$3,695$729,950
$600,0006.50%$3,793$765,267
$600,0006.75%$3,892$800,972
$600,0007.00%$3,992$837,054

These calculations don't take loan fees or extra repayments into account and assume that the interest rate doesn't change over 30 years.
How do I apply for an investment property loan?

Lenders treat investment properties as higher-risk purchases, which means it can be more complicated to get an investment loan approved.

Here are 6 tips to make your investment loan application a success:

1. Save a bigger deposit.

A 20% deposit is a big ask, but it makes you a less risky borrower (and lets you save on LMI).

2. Check your credit score.

A quick check of your credit score is always a good idea. Sometimes there are red flags or errors you might not have noticed. If it's not in great shape, it's time to start improving it.

3. Trim your spending.

Cutting back on unnecessary purchases in the 3 months leading up to your application boosts your chances of approval.

Mortgage-free by retirement? It depends on your pay
Income makes a bigger difference to your mortgage-free timeline than most people expect. 76% of Australians earning $200,000-plus expect to pay off their mortgage before retirement, compared to just 25% of those earning under $50,000. That's worth keeping in mind if you're weighing up an investment loan on top of an existing mortgage. The right loan structure can help keep a debt-free timeline realistic.

4. Compare loans and lenders.

Every lender has different eligibility criteria. Some may be stricter when lending to investors.

5. Choose your property carefully.

If the property you're buying looks like a riskier investment due to its size, property type or location, the lender might reject your application.

6. Talk to a mortgage broker.

A qualified broker can help match you up with a bank or lender whose policies and criteria best suit your personal situation.

Matt Corke's headshot

"My mortgage broker suggested I go on an interest only investment property loan as it would keep down the costs, and the interest can be claimed at tax time."

Head of Publishing Ventures

Risks and benefits of investing in property

Property investment can be both risky and rewarding. Here are some of the potential risks and benefits you should think about:

Benefits

  • Rental income. You can earn rental income that puts cash in your pocket right away.
  • Capital gain. If you hold the property for a long time, it could grow in value significantly.
  • Tax and depreciation benefits. You can deduct investment loan interest charges and other investment costs at tax time, making the cost of owning a property far more affordable. From the 2027–28 income year, losses on established properties bought after 12 May 2026 can't be offset against your other income.
  • The potential to add value. Unlike shares or other investments, you may be able to increase your investment's value through renovations.

Risks

  • Purchase costs. There are also many upfront costs for investors, including lenders mortgage insurance (LMI), stamp duty, building and pest inspections, conveyancing and legal charges.
  • Ongoing costs. There are many ongoing costs such as repairs, strata fees and council rates.
  • Managing tenants. Being a landlord means dealing with the tenants in the property.
  • Illiquid asset. It can take months to sell an investment property if you need to generate cash.

Negative gearing and capital gains tax changes

In the May 2026 federal budget the government announced major changes aimed at reducing the tax benefits property investors receive.

Negative gearing

Negative gearing allows investors to reduce their taxable income if their investment property costs outweigh the income. From 1 July 2027, negative gearing is only allowed on newly-built investment properties.

After the cut-off date, investors can still offset investment losses against residential property income or gains, and can be carried forward.

Existing investors who held investment properties before 12 May 2026 can still benefit from the existing negative gearing rules.

Capital gains tax discount

From 1 July 2027, the 50% capital gains tax discount will be replaced by a cost base indexation method that taxes investors on their real gains when a property is sold, minus inflation. There's also a minimum 30% tax on capital gains regardless of the cost base indexation.

Any capital gains made before July 2027 can keep the 50% discount.

Investors selling newly-built investment properties can choose the old 50% discount or the cost base indexation method.

In effect, this change means most property investors will pay a lot more tax when they sell an investment property for a substantial gain. Although it applies to other investments like shares too.

Nicole Pedersen-McKinnon's headshot
Expert insight

"Common wisdom is to opt for an interest-only investment loan so you maximise your tax deductions. And it's a sound approach. The only exception is if you have already paid off the mortgage on your own home. This is not tax-deductible. At that stage, consider going principal and interest and throwing all the money you can at that investment loan to create a debt-free source of income in retirement."

Nicole Pedersen-McKinnon's headshot
Nicole Pedersen-McKinnon
Finance journalist

Investment loan guides and resources

What is Finder Score?

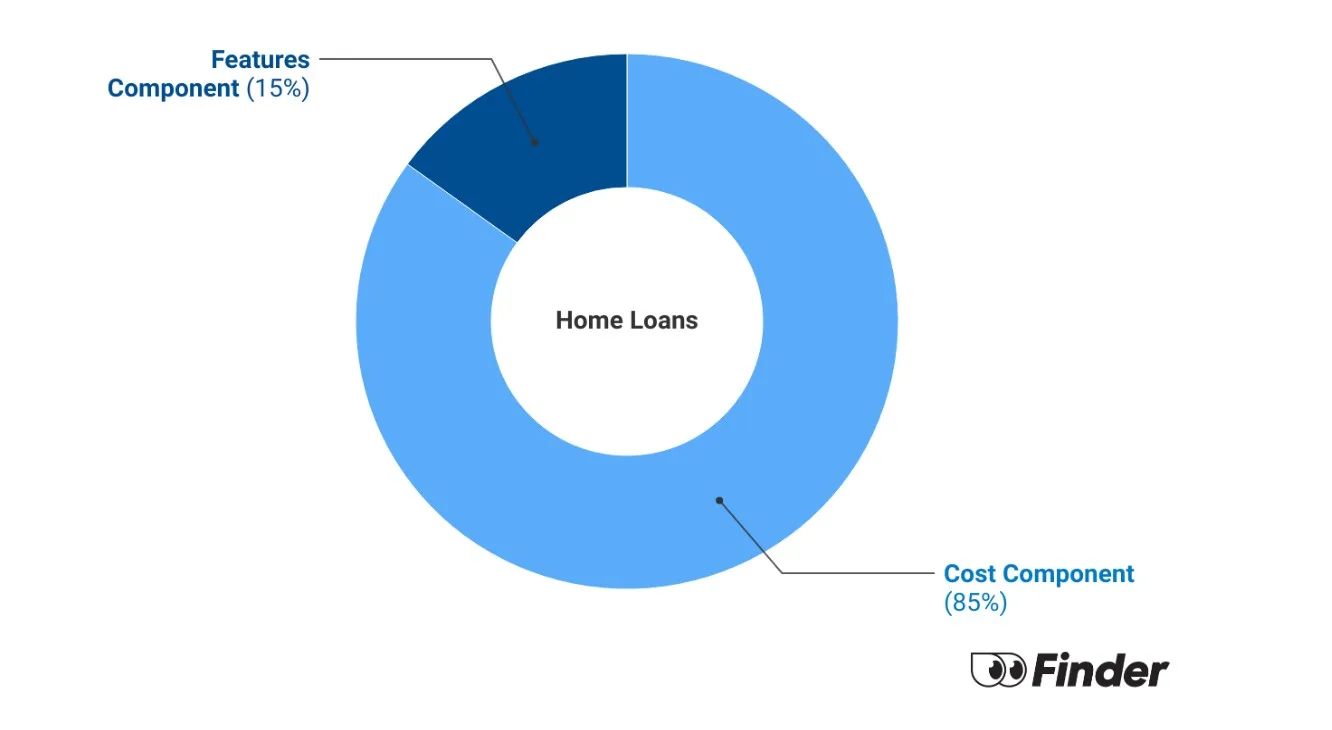
The Finder Score crunches 7,000 home loans across 120+ lenders. It takes into account the product's interest rate, fees and features, as well as the type of loan eg investor, variable, fixed rate - this gives you a simple score out of 10.

To provide a Score, we compare like-for-like loans. So if you're comparing the best home loans for cashback, you can see how each home loan stacks up against other home loans with the same borrower type, rate type and repayment type. We also take into consideration the amount of cashback offered when calculating the Score so you can tell if it's really worth it.

Read the full breakdown

Frequently asked questions

Sarah Megginson's headshot
To make sure you get accurate and helpful information, this guide has been edited by Sarah Megginson as part of our fact-checking process.
Rebecca Pike's headshot

Rebecca Pike is Finder’s money editor, with over 7 years of experience in mortgages and personal finance. A frequent TV and radio commentator, she frequently appears on Sunrise and 7News, Today and 9News, as well as Sky News, Channel 10 and across radio and print. Rebecca previously served as Editor of Mortgage Professional Australia. She has a Master’s degree in Journalism as well as ASIC-recognised certifications in Tier 1 Generic Knowledge and Tier 2 General Advice Deposit Products, which comply with ASIC guidelines. See full bio

Rebecca's expertise
Rebecca has written 253 Finder guides across topics including:
  • Home loans
  • Personal Loans
  • Car Loans
  • Cost of living
  • Budgeting

Get rewarded $$ for switching with Finder Rewards

Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.

More guides on Finder

Go to site