Get up to 15% off your TAL Life, Trauma or TPD insurance policy for life - if you have a Body Mass Index (BMI) between 19 and 28 at the time of your application.
Your family could have 2 chances to save on its insurance: Your first month is free and, by taking out a second life policy, you can get a 10% discount on that policy.
Zurich offers premium suspension cover of up to 12 months to help you if you're struggling financially. Most insurers don't offer this.
A $15,000 payout for funeral costs is competitive.
What you're covered for
Max cover: $1,500,000
Funeral benefit: $15,000
Optional TPD cover: No
Optional trauma cover: No
Current offer:
Get your first month free, plus a complimentary legal will. For policyholders who purchase an eligible Ezicover Life Insurance or Income Protection policy from 27 Jan 2023 and maintain cover for at least 12 months. Offer must be redeemed while the policy remains active. T&Cs apply.
Good discounts on offer: 1 month free if you pay annually, 5% multi-life policy discount.
AAMI has a competitive maximum cover of $1.5 million, consistent with other brands in the market.
AAMI won Most Loved Life Insurance - Direct in Finder's 2026 Customer Satisfaction Awards. It scored highly for customer service, features and benefits, ease of application, value for money and reliability.
What you're covered for
Max cover: $1,500,000
Funeral benefit: $10,000
Optional TPD cover: No
Optional trauma cover: Yes
Current offer:
Get a $100 first year discount when you take out a new AAMI Life Insurance policy. T&Cs apply.
Life cover, also known as "death cover" provides a lump sum payment to your beneficiaries when you pass away. Life cover is designed to financially support your loved ones and allow them to maintain their lifestyle when you are no longer around.
There are a few different types of life cover available, including:
Total and permanent disability (TPD) insurance. Provides a lump sum payment if you become totally and permanently disabled and are unable to work again. This cover can help pay off debts such as a mortgage, fund medical and rehabilitation costs and support your ongoing living expenses.
Income protection insurance. Replaces a portion of your income if you're unable to work due to illness or injury. It helps you continue meeting everyday expenses like rent, bills and groceries while you recover and return to work.
Critical illness insurance. Pays a lump sum if you're diagnosed with a specified serious illness, such as cancer, heart attack or stroke. This cover can be used for medical treatment, recovery costs or to ease financial pressure while you focus on your health.
How to compare life cover
Comparing life cover helps you find a policy that suits your needs and budget. While price is important, it's also essential to understand what you're actually covered for.
When comparing life cover policies, consider:
The type of cover offered (life, TPD, income protection or critical illness)
The amount of cover and benefit payments
What is included and excluded in the policy
Waiting periods, benefit periods and claim conditions
Premium structure (stepped vs level premiums)
The insurer's claims process and reputation
Taking the time to compare policies can help ensure you choose cover that provides the right level of protection when you need it most.
FAQs
Life cover, also known as life insurance, provides a lump sum payment to your nominated beneficiaries if you pass away or are diagnosed with a terminal illness. The payment can help your loved ones manage financial commitments, like your home loan, everyday living expenses, debts and future costs during a difficult time.
There are several types of life cover available, including life insurance, TPD insurance, income protection insurance and critical illness insurance. Each type of cover serves a different purpose, and many people choose a combination to ensure comprehensive financial protection.
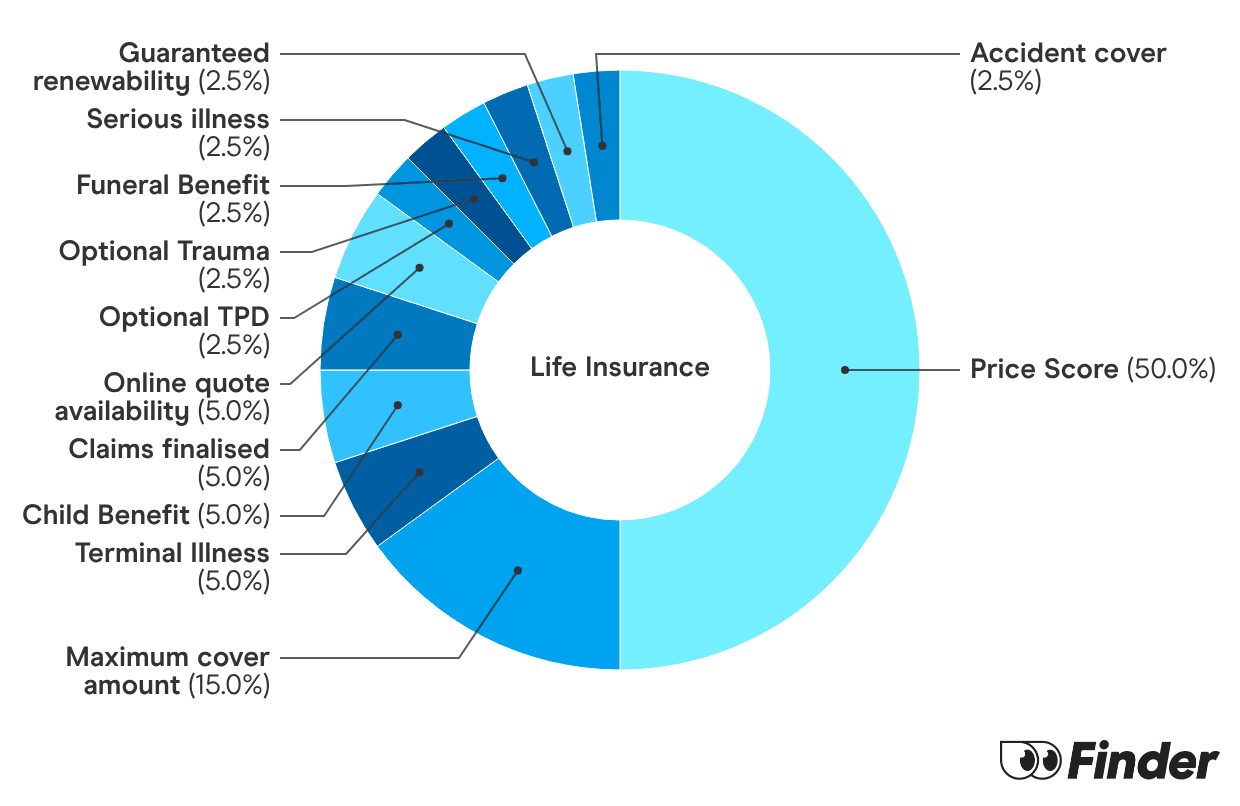
The best life insurance for you will depend on your personal profile and budget, however, we've done some research to help get you started. In 2026, TAL life insurance was the winner of our best life insurance award. This is because TAL offers competitive pricing and extensive benefit limits. In short; it's well priced for such a good product. Keep in mind, you should always get your own quote and read through the product disclosure statement to know if this product offers the kind of coverage you're looking for.
To be straight with you, only you can answer this one. Life insurance is one of those products you hope you never have to use because for it to ever be used, something terrible has to happen first. However, you may deem it 'worth it' for the peace of mind it brings you and your family. Life insurance can cover the cost of major debts like your mortgage in the event you're unable to do so yourself. For many, knowing your family would be financially stable in the event of your passing makes life insurance worth it. If you're not sure whether or not life insurance is necessary for you, this article can help you assess your needs and what your family would need in the event of your passing.
A life insurance payout goes to the beneficiary; this is the person you choose at the time of taking out your policy. In the event of your death, the beneficiary — which can be 1 person or a selection of people — would get the payout.
If you cancel your life insurance, you will no longer be covered as of the date you cancel. If you've paid your premium in advance then you may be refunded for the unused portion of it, minus any cancellation fees you may owe.
It's an individual assessment depending on your cashflow, retirement funding and tax situation. While it's often cheaper and easier to hold life insurance within super, it reduces the amount in your retirement fund. Additionally, the payout is usually small and life cover in super usually ends at age 70 (TPD cover in super usually ends at 65), according to ASIC's MoneySmart. With a traditional life insurance policy, the expiry age is usually around 99 or there is no expiry age at all, as long as you keep paying your premiums.
Yes, it is possible. If you have a pre-existing medical condition, there are insurers who will still cover you. But they might ask you to pay slightly higher premiums or exclude that condition from your cover. It's really important to disclose any condition you have when you apply for life insurance. Not doing so could void your cover.
Child life insurance is a feature you can add to your life insurance policy for an added fee. It will pay out a financial benefit if your child dies or suffers a serious medical condition.
Peta Taylor is a publisher at Finder, working across all of insurance. She's been analysing product disclosure statements and publishing articles for over 2 years. Peta is passionate about demystifying complex insurance products to help users make well educated decisions with confidence. Peta is part of Finder's insurance awards team and works alongside editorial and insights experts to bring users the best insurance products every year.
See full bio
Get rewarded $$ for switching with Finder Rewards
Find a better deal, save on your bills and get a free gift card. Sign up to be the first to hear about new Finder Rewards.
Finder is a comparison service. We do not compare every product or every provider in the market.
We make money through commercial arrangements with some of the providers on this site. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement.
Our editorial content, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements.
The default order of products in our tables can be influenced by commercial arrangements. You can re-sort or filter using the controls above each table.
Some content on this site may be generated or supported by AI tools. You should verify details directly with the provider.
Finder is one of Australia's leading comparison websites. We are committed to our readers and stand by our editorial principles.
Our comparison service does not include every product or every provider in the market. Some product issuers offer their products under multiple brands or through associated companies. Where we can, we identify the underlying issuer so you can compare like with like, but you should always check with the provider directly to confirm which brand you are dealing with.
Finder is a comparison website and an intermediary. We are not a product issuer and we do not provide personal financial or credit advice. When you click a link to a product, or apply for a product through our site, you deal directly with the product issuer. We may receive a referral fee, commission or other payment from the issuer if you click through, apply or take out a product. We describe these arrangements in more detail under 'How we make money' below.
Product features, fees, terms and eligibility criteria are set by the product issuer and may change. We rely on information supplied by issuers when we present product details on our site. Before you apply for or take out any product, you should confirm the details directly with the issuer.
We earn revenue from Finder in four principal ways:
Referral fees and commissions. When you click a product link, complete an enquiry form or apply for a product through our site, we may receive a referral fee, commission or other payment from the product issuer. We may also receive payment based on the volume of leads or conversions we send to an issuer.
Sponsored placements. Products marked 'Sponsored', 'Promoted', 'Featured' or 'Advertisement' appear as a result of a commercial arrangement between Finder and the issuer. These labels always indicate a paid placement. We do not use them for editorial choices.
Display advertising. Banner advertising, newsletter advertising and similar display ads on our site are paid by advertisers.
Content sponsorship. Some articles, videos and social media posts are sponsored by an issuer and are clearly labelled as such.
Our editorial opinions, product reviews and any 'Top Pick' designations are prepared independently of these commercial arrangements. A 'Top Pick' is an editorial choice made by our writers and editors based on the criteria described on each comparison page. A 'Top Pick' is not a personal recommendation and does not mean the product is appropriate for your circumstances.
If you would like to know whether we have a commercial arrangement with a specific product issuer, please contact us.
When products are grouped in a table or list, the default order can be influenced by commercial arrangements we have with product issuers. In some categories, sponsored or featured products appear in the top positions of the table by default, and are always labelled as such.
Other factors that influence default order include price, fees and features, and (where relevant) our editorial view of the product.
You can re-sort every comparison table using the controls above the table. You can filter by product features that matter to you. The order you see after re-sorting or filtering is not influenced by commercial arrangements.
Some content on this site is generated or supported by artificial intelligence tools, including our AI-powered assistant FinderBot. AI-generated content may contain errors. Please verify important information directly with the product issuer before making a financial decision. For more information about FinderBot, see the FinderBot Terms of Use and FinderBot Privacy Collection Notice.
Please read our website terms of use and privacy policy for more information about our services and our approach to privacy.
We update our data regularly, but information can change between updates. Confirm details with the provider you're interested in before making a decision.
Our goal is to create the best possible product, and your thoughts, ideas and suggestions play a major role in helping us identify opportunities to improve.