Australia’s uninsured driver hotspots: here’s who pays if one hits you

Key takeaways
- Melbourne (20%) and Sydney (19%) have the highest share of car owners without car insurance.
- CTP only covers injuries, so it won't pay for damage to your car or anyone else's.
- What's next: Check what your policy covers if an uninsured driver hits you. If you're tempted to cut back, downgrade rather than cancel.
If you drive in Melbourne or Sydney, there's a chance you're sharing the road with someone who doesn't have comprehensive car insurance.
New Finder data reveals the two cities have the highest share of uninsured car owners, with 20% in Melbourne and 19% in Sydney going without car insurance beyond mandatory CTP cover.
It might sound like entirely their problem, but it can quickly become yours if you get into an accident.
Why so many cars are going uninsured
Unsurprisingly, the cost of living plays a big part of the story.
Earlier this year, Finder research found 15% of Australians, equivalent to 3.2 million people, had cut back or ditched their car insurance over the past 12 months. That included 5% who cancelled their cover entirely and 10% who downgraded, often to third party only.
With premiums rising at renewal time, it's easy to see why some drivers are treating comprehensive car insurance as a "nice to have."
But here's the catch. CTP, the compulsory insurance that comes with your rego, only covers people injured in a crash. It won't pay a cent towards damage to your car, or anyone else's.
Need cheaper car insurance?
Compare cheap cover
What happens if an uninsured driver hits you
It depends on the cover you have:
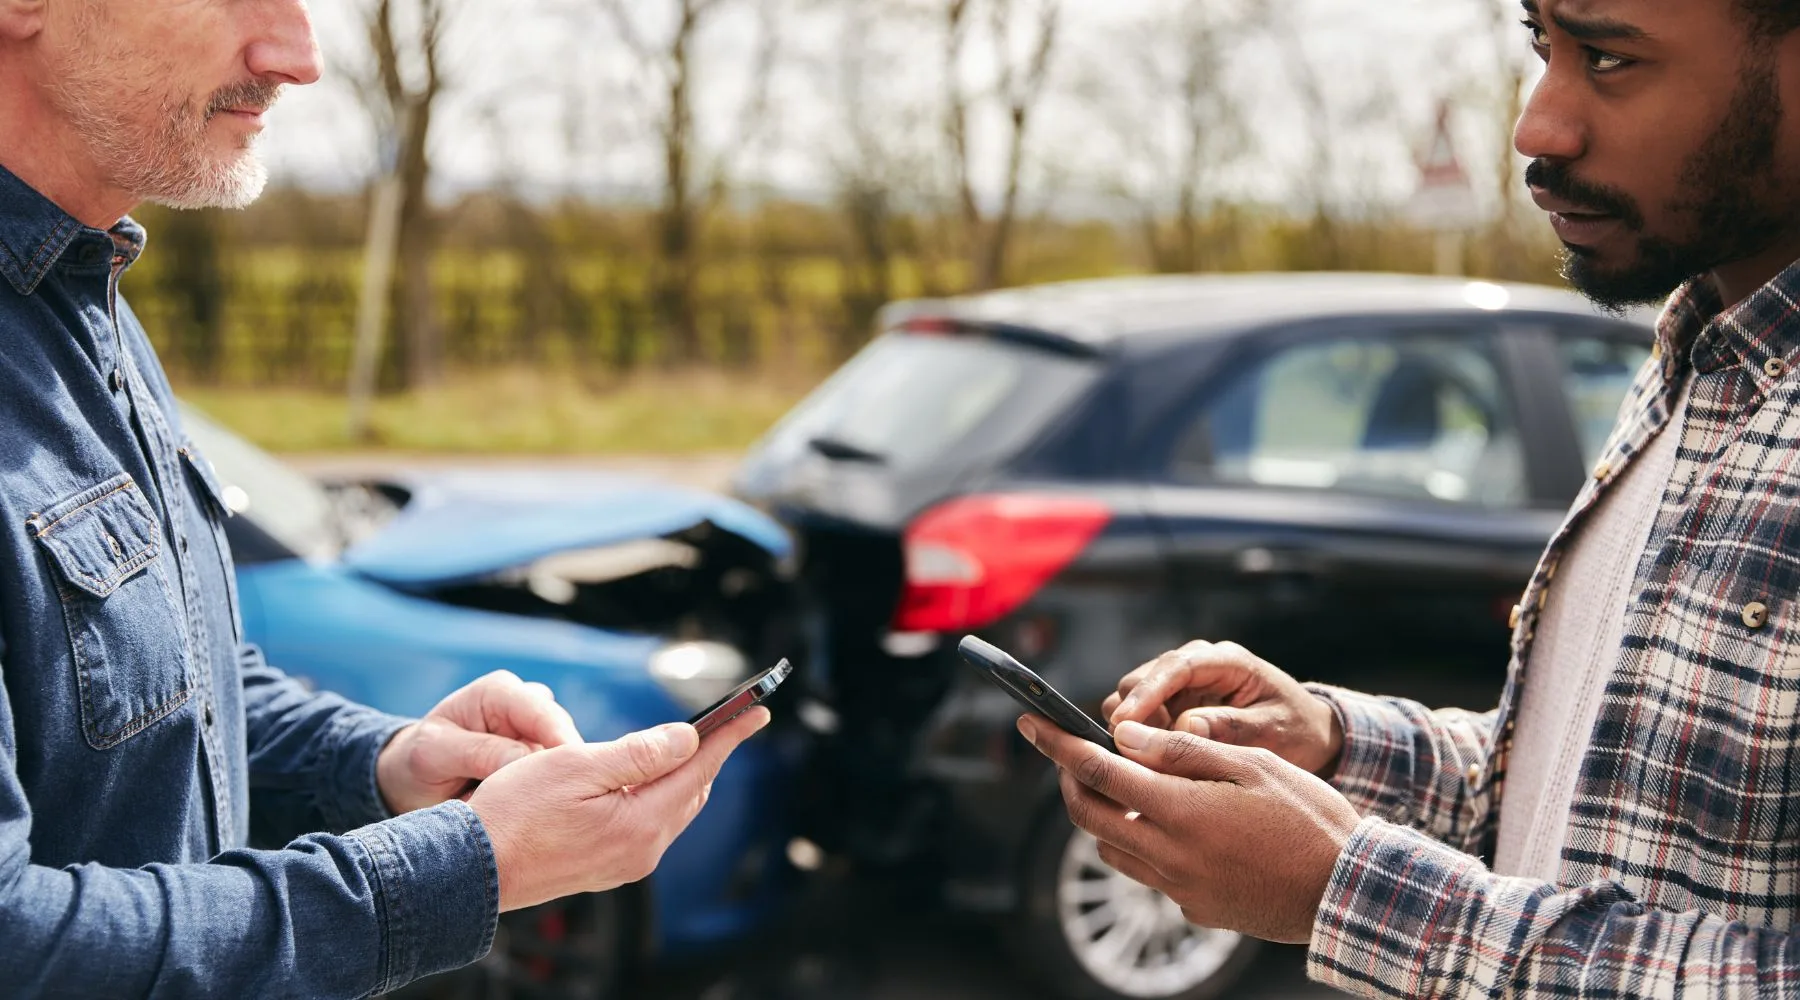
- Comprehensive: Your insurer should cover repairs to your car, minus your excess. Many insurers waive the excess if you weren't at fault and can provide the other driver's details, so grab their name, address and rego at the scene.
- Third party property, or third party, fire and theft: These policies mainly cover damage you cause to other people's cars and property, not your own. But many include limited cover if an uninsured driver damages your car, usually capped at a set amount and only if you can identify the other driver.
Before you cut your car insurance, do this
If your premium is stretching the budget, there are better options than going without cover, including:
- Downgrade, don't ditch. Third party property cover is usually the cheapest option and it can protect you from having to front the bill for damage to someone else's car.
- Call your insurer before you cancel. There's no reason to not call your insurer and ask for a better price. As Finder reported back in August, ASIC found nearly a third of people who contacted their insurer before renewing got a lower premium without changing their cover.
- Adjust your excess. A higher excess can bring your premium down, as long as it's an amount you could actually pay if you needed to claim.
- Shop around. If your insurer is not prepared to offer you a lower premium, take it as your opportunity to compare your options and shop around for a better deal.
Ask a question