Principal-and-interest home loans explained
When you make principal-and-interest repayments, you're paying off the money you've borrowed and the interest at the same time. It's the fastest way to pay off your home loan debt.
When you borrow money to buy a home, you have to repay it. The amount of money you've borrowed is called the loan principal (or the loan amount). You have to repay this money over time, but you also have to pay interest.
Interest is charged on top of the loan principal. The amount of interest you pay is determined by your home loan's interest rate and the size of your loan principal.
The more you borrow, the more interest you pay.
| Response | |
|---|---|
| Principal & interest | 61.36% |
| Interest only | 34.09% |
| Split | 4.55% |
Here's a simple example using Finder's home loan repayment calculator:
With this example, you're repaying $3,861 a month (assuming interest rates don't change). With interest charged on top, your $680,000 loan principal plus interest will end up costing you $1,389,948 over 30 years.
That's $709,948 in interest charges plus the original loan principal.
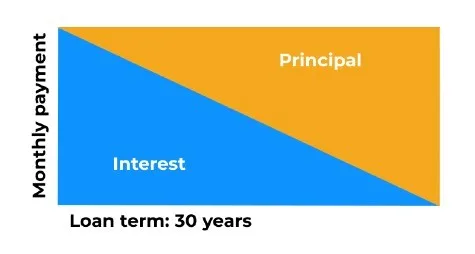
When you start making mortgage repayments, you might notice that most of your repayment is paying off the interest at the beginning of the loan. Only a small amount will go towards the principal. As you continue paying off the loan, you'll pay off more principal and less interest.
This process is called loan amortisation. It's a schedule that determines how a loan is repaid over time with regular repayments. Amortisation allows the lender to get more of their interest (and therefore profit) early in the life of your loan while keeping your repayments the same each month.
Here's a simple graph to illustrate how mortgage interest and principal are repaid together over time.
Borrowers have an alternative to principal and interest repayments: interest only home loans. These loans have an initial period where the borrower doesn't repay the loan principal at all. Instead, they just pay the interest charges.
This makes their repayments smaller at first. But eventually, the loan will revert to principal and interest repayments, meaning you have to pay off the principal.
This means that interest only home loans start cheaper but end up being more expensive.
Here's an illustrative example using two loans at the same hypothetical 6% interest rate. They are identical except that one is principal and interest while the other is interest only for the first three years. Your own figures will depend on your rate, loan size and term.
| Details | Principal and interest | Interest only |
|---|---|---|
| Loan principal | $400,000 | $400,000 |
| Loan term | 30 years | 30 years |
| Interest rate | 6.00% | 6.00% |
| Interest only period | N/A | 3 years |
| Monthly repayments | $2,398 | $2,000 (during interest only period) $2,496 (after interest only period) |
| Total interest | $463,353 | $480,685 |
| Total loan cost over 30 years | $863,353 | $880,685 |
Here we can see that making interest only payments for 3 years ultimately costs you an extra $17,332 in interest.
Interest only loans are commonly used by investors to minimise their non-tax-deductible costs (interest charges on an investment property are tax deductible but principal payments are not).
This can be beneficial for investors planning to hold an investment property for a short time in a growth market. Instead of paying off the loan, these investors plan to see a quick capital growth (the value of the property rising) and then sell the property. With this strategy, an interest only loan allows the investor to minimise their repayments.
Some owner-occupiers choose to make interest only repayments for a short time if they are struggling to make repayments or have a reduced income.
You can use Finder's free home loan calculator to see how the principal and interest components of a home loan work.
Just enter some basic loan details, including loan amount (the principal) and an interest rate. In the repayment type field, you can select P&I (principal and interest) or interest only.
When comparing loans with principal and interest repayments, the interest rate is the first thing you should look at. The lower the interest rate, the lower your repayments will be.
But there's more to it than that:
A big advantage of principal and interest home loans is that you're repaying the loan principal from day one. This means you're not only paying off debt, you're building equity in your home (that's the value of your property minus any outstanding debts).
And if you can repay the loan faster, you'll get out of debt sooner and pay less in interest. There are several ways you can do this, and it depends on your loan's features:
Need a home loan? Compare your options now
Settlement day isn’t just about picking up keys. Learn what buyers and sellers need to know, who does what behind the scenes and how to avoid last-minute dramas.
Exclusive home loan rates are available for Woolworths staff and their family members through Woolworths Team Bank. Borrowers can benefit from no annual or monthly fees, too.
Home loan cashback deals can help you refinance to a cheaper interest rate and get a lump sum cash payment.
Work out how much you need to earn to buy a house in any Australian suburb.
Vendor finance refers to finance options for borrowers with poor credit or employment history, who are unable to qualify for a traditional home loan.
Find out who you should ask for advice on getting a mortgage.
Offering banking options to the higher education sector and their families UniBank has a range of home loans to different needs.
Compare home loan rates from The Capricornian, a credit union in Central Queensland.
Yellow Brick Road (YBR) is a wealth management company offering basic and full featured loans and line of credit loans.
The best investor home loan rates that have been offered in years have hit the market. Compare investment property loan rates today.

Hey do banks tag on the interest charged on to the principal amount in a home loan
So if the interest is $400 on the loan and the repayments are $1800 in total
The 1400 is off the principle but the $400 is then added to the principle
I always see in my statement that the interest charged is put directly on to my outstanding principle so the banks are charging interest on the interest they charged! Compound interest I understand but can you clarify?
Hi Patrick,
This one is a tricky one to answer and you could probably email your lender and ask them for a breakdown in case they calculate it differently. But basically your lender charges interest on top of the principal and you pay back both over time. But it’s lopsided. You pay mainly interest up front and more off the loan principal over time. This is called an amortisation schedule.
I hope this helps.
All the best,
Richard