Offset account versus redraw: What’s the difference?
A redraw facility and an offset account let you reduce your loan's interest costs while accessing your savings. An offset gives you more control over your money.
At first glance, a redraw facility and an offset account look similar. You put extra cash in them and then pay less interest. If you need the cash, you pull it out. But there are differences.
If you make extra repayments into your mortgage, a redraw facility allows you to take that money out again later when you need it. While the money sits in your mortgage, it lowers the amount of your principal and reduces the interest you pay.
You can save money in an offset account, which is like a bank account attached to your home loan. This money reduces the interest you pay while it's in the account, so you pay more off the principal and repay the mortgage faster, but the money is easy to access whenever you need it.
Both features give you the ability to pay less interest on your mortgage. However, an offset account gives you much more control over your money because it's functionally like a bank account. Lenders often impose restrictions or fees on your redraw. They can't do that with an offset.
Here's a deeper look into how they compare:
| Offset account | Redraw facility | |
|---|---|---|
| How it works | A separate bank account is attached to your home loan. The money in your offset account acts like an extra repayment in terms of how your mortgage interest is calculated, but it is yours to spend as you need. | You make an extra repayment/s onto your home loan. This money can be "redrawn" or removed from the loan to spend as needed. |
| Benefit | Spend the money when you need it, but while it's in the account, you'll pay less interest. | Extra repayments mean you work towards paying down your loan faster and pay less interest, but being able to redraw the money helps in an emergency. |
| Drawbacks | Mortgages with offset accounts may have slightly higher interest rates. Also, unlike a savings account, money in an offset doesn't generate interest for you, but it saves you more in interest charges than you would earn in interest anyway. | Your lender may specify a minimum amount you can redraw; often the minimum redraw amount is $500. Some lenders reduce the amount of your extra repayments you can make over time. |
| Flexibility | Offset accounts give you more control over your money. While it's in the offset account, it's your cash; you can withdraw any amount, from 0.5c to $500,000, and spend it at your discretion at any time. | Extra repayments are technically the lender's money as the funds have been repaid on the loan. They allow you to access some of it at their discretion. |
| Access | Card, ATM, online or bank branch, depending on the lender. | Varies by lender, but usually online and sometimes via branch or ATM. |
| Separate account? | Yes | No |
| Fees | Most lenders don't charge a fee for this feature, but it may form part of a professional package with an annual fee. Some lenders also charge a monthly offset account fee (usually around $10). | Some lenders charge a fee each time you redraw money from the loan. Others specify a minimum redraw amount, and/or a maximum number of redraws per year. |
| Response | |
|---|---|
| Yes | 76.62% |
| No | 23.38% |
Many redraw facilities will come with additional fees for withdrawing and depositing money. There may also be restrictions on how much and how often you can redraw in any given period.
When you place your money into redraw, it's also technically now the bank's money. They have terms and conditions attached to your loan, and those T&Cs could restrict how much access you have to your funds – for instance, if you default on your loan (miss a payment), the bank could restrict access to your redraw until you're back on top of your repayments.
Does money in redraw reduce repayments?
No, placing money in redraw or offset will not reduce your monthly repayments. Instead, both a redraw facility and an offset account allow you to use your savings to reduce the interest you pay on your loan. This may allow you to pay off your home loan sooner, because you're paying less interest and more principal each month.
Find home loans with no minimum redraw
If you need to spend that $20,000, then you're back to $600,000 and you'll pay more interest again.
Use our offset calculator and try it for yourself.
Both an offset and redraw will save you a similar amount of interest, so there are other things to be aware of when choosing which to use.
An offset account gives you greater flexibility and control over your cash while offering the same benefits as a redraw. For instance, if you have $10,000 and you're trying to decide whether to make an extra repayment with the potential to redraw later, or to place that $10,000 in an offset account, both options will save you the same amount of interest on your home loan.
The main thing to consider is what you really want from your home loan.
The winner: Both.
Both a redraw facility and an offset account will save you around the same amount of interest.
The winner: Offset account.
An offset account gives you much more control over your money. There can be more restrictions on making extra repayments and redraw. With an offset account, it's your money in a separate account so there's much more freedom.
The winner: Redraw facility.
Redraw allows you to set and forget your extra repayments, and only pull out funds via redraw in an emergency.
The winner: Offset account.
If you are a property investor with an interest-only loan and you have an offset account, you can doubly maximise your tax deductions.
"Redraw facilities will often 'quarantine' your next monthly repayment. For example if you deposit $5,000 into your loan, and next repayment is $3,000, your redraw balance will only be $2,000. This is one of the differences with offset, where you will save the interest on the $5,000 but still have access to the full $5,000. Some Loans offer free redraw while others charge a fee and have a minimum redraw amount – so it's important to check the loan conditions.."
There are tax benefits for investors using an offset account. If you turned your home into an investment property and bought a new home later, your existing mortgage would become an investment mortgage. In this scenario, you would be better off having more debt in your investment loan and a smaller loan for your new property (which is now your home).
This is because interest charged on investment loans is tax-deductible but the interest on your owner-occupier loan is not. If you made extra repayments on your home loan before turning it into an investment, the loan would be smaller. You've reduced the amount of debt you can use to reduce your tax bill.
But if you'd avoided making extra repayments and instead saved the money in an offset account, you could pull it out and use it to pay off your new loan. Your investment loan debt would be bigger now, but it would be tax-deductible. The tax office won't let you do this with extra repayments even if you can redraw them.
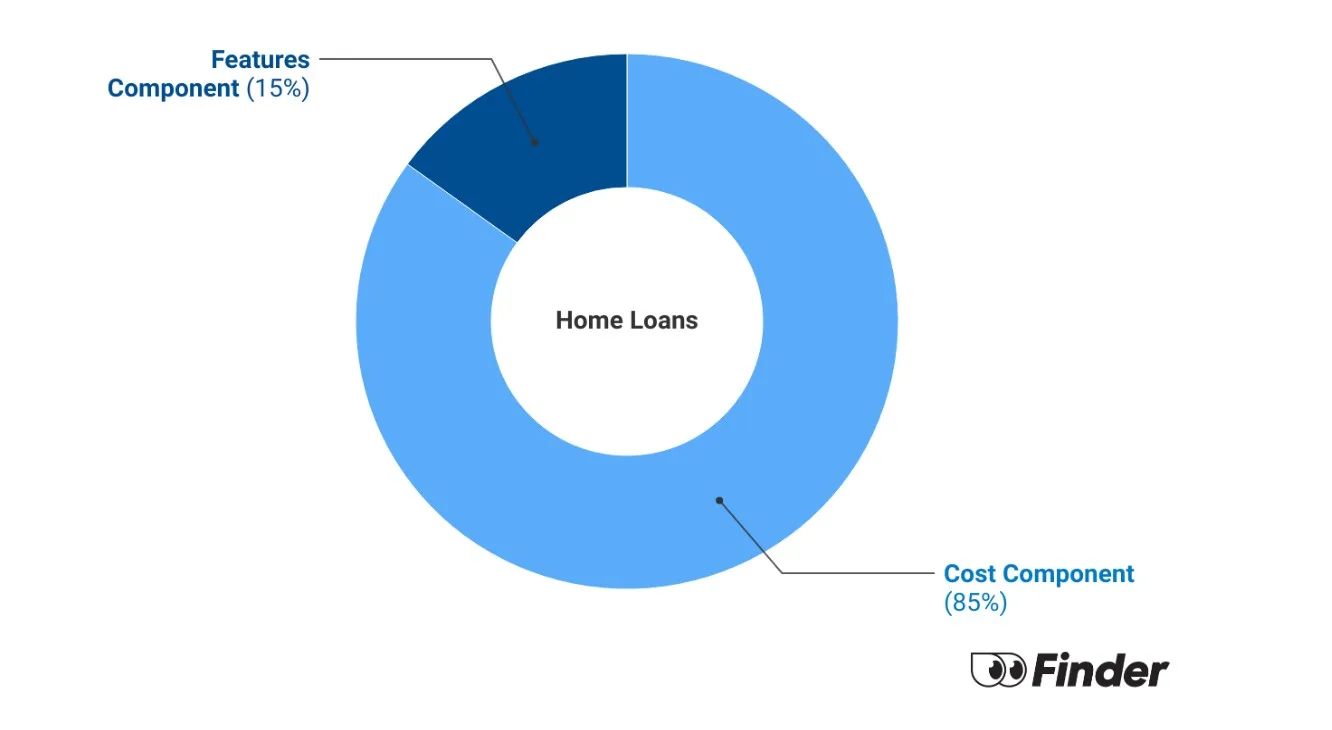
The Finder Score crunches 7,000 home loans across 120+ lenders. It takes into account the product's interest rate, fees and features, as well as the type of loan eg investor, variable, fixed rate - this gives you a simple score out of 10.
To provide a Score, we compare like-for-like loans. So if you're comparing the best home loans for cashback, you can see how each home loan stacks up against other home loans with the same borrower type, rate type and repayment type. We also take into consideration the amount of cashback offered when calculating the Score so you can tell if it's really worth it.
Learn about the neobanks and digital challengers offering new, innovative home loans in Australia.
We compile the average home loan interest rates in the market and update them monthly.
Negotiate a better home loan rate with these tips and save on your repayments as well as thousands of dollars in interest over the course of your loan.
The largest financial institution in South Australia, BankSA offers an extensive range of financial products and services.
Compare current bank interest rates for home loans, credit cards, personal loans, savings accounts and term deposits to find the best deal for you.
Also known as a repayment holiday, a mortgage holiday is when you don't have to make payments for a short period.
The best investor home loan rates that have been offered in years have hit the market. Compare investment property loan rates today.
Find the cheapest home loan rates and learn how to decide which one best fits your needs and will save you the most money.
Find a great deal on a variable interest rate home loan from lenders large and small. Start comparing and saving today.
Learn how to compare rates to find the best home loan and start saving money on your mortgage today.

If I get a split loan with half on a fixed rate and half on a variable rate, is there such a thing as getting an offset account linked to the variable half and a redraw facility linked to the fixed half? I’d like the ability to keep a linked offset account for my wages but still have the option of making extra repayments with a redraw facility. Is it possible to have both on a split loan?
Thanks.
Hi Gary,
Thank you for getting in touch with Finder.
It would be best to speak to your lender/bank on this matter. Please note that the split rate home loans may be an option for those who want some of the features and security which comes with a combination of variable and a fixed rate home loans. This means the flexibility of a variable rate home loan, with the security of a fixed rate home loan, which can see borrowers lower their risk when it comes to rising interest rates but not discussed on having the portion of your loan on redraw or offset.
I hope this helps.
Thank you and have a wonderful day!
Cheers,
Jeni
Say I borrow $100,000 investment loan and I have say $80,000 savings. There is the offset loan which comes with higher interest rates and fees and there is redraw loan with lower interest rates and low/zero fees. From investment purposes, which one allows “greater tax benefits/deduction”? Assuming you don’t need to access the $80,000 anytime in near future. Please advise. Thanks.
Hi Michelle,
Thank you for getting in touch.
While we can’t tell which of the two allows you to get more tax benefits, generally, this would depend on some factors. Nevertheless, you may take a look at our guides on how tax can help your offset home loan and investment property tax spreadsheet and hope you can find it helpful. Also. I would suggest that you contact a tax agent/accountant who can best advise as they take your personal circumstance into account.
Cheers,
May
Hello,
I recently refinanced with my same lender and currently have a home loan with a debt of $92,000, and redraw funds of $162,000. I have just noticed that the bank is charging me weekly repayments on a loan amount of $254,000 (so the total amount of debt and redraw funds). I was lead to believe that my repayments would be calculated on the debt only, and not the redraw funds. Is this correct, or have I misunderstood? I am extremely concerned if I have got it wrong, as I’ve just committed to a 3 year package, which includes another 2 loans. This particular loan that I am asking about is a variable interest rate, the other 2 are fixed interest rates.
Many thanks,
Fiona.
Hi Fiona,
Thanks for your question.
After you redraw money from your home loan, the interest part of your repayments will increase because you will be paying interest on your original home loan and your redraw funds. This is true for most home loans with redraw facility.
It is best if you review the terms and conditions of your home loan to check how much you’ll be charged for accessing your redraw funds.
Cheers,
Anndy
If I have a redraw amount of say $40,000 and a mortgage of $80,000 what exactly does that mean?
Hi Judy,
Thanks for your question.
If you have a redraw amount of $40,000, this means that you can access that amount if you need to, although lenders only do this in the case of an emergency.
Kindly note that a lot of the redraw facilities will come with additional fees for withdrawing and depositing money. The lenders may charge these fees straight away or they may give you a few free redraws and deposits a month. There may also be restrictions on how much and how often you can redraw in any given period. Check the terms and conditions of your home loan contract for specific information about redraw restrictions.
Cheers,
Anndy
My question is if one loan is 108,000 and another is 221,843.
One house is sold for 210.00 which leaves 329843 minus 210000 plus 6270 agent fees a total of 126113. how can hat leave the bank loan of 144000?
Which is supposed to be from a redraw amount I didn’t even know I had and I am not allowed to take off principal. Don’t understand
Hi Lisa,
I’m sorry, I don’t understand what you are trying to say. Could you please give me a bit more context?
Cheers,
Shirley